The carrot and stick of sustainable investment in real estate
Europe’s experience holds lessons for Singapore investors
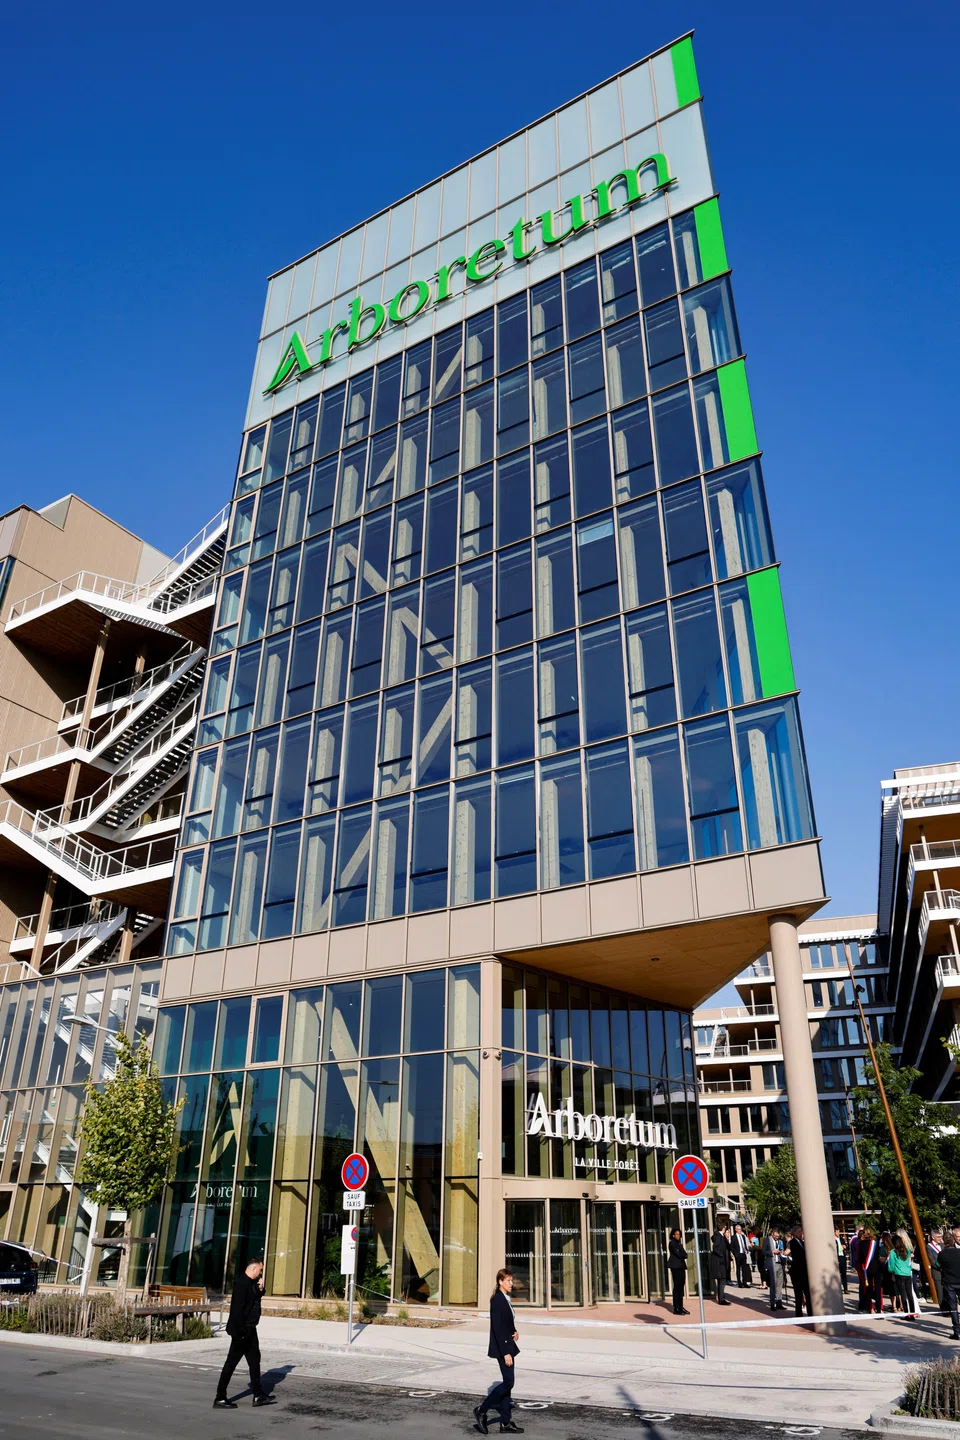
SINGAPORE has just raised its environmental standards for buildings, but Europe has already taken similar steps. What lessons can the Republic’s investors draw from Europe’s experience?
Earlier this month, changes to the Building Control Act were passed in Singapore’s Parliament for a new Mandatory Energy Improvement regime. This requires highly energy-intensive buildings to improve their energy efficiency or face a penalty of up to S$150,000.
The move is in line with the Singapore Green Building Masterplan and the shift towards a low-carbon built environment, and will contribute to the national commitment to achieve net-zero emissions by 2050.
Accelerating such energy efficiency improvements is crucial, as buildings account for over a fifth of Singapore’s carbon emissions and more than a third of its electricity consumption.
The investment case for greening buildings
The environmental impact of the real estate sector is much larger in Europe than in Singapore.
In the European Union, buildings account for 40 per cent of total energy consumption, 36 per cent of carbon emissions and more than half of the region’s electricity use. That is, in part, because many buildings are old and lack the latest efficiency features.
In contrast, Singapore has “greened” close to 60 per cent of its buildings in terms of gross floor area, with the target of raising this to 80 per cent by 2030.
In the EU, the main legislative instrument regulating buildings is the Energy Performance of Buildings Directive. Revisions to the directive, approved earlier this year, have increased the standards expected.
In the nearer term, the EU has set a goal of cutting greenhouse gas emissions in the building sector by 60 per cent by 2030; further ahead, similar to Singapore, the directive targets a zero-emission and fully decarbonised building stock by 2050.
There are two good reasons that real estate investors in Europe and elsewhere are increasingly prioritising sustainability in their portfolios: because they should, and because they must.
They should, because of the rewards for those who upgrade their assets. And they must, because, if they do not, their assets will soon become obsolete. These are, respectively, the carrot and the stick for Europe’s real estate market.
The pricing premium
Let us start with the positive side of this dynamic: the forces incentivising an early and comprehensive adoption of sustainability initiatives. The primary factor, as would be expected for investors, is the potential for superior performance.
The pricing premium for buildings with sustainability ratings is becoming substantial. In the London and Paris office markets, we observe that assets with a sustainability rating sell for averages of 29 per cent and 25 per cent more, respectively, than equivalents lacking such accreditation.
This is not coincidental; it is driven, and should be sustained, by fundamental supply-and-demand considerations.
On the supply side, the present pipeline of buildings under construction will not be enough to replenish the ageing building stock in Europe.
Three-quarters of the building stock in the EU was constructed before 1990. This has contributed to 65 per cent of the bloc’s buildings having an energy performance certificate rating of D or worse.
Better buildings are not coming quickly enough: London faces a low-carbon building supply gap of 35 per cent by 2030, according to JLL, while the shortfall is 54 per cent in Paris.
This lack of supply is set against an excess of demand. Put simply, owners and tenants both prefer modern, sustainable buildings.
For large corporate tenants of commercial property, real estate is typically a single digit percentage of their total cost base. Yet it accounts for around 40 to 50 per cent of all their direct carbon emissions.
This means that one of the most cost-effective ways for major businesses to meet their environmental ambitions – half of the world’s 2,000 largest public companies now have net-zero targets – is to pay a little more for a more sustainable building and thus slash their carbon footprint.
For residential occupiers, it is less about reducing emissions and more about reducing costs. Heating accounts for 78.4 per cent of energy consumed by European households, and it is becoming vastly more expensive.
Facing mandates
That is the tenants’ perspective of the imperative to go green. What about owners?
The largest investors in commercial property are long-term operators such as pension funds and insurers. Almost universally in Europe, they face mandates to incorporate environmental, social and governance criteria into their investments.
They are therefore systematic sellers of “brown” real estate and buyers of green property. As they have to work within multi-decade time frames, they do not want obsolescence risk in their portfolios – whether from a disappearance of buyers interested in inefficient buildings, or from their assets becoming stranded by rising environmental standards.
That takes us from the carrots to the sticks. Even if these older buildings do not risk obsolescence because of evaporating demand, they will become obsolescent under new regulations mentioned above.
No long-term investor wants to own buildings that will not meet standards – so there is a race to get out of these buildings as soon as possible, before they become essentially unsellable. This not only supports the premium for green buildings, but also creates a great opportunity set for investors looking at decarbonisation solutions.
Indeed, for investors who can add value by transforming assets from brown to green, there are exciting possibilities for arbitrage: buying older buildings cheaply from motivated sellers, upgrading and modernising them, and then selling them on to longer-term owners.
The results can be impressive. When we installed a heat pump and upgraded the ventilation systems at a data centre in Sweden, for example, we achieved a 62 per cent saving in the asset’s total energy costs.
Taking all this together, we see a K-shaped outlook for real estate: obsolete assets on a permanently downward trend, and a much brighter upward trajectory for modern sustainable buildings fit for the future.
The writer is global head of real estate and co-chief executive officer of Pictet Alternative Advisors