China’s mortgage boycott is the tip of the iceberg
The widening mortgage boycott can have a domino effect on stakeholders in the country’s real estate sector, and implications for emerging markets as well
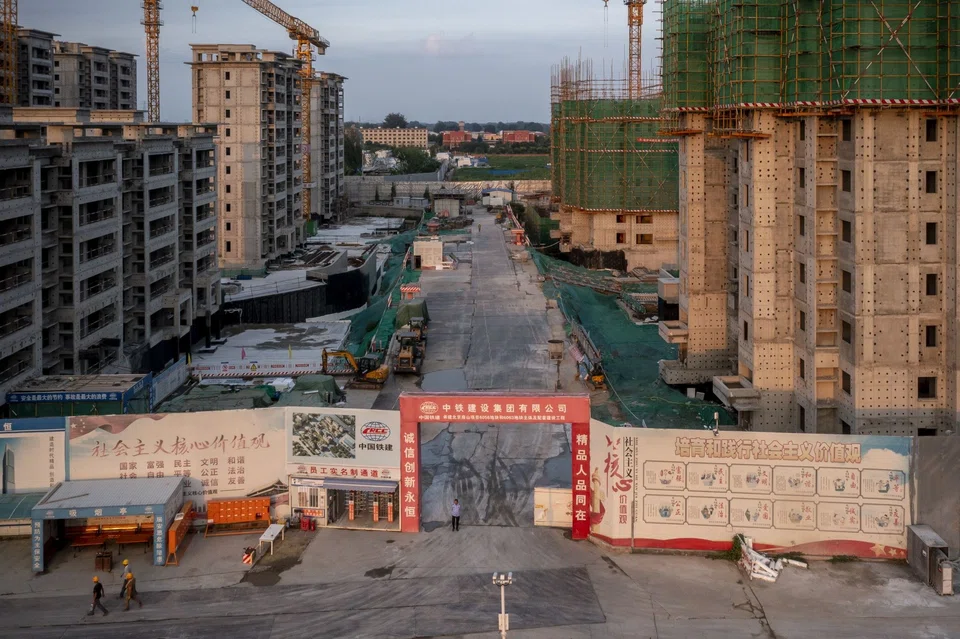
CHINESE property developers are desperate to recover from the prolonged zero-Covid lockdowns, but the mortgage boycott has complicated matters. When analysing the impact of the mortgage boycott which started in China a few weeks ago, it is easy to conclude that Chinese property developers are not out of the woods yet and, most importantly, the problems of China’s real estate sector are wider than the defaults we have seen from developers and are structural, not cyclical.
Since the fall of Evergrande last summer, homebuyers have taken centrestage in China’s real estate sector. The reason is that developers rely on pre-sales funding from homebuyers, but regulations and Covid restrictions have led to a rupture in the capital chain. Based on the public database, the home completion delay from the agreed schedule has reached 14 months. There are 821,000 units and the mortgage exposure, according to our estimations, could reach 735 billion renminbi (S$150 billion) or 2 per cent of total mortgages. As this is only part of the unfinished projects, it is important to estimate the likely maximum loss if all unfinished projects end up in mortgage boycotts. Our estimate is 2.3 trillion renminbi or 6 per cent of total mortgages.
The mortgage boycott can have a domino effect on other stakeholders, namely property developers, supply chains, banks, and the government. Defaulted developers will suffer the most as their unfinished projects are behind almost all mortgage boycott cases, including Evergrande, Sunac and Greenland. In other words, homebuyers have lost confidence in the completion of new housing projects and may prefer existing homes.
The latter does not bode well for the sector as the role of pre-sales in the financing of Chinese developers has continue to grow over time, reaching 86 per cent of property sales in the last 4 years. With the poor market sentiment, home-price growth has decelerated and home sales can fall as much as 30 per cent in 2022. It can affect developers’ ability to serve their debt and make payments to contractors.
Supply chains, ranging from upstream materials and downstream home appliances, are all potential victims. Any further spillover of the mortgage boycott is also bound to worsen banks’ asset quality and solvency. The non-performing loan (NPL) ratio for lending to real estate firms is likely to move above 4 per cent by end-2022 compared to 0.7 per cent in 2019. However, it is really the mortgages that can pose the biggest threats to banks as they account for 11 per cent of banks’ assets, higher than the 4.5 per cent exposure to real estate firms.
Chinese regulators are preparing for the likely worsening of banks’ asset quality by creating rescue funds. For example, the recently announced State Council’s rescue fund will involve 50 billion renminbi from China Construction Bank (CCB). It goes without saying that CCB will bear the brunt of this initiative as its solvency will deteriorate as a consequence.
More generally, the Chinese government will mobilise state resources to ensure the proper delivery of unfinished housing units, thereby reducing the potential mortgage boycotts. But the crux of the mortgage boycott is the lost confidence, which will not come back easily. With the never-ending mobility restrictions and regulatory changes, households prefer savings over property investment. Even though mortgage rates are back to the 2017-level, only 16.2 per cent of households expect higher home prices and 16.9 per cent have the intention to buy a home within 3 months in June 2022, lower than 36.5 per cent and 23 per cent in mid-2018.
That said, only Herculean actions from policymakers, which bring back confidence, may be able to put the tip of the iceberg back into the water. Barring this optimistic scenario, there are 4 important implications for China and Asia.
The most general implication is heightened systemic risk with a downward effect on China’s already low growth rate. In fact, property investment will continue to act as a major drag for the Chinese economy over the rest of the year and in 2023. As real estate can form up to a third of China's economic growth, the potential reverberations of this difficult situation will be large.
Another implication is China’s property sector may be increasingly geared towards state-owned firms, drifting away from the private-dominated era. Bakers need flour to make bread just as property developers need land to build houses. But the share of land purchases by state-owned firms has grown from 40 per cent before 2019 to 74 per cent so far in 2022. It shows that private firms find it increasingly difficult to maintain their original business model of high leverage and quick turnover, opening the door for state-owned enterprises to grow market share and buy cheap assets from troubled developers.
For Asia, a decelerating Chinese economy means its imports may weaken further, which is particularly problematic for commodity exporters. With a weaker domestic demand in property construction, China has been importing less iron ore, and we may soon see the same for crude oil and natural gas as China has been piling up reserves. The poor sentiment will affect emerging markets negatively with spillovers in asset prices and credit spreads.
In short, China’s mortgage boycott is another important risk to watch with its economic linkages with the Asian economies beyond the zero-Covid policy and the recent crisis in the Taiwan Strait. The grand clean-up of China’s real estate sector will be costly for all parties involved, such as developers, households and banks, and of course the state.
Alicia Garcia Herrero is chief economist Asia-Pacific and Gary Ng is senior economist, Asia Pacific (thematic research) at Natixis CIB