

Derivative-income funds offer attractive yields – if you can accept the trade-off
[SEOUL] Vetaran fund manager Hamilton Reiner, who pioneered equity premium income funds for JP Morgan Asset Management (JPMAM), speaks with a kindly, almost professorial cadence that belies his star power.
His brainchildren – JEPI, JEPQ and a host of other options-based exchange-traded funds (ETFs) and mutual funds – inspire blogs, Internet chatter and spots on YouTube channels. For the uninitiated, JEPI and JEPQ are the stars in JPMAM’s line-up of active ETFs.
JEPI is the ticker for the JPMorgan Equity Premium Income ETF, with exposure to the S&P 500. JEPQ refers to the JPMorgan Nasdaq Equity Premium Income ETF, which offers exposure to the Nasdaq 100 index.
Both ETFs use a covered-call strategy, deploying derivatives or options to generate income comprising option premiums and dividends from stocks.
At JPMAM’s recent Asia Media Summit in Seoul, chief executive George Gatch held up Reiner’s innovation as one that has hoisted the firm into a leading position in options-based strategies.
“We’ve been a pioneer in delivering derivative and options-based strategies that provide higher levels of income and lower levels of volatility. We launched our first fund with (Reiner) around 11 years ago, when there were 22 funds in the category,” he noted.
“Today, there are over 500, and JPMorgan has 50 per cent market share of the derivative-income capability. We pioneered bringing it from mutual funds to ETFs.”
JEPI was launched in 2020 and since then, its assets have ballooned to more than US$41 billion. JEPQ, introduced in 2022, has more than US$31 billion in assets.
Despite the ongoing bull market in US stocks – where investors would have done far better investing directly in the indices – the strategies have continued to attract inflows.
Research from financial services firm Morningstar shows that the category of US derivative-income funds, comprising mainly covered-call strategies, attracted a record US$31.5 billion in the first half of 2025.
In Singapore, three JPMAM equity premium income ETFs are registered – JEPI, JEPQ and JEPG. The last one is the ticker for the JPMorgan Global Equity Premium Income Active ETF, with the MSCI World Index as its benchmark.
All the funds are vehicles for Ucits – or undertakings for the collective investment in transferable securities – which are more tax-efficient for non-US investors. They are listed on overseas exchanges.
Options for outcomes, not leverage
“With over 35 years of investing in equities and equity options, I’ve always believed that options should be used for outcomes, never for leverage. I just don’t believe in leverage, personally or professionally,” Reiner said on the sidelines of JPMAM’s media summit.
“I was looking around the industry and there was not a lot of income in fixed income, and everyone likes income. It’s one of those things that are evergreen. I wondered, how can we potentially combine our ability to use equities and options to deliver income? That’s how we came up with the idea for JEPI.”
The managing director is also portfolio manager and head of US equity derivatives at JPMAM.
The strategy earns an income from selling one-month out-of-the-money call options on an underlying basket of stocks. But there is a trade-off: Investors have to be prepared to give up some of the market’s upside.
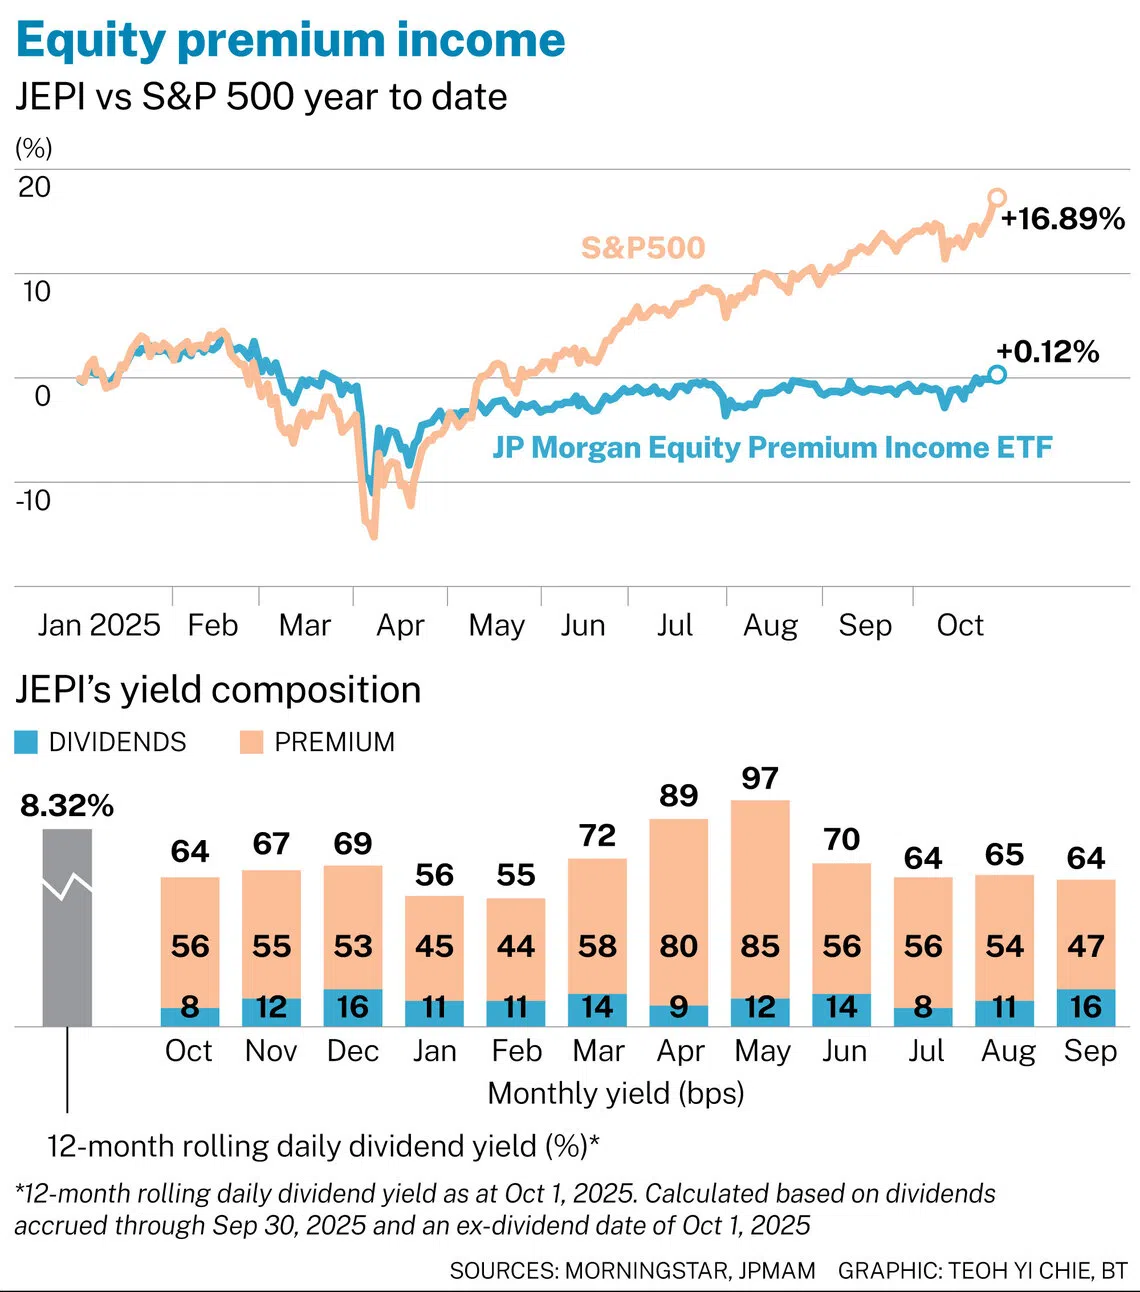
In fact, that trade-off has been quite costly in the past year. JEPI, for instance, returned 5.06 per cent in the year to Sep 30, compared with the S&P 500’s 14.8 per cent. JEPQ, meanwhile, generated a return of 10.12 per cent, versus the Nasdaq’s 18 per cent.
But it likely helps to think of such ETFs as a proxy for a credit investment rather than a straight equity exposure. In particular, investors with a long horizon and a diversified portfolio should be mindful of their objectives and such funds’ expected risk-return profiles.
Morningstar said of both JEPI and JEPQ: “In general, covered-call funds have not been the best buy-and-hold investments for investors with a longer time horizon. The stock portfolio’s upside is capped, and the downside remains exposed to significant drawdowns, which can erode an investor’s long-term total returns.”
On JEPQ, it added: “Using a relatively volatile underlying index amplifies call premiums, but also its tail risk.”
For JEPI, dividends comprise around 1 to 2 per cent of the yield; and the option premium, around 5 to 8 per cent. Dividends for JEPQ are typically lower at 1 per cent, and the option premium is higher at 8 to 10 per cent, thanks to greater volatility.
Up to end-June, the rolling 12-month yield on JEPQ exceeded 11 per cent; for JEPI, it was more than 8 per cent.
Mitigating risk
Reiner said the strategy’s exposure to high-quality names with predictable earnings helps to mitigate risk. Options are laddered in “multiple weekly buckets”, as Morningstar pointed out, to achieve a steady income profile.
“If you sum it together, you have a strategy with high-quality names, a monthly distribution of above-average income, and less beta,” he said.
“It’s a nice trifecta, from an investor’s perspective. They’re wonderful when markets are going up, and when stocks are going down, high-quality stocks tend to go down less.”
The investment veteran has 38 years of experience. He cut his teeth in derivatives through a nine-year stint from 1987 with O’Connor & Associates, where he was a derivatives floor trader and, later, the head of trading US floor derivatives. He joined JPMAM in 2009.
The total assets in JPMAM’s equity premium income strategy stand at around US$80 billion. When hedged equity strategies – with downside protection – are included, the assets run close to US$110 billion, of which ETFs comprise US$78 billion.
In total, JPMAM’s assets under management are about US$3.8 trillion.
Reiner said: “We’re very transparent with clients. If they want all the upside and therefore potentially all the downside, they should just buy the index… In a variety of environments, this strategy could add incremental value to your portfolio.”
In 2022, when stock and bond indices fell sharply, the funds outperformed. JEPI lost only 3.5 per cent, while the S&P 500 index fell 18 per cent.
Volatility is also lower. Since its inception, JEPI’s volatility has been 13.55 per cent versus the S&P 500’s 20.88 per cent. And JEPQ’s volatility has been 21.18 per cent, compared with the Nasdaq 100’s 28 per cent.
In addition to equity premium income, JPMAM has also rolled out a series of hedged equity ETFs, which use options as well for downside protection. The funds buy put options which cushion downside losses, but they also sell out-of-the money call options which cap the upside.
The value of such a strategy, said Reiner, lies in helping people stay invested through rocky periods. “Personally, I love the idea of a hedged equity ETF. I say to people: Are you ready to give up some of the upside in return for some protection on the downside? Very few would say no.”
He added: “Many things happen that affect people’s ability to stay invested. Attempting to time the markets is the biggest cardinal sin in investing. A hedged equity strategy helps people stay invested throughout, so I do believe they are an important part of portfolios as we move forward.”
TRENDING NOW

Fed hike throws Singapore banks a margin lifeline; UOB likely to benefit more

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Chagee, Mixue and Luckin won the market. Sustaining their edge is the harder part

Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet

