

Glide-path portfolio for the CPF’s LRIS: an idea whose time has come
Here are six reasons to revive the Lifetime Retirement Investment Scheme with a mechanism that lets investors ratchet up or taper off risk-taking
RECENT news that the Central Provident Fund (CPF) is reviving the Lifetime Retirement Investment Scheme (LRIS) is something of a surprise. It is welcome news and comes none too soon.
The LRIS was mooted by the CPF advisory panel in 2016. For around a decade since then, it would seem it lay dormant – until Manpower Minister Tan See Leng’s remarks in Parliament in January.
He said the Ministry of Manpower was in the “final stages” of studying the LRIS and how to support CPF members through an investment option “that would strike the right balance between risk and return”.
That statement alone would not have been convincing enough. But his response to MP Jamus Lim (Sengkang GRC) was, to me, the clincher. He said the framework of the LRIS would involve different combinations of stocks and bonds – in the form of a glide path, a mechanism which enables investors to ratchet up risk-taking when young, and then taper it off in their later years.
This is a significant detail and the first time the government has hinted at a type of portfolio. As I see it, now is the optimum time to launch LRIS for these reasons:
1. The technology exists
Glide-path funds have been in US since the 1990s. Even target-date or life-cyle funds use such a mechanism to dial up or down the risk exposures according to investors’ profiles, based on a pre-set time horizon which may be linked to the desired retirement age.
Target-date funds, however, typically have a specific maturity date. They do not allow customisation and would also impose a burden of relaunching new funds periodically to give new target-date choices, which is inefficient.
2. A more financially savvy public
CPF members are better educated today about investing and the need to generate returns that beat inflation. There are low-cost options within the CPF Investment Scheme (CPFIS), such as Dimensional Fund Advisors’ (DFA) funds, which neither levy a sales charge nor pay trail fees, and where the total expense ratio is 0.28 per cent a year.
But, as Providend chief Christopher Tan said, investor awareness of them is low.
And as I see it, there are still too many fund choices in the CPFIS – around 470, and most are equity funds.
The LRIS needs to be the one-stop option for simplified, low-cost portfolios which should have a form of advisory built in, that can prompt members to rebalance. Rebalancing ensures appropriate risk-taking and diversification, but it need not be prompted by age alone.
A strong bull market, for instance, will skew a portfolio’s equity allocation, making it more vulnerable to a market correction. The system should take into account recent returns, to nudge members to take some risk off the table and bring their strategic portfolio weights back to neutral.
3. It complements CPF Life
The CPF should think big on LRIS and think long term. That is, it should not just be an engine for retirement accumulation, but also for decumulation. Decumulation is proving to be a challenge even in developed markets like the US, where many retirees are in the dark on how much they can safely withdraw in retirement.
But the technology already exists to engineer this. DBS’ Retirement Portfolio is a robo glide-path portfolio with decumulation. It is customisable according to investors’ desired retirement age and target withdrawal income.
The LRIS – with a decumulation option – can sit alongside the CPF Life, an annuity scheme to provide income for life. This is important as Singaporeans are living longer. Living to your 90s means your savings have to last for 30 years or longer after retirement.
This is ample time to benefit from a moderate-risk portfolio which can beat inflation. CPF Life remains indispensable as a basic retirement income scheme. Beyond that, members with excess funds may wish to continue to invest in LRIS.
4. Strong, long-term returns from a balanced portfolio
The long-term returns from a balanced 60/40 (60 per cent equities/40 per cent bonds) portfolio are compelling, even taking into account the terrible 2022 experience, when stocks and bonds fell in tandem.
In Parliament, MP Shawn Loh (Jalan Besar GRC) pointed out that a “typical investment portfolio” of 65 per cent equities and 35 per cent bonds has earned 9.5 per cent annual returns over the past five years, and any further delay of the LRIS “may deprive CPF members an option to take risks to earn higher expected returns”.
Here is some longer-term data. Based on the quarterly guide to markets by JP Morgan Asset Management (JPMAM), a 60/40 portfolio (using S&P 500 for equities) returned 9.4 per cent a year over 20 years. On average US$100,000 invested in that period would grow to US$606,792 in 20 years.
Fear of loss has always been a worry for the CPF, but the historical data as captured by JPMAM – using the US market because that is the largest, most liquid with the longest returns – shows that the upward rise of market has been inexorable.
Over time, the average bull market has lasted 70 months and generated 221 per cent in returns. In contrast, the average bear market has lasted 14 months with negative returns of 39 per cent.
Obviously, the operative words are “long term”. CPFIS quarterly data discloses only short-term data for up to three years, which is not really meaningful.
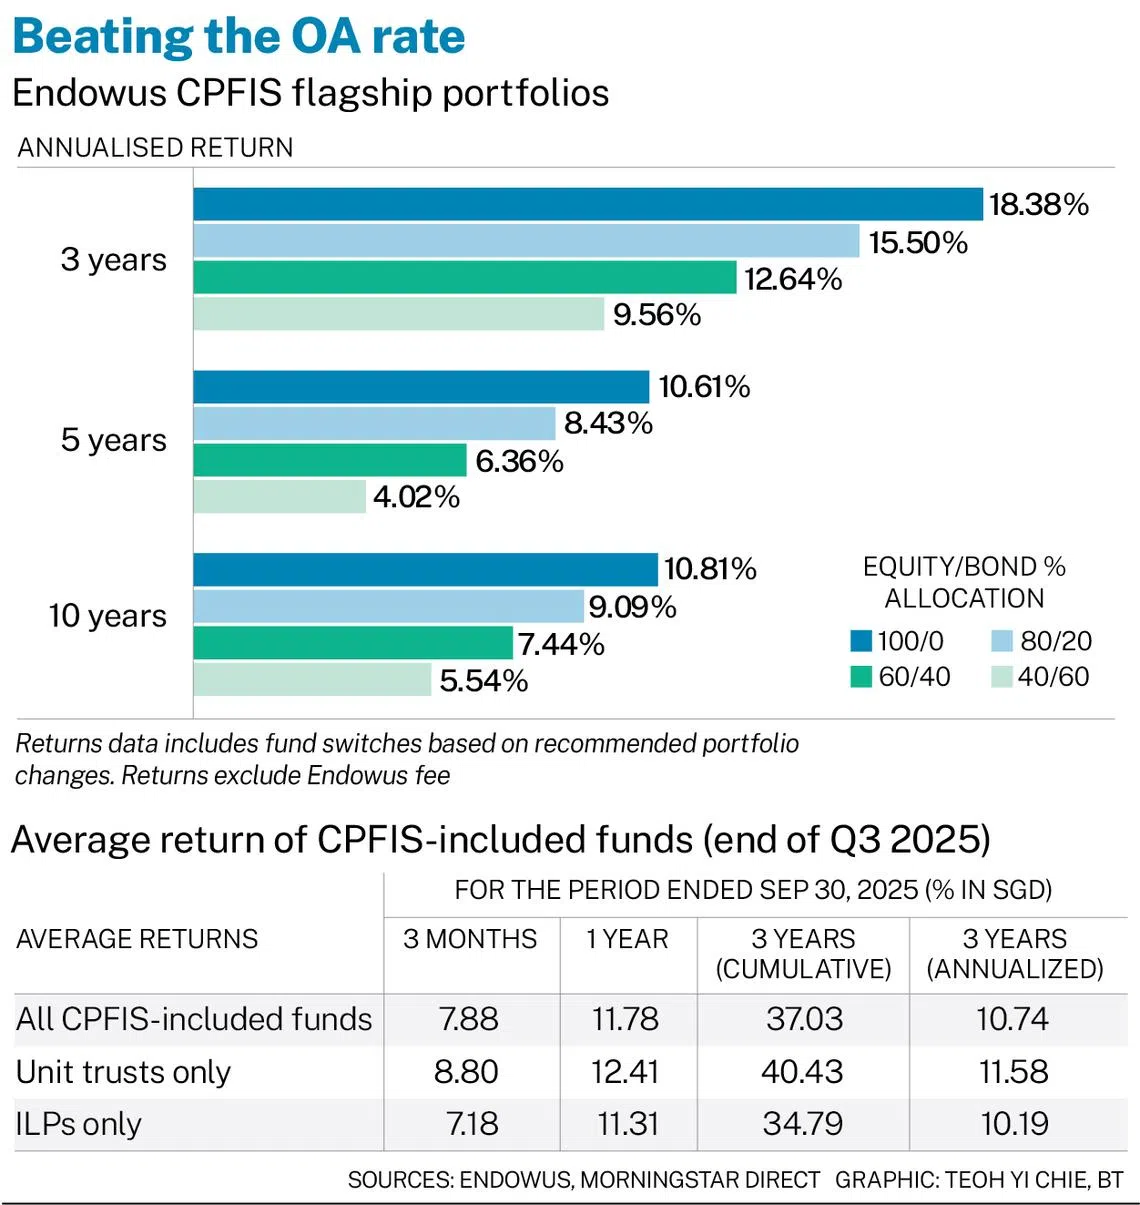
The accompanying charts reflect Endowus’ flagship portfolio returns. Various equity/bond combinations beat the Ordinary Account’s guaranteed rate of 2.5 per cent over periods of up to 10 years.
5. Right time for Singapore equities
LRIF portfolios are likely to have an allocation into Singapore equities, which are expected to enjoy a new lease of life, thanks to measures to boost liquidity and interest.
These measures include the S$5 billion Equity Market Development Programme, and the “Value Unlock” programme by the Monetary Authority of Singapore and the Singapore Exchange (SGX) to help listed companies reach their valuation potential.
JP Morgan Securities analysts have projected a bull scenario of the Straits Times Index at 6,000; DBS is even more optimistic, with a target of 10,000 by 2040. CPF members have been burnt investing in Singapore stocks, but these measures may well provide a turning point.
6. Customisation needed
What of advice? It is simple enough to call a tender, and providers of glide-path funds or portfolios will surely respond. But any offering must enable customisation in line with members’ profiles and retirement objectives, and risk rebalancing is a must.
Providend’s Tan is concerned that a glide-path portfolio “may not align perfectly with an individual’s specific risk tolerance or unique financial situation”. It is not always the case, he said, that a younger person has a greater tolerance for risk. It may also not be optimal for an older person to hold more bonds if they already have other bond holdings.
With the key criteria of lower costs, advisory within the LRIS may well be via a robo, something that younger Singaporeans are likely familiar with.
TRENDING NOW

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Income Insurance appoints former Manulife Singapore top man as new CEO

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

