

India stock market awaits catalysts
Despite supportive fiscal and monetary policies, the country’s market outlook remains subdued
INDIA is among the worst-performing markets this year. Year to date, as at Oct 28, the Sensex index only managed to deliver total returns of 1.4 per cent in Singapore dollar terms, trailing many global indices including the Kospi (58.5 per cent), MSCI China (35.4 per cent), and the Straits Times Index (21.5 per cent). This significant underperformance can be attributed to the following factors:
IT sector headwinds
India’s IT sector, which derives over half of its revenue from the US, has suffered from a cutback in discretionary IT spending by American firms amid an uncertain economic outlook. Adding to the pressure, US President Donald Trump recently implemented a one-time US$100,000 fee on new H-1B visa applications for skilled foreign workers, many of whom are employed by Indian outsourcing firms. In the near term, the growth and profit margins of these IT firms could face pressure, as contracts with US clients may need to be renegotiated to reflect higher manpower costs resulting from increased visa fees.
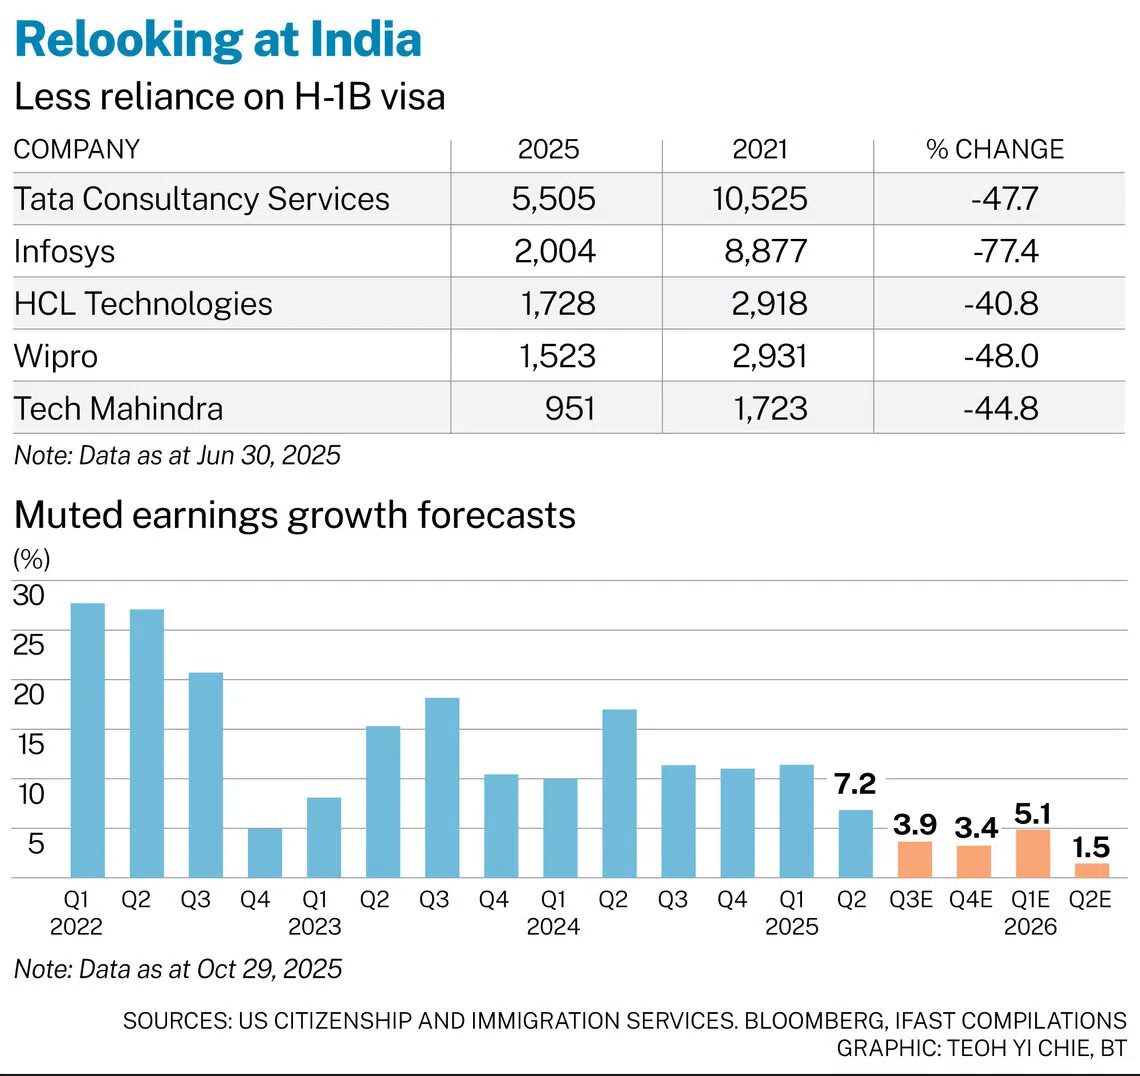
Despite this, we believe that the long-term impact to India’s IT sector will be manageable. Many Indian IT companies have already reduced reliance on H-1B visas over the years, and mitigation strategies such as nearshoring to US-adjacent countries like Canada and Mexico can help. Given the US’s reliance on affordable Indian tech talent, we expect the sector to retain its long-term importance.
Muted earnings growth coupled with elevated valuations
On top of IT sector weakness, India’s corporate earnings have also been mediocre as a whole.
Earnings for 2Q25 grew only 7.2 per cent year on year (yoy), while 3Q25 earnings, which are currently being announced, are projected to grow at just 3.9 per cent yoy.
This marks a slowdown from the double-digit growth seen in recent years. Yet, valuations have remained lofty, with the Sensex trading at 24 times forward P/E (price-to-earnings ratio), more than one standard deviation above its 15-year average of 19.6 times. The mismatch between weak earnings and high valuations has made investors hesitant to pour money into the Indian stock market.
Tariff shock from the US
Expectations of modest tariff hikes earlier in the year were dashed when the US government imposed a 25 per cent reciprocal tariff on Indian imports, followed by an additional 25 per cent penalty tariff due to India’s continued purchase of Russian oil.
The combined 50 per cent tariff rate now makes India the most heavily taxed Asian trading partner of the US.
While the direct impact on gross domestic product is limited – since exports to the US account for only around 2 per cent of India’s GDP – the indirect effects could be more substantial.
Export-dependent industries such as textiles and gems and jewellery, which employ large numbers of workers, may face declining orders, potentially weighing on employment, wage growth, and consumer spending. Weakened business confidence may also dampen private investment.
Collectively, the above three factors have dampened investor sentiment, prompting foreign capital outflows to markets such as Taiwan, Korea, and China, which are benefiting from AI optimism and domestic reforms.
Policy support from government and central bank
Thankfully, the Indian government and central bank have launched measures to bolster domestic demand.
In September, India streamlined its complex four-tier goods and services tax system (5, 12, 18, and 28 per cent) into two main slabs – 5 and 18 per cent – while introducing a 40 per cent rate for certain luxury and sin goods. Most goods and services now face lower rates, although a few categories have seen increases.
Overall, the reform should reduce compliance burdens and strengthen consumption in sectors such as consumer staples, autos, health care and financial services.
In addition to GST reforms, the Reserve Bank of India (RBI) cut policy rates by 100 basis points earlier this year to support lending and growth. With inflation remaining near the lower end of the RBI’s 2 to 6 per cent target band, there is further room for policy easing to stimulate India’s economy.
Stock market awaits catalysts
Despite supportive fiscal and monetary policies, India’s market outlook remains subdued. The disconnect between elevated valuations and sluggish earnings growth is expected to keep equities range bound until clearer signs of a corporate profit recovery or progress on a US-India trade deal emerge.
We expect the benefits of GST reforms and accommodative monetary policy to gradually feed through the economy over the coming quarters, with earnings growth likely to rebound only next year. Investors already holding Indian equities may continue to stay invested, while those looking to increase exposure might consider waiting until valuations become more attractive.
The writer is a research analyst with the research and portfolio management team of FSMOne Singapore, the B2C division of iFast Financial






