

Indonesia needs to 'get fiscal'
With state coffers down 9.9% in April, sound fiscal policy is critical to boost growth.
INDONESIA has one of the strongest structural stories in Asean, and we think 2015 likely marked the floor to growth. Our base case for this year is for a mild growth recovery to 5 per cent from 4.8 per cent in 2015. Given the tepid external environment - Morgan Stanley's global economics team expects global GDP growth to decelerate from 3.1 per cent in 2015 to 3 per cent in 2016 - we think fiscal policy is what's needed to lend growth alpha in Indonesia in this cycle.
However, the year-to-date fiscal revenue shortfall and its implications for government expenditure, as well as mixed trends in high-frequency macro indicators, have led to concerns about whether Indonesia's growth recovery is in fact happening.
Government revenue collection from January to April was down 9.9 per cent from the year before - a little less bad than the 12.8 per cent drop in the first quarter. A few things drove the government revenue decline in January-April, such as lower excise taxes owing to the front-loading of tax payments last year and a decline in non-tax revenue for natural resources as prices for commodities such as oil stayed low.
There was also a drop in value-added tax collections owing to tax restitution and a fall in non-oil-and-gas income tax. Last week, the Ministry of Finance said that government revenue collection remained in negative territory in January-May, although the decline was milder at -6.9 per cent year over year.
Given this weaker-than-expected revenue collection, the government has proposed revisions to the 2016 budget. They are expecting revenue to come in 4.8 per cent lower than the original plan and aiming to cut expenditure by 2.3 per cent relative to the original 2016 budget.
This would take the fiscal deficit from the originally targeted -2.2 per cent to -2.5 per cent of GDP. Even with this reduction, revenue and expenditure are still forecast to be up 15.3 per cent and 14 per cent over 2015, respectively, which seems ambitious to us. As part of these projections, the government is expecting the tax amnesty plan to raise 165 trillion rupiah (S$16.6 billion), accounting for 11 percentage points of revenue growth.
Despite the weak revenue collection, we think expenditure growth will not be weaker than the 1.1 per cent growth seen last year.
Our analysis suggests that even after accounting for what we think is likely to be tepid revenue growth of 0.8 per cent for 2016, government expenditure could still grow 3.8 per cent, a touch higher than the 1.1 per cent in 2015, while still keeping the overall government deficit within 3 per cent of GDP.
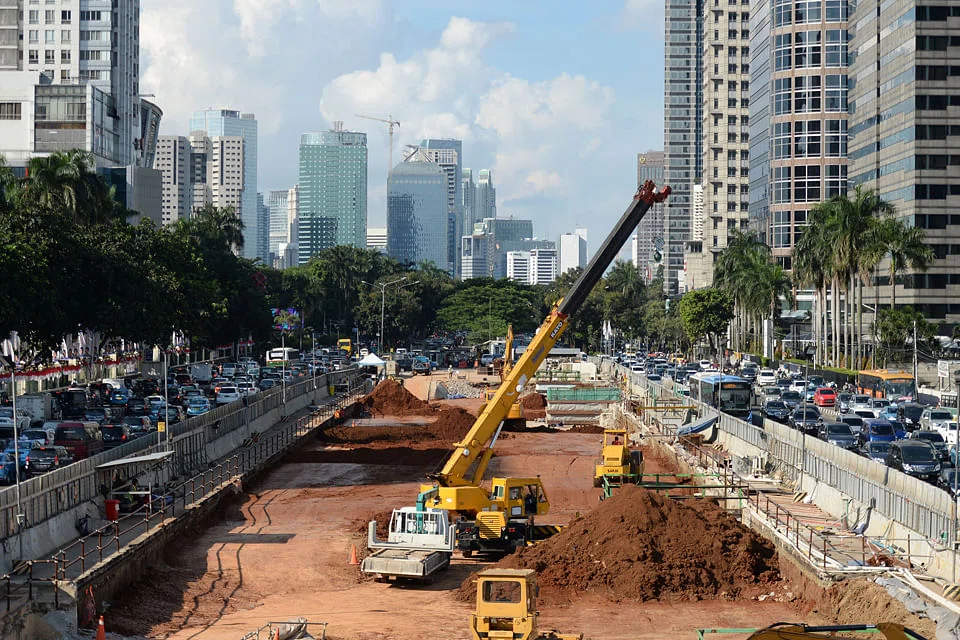
Clearly, such a pace of expenditure growth would not drive a V-shaped recovery in Indonesia and this has not been our base case. Nonetheless, we think a more efficient expenditure mix - where infrastructure constitutes a bigger share of government expenditure - should help bring about better multiplier effects and drive a mild growth pick-up.
Meanwhile, the finalisation of the tax amnesty policy is a fiscal event that markets are watching in the near term. Policymakers at Bank Indonesia and the Ministry of Finance expect the tax amnesty to raise revenue worth between 0.4 per cent and 1.3 per cent of GDP. While a tax amnesty would provide a near-term boost to fiscal revenue, what is more important is what policymakers do afterwards as part of fiscal reforms to improve tax compliance and collection.
A tax amnesty plan on its own will not have a positive impact on revenue collection in the long run if policymakers do not follow through on the information that the plan yields on taxpayers/tax evaders to increase compliance. In fact, if taxpayers think that yet another tax amnesty could be offered further down the road, it could even lead to reduced tax compliance and lower revenues.
In this context, increased tax scrutiny/compliance and the implementation of other revenue-enhancing measures (such as fuel levies, broadening of the tax base) would help to give a structural lift to government revenue in the medium term.
In addition, while there are concerns that continued tax scrutiny could pose a drag on the economy, we think that this scrutiny could bring about longer-term macro gains if it structurally lifts revenue collection. In a way, hoping for higher revenue collection (as a percentage of GDP) via fiscal reforms and assuming that translates into public spending is equivalent to swapping private sector demand for public sector demand in the near term.
Indeed, we have been arguing that Indonesia needs to improve competitiveness in non-commodities to offset the commodity terms-of-trade shock. Ramping up infrastructure spending is one of those ways. To the extent that there is a higher multiplier effect from productive public spending, this would still be a net positive for the medium term. Ultimately, this would help to crowd in and lift private sector demand.
The writer is an Asean economist for Morgan Stanley
TRENDING NOW
SoftBank’s Son plans US$50 billion Malaysia tech outlay: Anwar Ibrahim

Singapore expects all parties to honour commitments, says PM Wong after Indonesia cuts gas exports

Gas Supply may pursue remedies if contract breached following Indonesia’s export cuts: Tan See Leng

Why the biggest business decision about AI isn’t which model to choose

