

Longevity barbell: How to balance cash flow certainty with transformative upside
As societies continue to age, the convergence of sectors including healthcare and housing will increasingly define where sustainable growth and long-term value creation emerge
LONGEVITY has been a human ambition for millennia. What is new is its investability.
In the mid-2020s, we are at an inflection point: Science is moving from theory to application. Capital is forming around scalable platforms, and demographic ageing is a fact, not a forecast. In Asia, this combination turns longevity from a fringe curiosity into a core portfolio theme.
Here, a barbell strategy offers a balanced approach. On the defensive side sit near term, cash flow generators with clear demand and line-of-sight earnings. On the growth side sit longer dated, high-potential innovations that can transform healthcare and, over time, returns. This structure balances defensiveness and optionality, preserves discipline, and gives investors exposure to both the commercial present and the scientific future.
The defensive side: GLP-1 therapies and eldercare
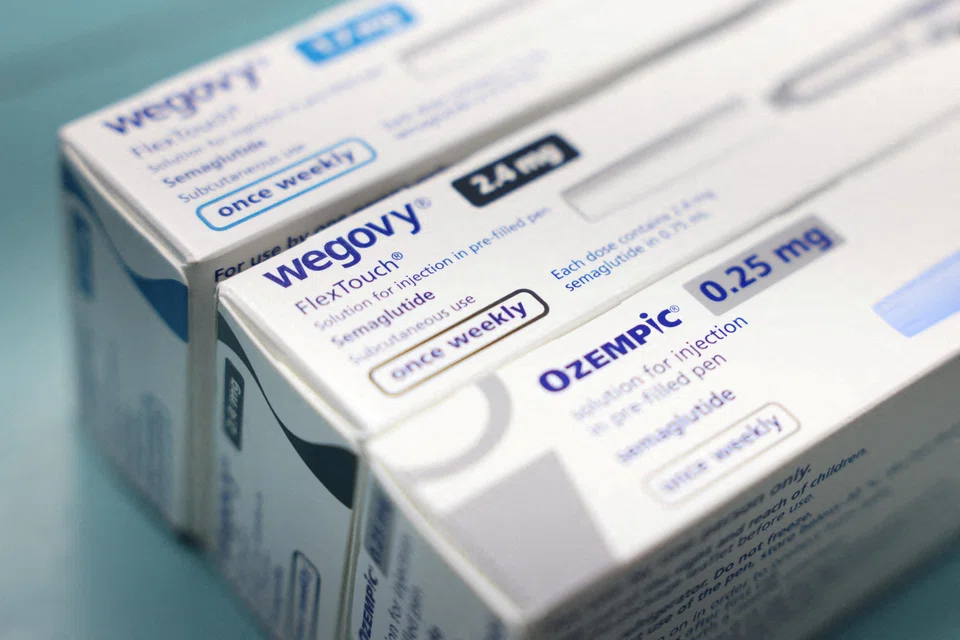
GLP-1 therapies – which use medications that mimic the natural hormone glucagon-like peptide-1 – have already reshaped obesity and diabetes care and are now expanding into cardiovascular indications. Revenues have scaled with unusual speed. Combined global sales of leading GLP-1 products Wegovy and Zepbound have risen more than 50 times since 2021 to US$13.3 billion in 2024.
Remarkably, H1 2025 sales are already approaching full-year 2024 levels. The pipeline is broadening, with approvals and real-world evidence supporting additional uses. Oral GLP-1 formulations are expected as early as 2026, an access catalyst for patients who prefer pills over injections.
In the United States, pricing and coverage steps, including the inclusion of obesity drug coverage within Medicare, are improving affordability and accessibility. In China, local production is likely to broaden access as patent timelines roll off (including Semaglutide’s timeline in March 2026). These dynamics support durable demand.
There are risks to manage. The surge in demand during 2022 to 2023 fostered cheaper, compounded versions of GLP-1 drugs. Safety concerns surrounding unverified compounded GLP-1 drugs have been documented, and litigation and regulatory actions are tightening standards. In light of this, investors should favour high-quality manufacturers with proven supply chains and robust compliance.
Eldercare is the other anchor. The greying of the population is structural. Senior housing supply is far behind demand in many markets. According to data from the National Investment Center for Seniors Housing and Care, only 4,000 new senior living units will be developed in 2025 and 2026 in the US, while demand growth would necessitate 100,000 new beds each year through 2040.
Yet, only a fraction of that is being developed today. At the same time, most seniors prefer to age in place, which supports home-health agencies, remote monitoring, and telehealth. For investors, eldercare often behaves like infrastructure: Occupancy and rents are driven more by demographics than the economic cycle.
Listed healthcare providers and managed-care companies with senior-focused models are direct plays. At the private level, speciality clinics, outpatient networks, and home-based service providers are attractive targets.
The growth side: gene therapy and cryogenics
In terms of frontier innovations, gene therapy has shifted from promise to proof. Since the first approvals in 2017, regulatory acceptance has accelerated. Crispr, a gene-editing technology once experimental, is now delivering early clinical results. In December 2023, the FDA approved Casgevy, a therapy for sickle cell disease and beta thalassemia that corrects faulty haemoglobin genes in bone marrow stem cells.
Tools once confined to rare monogenic disorders are being adapted to address the biological hallmarks of ageing – telomere attrition, genetic damage, and cellular senescence (a state where cells permanently stop dividing in response to stress or damage) – using viral vectors, lipid nanoparticles, and epigenetic programming.
This is not a straight line. Manufacturing viral vectors at scale is difficult. Clinical timelines are long; intellectual property is complex; and competition from other modalities is real. That said, platform enablers the likes of sequencing systems and contract development and manufacturing organisations are already commercial, helping reduce risk while preserving upside exposure to therapeutics.
Cryogenics is another enabling stack hiding in plain sight. It underpins IVF (in-vitro fertilisation), biobanking, and minimally invasive cryosurgery in oncology and dermatology. The cell cryopreservation segment alone is valued at US$1 billion in 2024 and is set to grow by over 20 per cent in terms of compound annual growth rate towards US$78 billion by 2034.
Scientific hurdles the likes of ice crystal damage and cryoprotectant toxicity remain, but the direction of travel is clear. As methods improve, organ preservation could become a practical bridge between donation and transplant.
The Asian lens
China and India are poised to become the epicentres of GLP-1 market growth in Asia, driven by the surging epidemics of diabetics and obesity, rapid expansion of healthcare infrastructure, and strong government-backed initiatives targeting metabolic health. Projections indicate that obesity prevalence in both countries will rise more than 200 per cent between 2010 and 2030 – a rate that far outpaces increases seen in developed economies.
Unlike the US where the access to these drugs is often constrained by high costs, insurance limitations, and supply chain challenges, China is poised for broader accessibility with anticipated lower-cost, locally produced alternatives.
These dynamics suggest the potential for rapid and widespread adoption of therapies within the Chinese market. With India set to follow China’s trajectory, their leadership will reshape the regional and potentially global landscape for GLP-1 therapies.
In Asia, rapid demographic shifts – particularly in Japan, South Korea, and increasingly China – are colliding with cultural changes as traditional family-based care is gradually giving way to institutional solutions. From an investment perspective, the sector is attractive on several fronts.
Publicly listed healthcare real estate investment trusts provide access to stabilised, income-producing assets, while private equity continues to fund development and operational platforms. Consolidation opportunities abound in fragmented regional markets where scaling operators can create efficiencies.
Taken together, Asia offers both demand depth and delivery innovation. The left side of the barbell compounds in markets that are already adopting preventive therapies and building care capacity. The right side benefits from the region’s growing role in clinical research and advanced manufacturing.
Investors do not have to choose between defensive cash flows and scientific ambition. The longevity barbell lets us hold both; cash flow certainty from proven therapies and care services, and exposure to innovations that can reshape health over the next decade.
In portfolios, as in medicine, balance matters. The objective is healthspan, not just lifespan: more years lived in good health, supported by disciplined capital. That is a goal worth compounding.
Beyond capital markets, longevity is driving innovation on the ground, as services and delivery models are reimagined to meet the evolving needs of ageing societies. As this demographic shift accelerates globally, solutions that enable ageing in place, improve care delivery and ease caregiving pressures are becoming increasingly critical – and investable – themes.
This is reflected not only in how we assess long-term investment opportunities, but also in how we support the broader ecosystem shaping the future of ageing.
Through initiatives such as the DBS Foundation’s Impact Beyond Award, we back innovative businesses across Asia developing scalable, technology-enabled solutions – from smart innovations that support independent living, to new senior living models and AI-powered platforms that better match caregivers with families – providing funding and capacity-building support to help scale their impact.
Together, these developments underscore a broader point. Longevity is not a single investment idea, but a multi-faceted ecosystem opportunity spanning healthcare, housing, technology, workforce development and services. As societies continue to age, the convergence of these sectors will increasingly define where sustainable growth and long-term value creation emerge.
The writer is chief investment officer, DBS Bank






