No bubble in AI, says JP Morgan Asset Management portfolio manager
‘Valuations don’t seem stretched to me,’ says Joseph Wilson
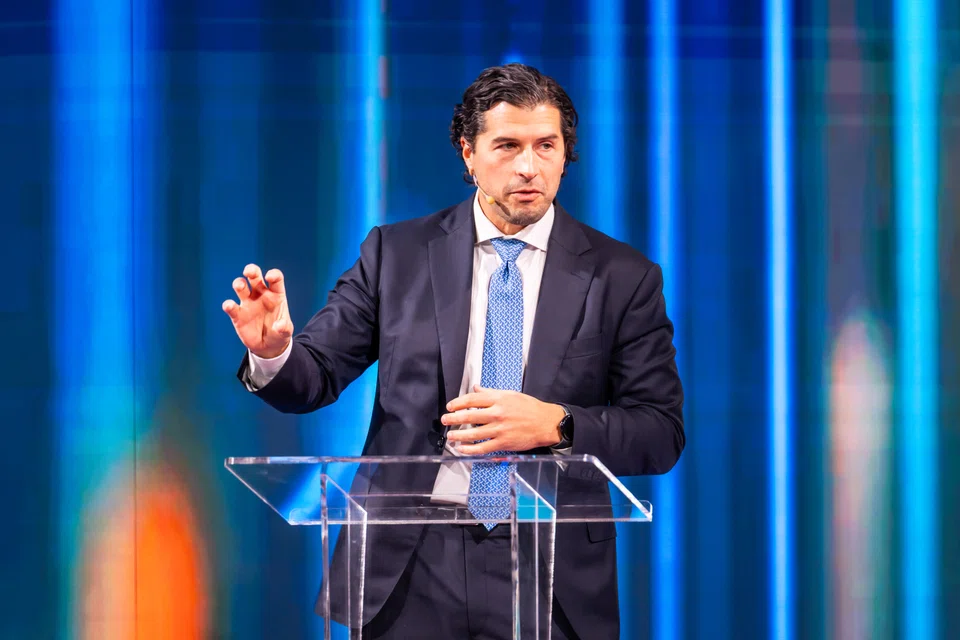
[SINGAPORE] Joseph Wilson, managing director and portfolio manager with JP Morgan Asset Management’s (JPMAM) US equity group, insists there is no bubble in technology and artificial intelligence (AI) stocks, because demand for AI infrastructure, services and applications far outpaces supply.
Wilson oversees the firm’s US technology strategy, which has total assets under management of US$26.9 billion. JPMAM itself manages a total of about US$4 trillion in assets.
Investor anxiety about overvaluation in tech and AI has driven sharp volatility. Nvidia’s strong set of earnings last week initially propelled markets upwards on Nov 20, but this quickly reversed and the Nasdaq ended more than 2 per cent down. The Nasdaq has since bounced by more than 3 per cent since that day’s dip.
“I think a lot about valuations,” said Wilson. “For every stock we own, we model an upside and a downside. Valuations don’t seem stretched to me. What seems more important from an opportunity perspective is that the next two, three and five years are underappreciated from a growth perspective. I think we’re right to be nervous about large capital expenditure requirements and the build-out for AI infrastructure.”
He noted, however, that at an industry level, “current demand still outpaces supply”.
“Today, data-centre vacancy rates are at record lows and utilisation levels hover around 80 per cent. Demand for computing continues to far outpace supply. More data has been created in the last three years than in all history, and AI workloads are also growing. We don’t see an immediate concern of ‘overbuilding’ as of now.”
A key indicator to watch, he added, is whether the substantial capex translates into profit margins down the road.
“So far, (companies) are seeing returns through increased cloud demand and productivity gains in coding, advertising and enterprise tools. But whether these growth rates in AI-related revenues are able to outpace growth rates in capex will be key. Monetisation is still a question for companies outside of the largest hyperscalers.”
Wilson is portfolio manager for the JP Morgan US Technology Fund, which has outperformed its benchmark, the Russell 1000 Equal Weight Technology Index, as well as the Nasdaq – while holding significantly less of the Magnificent Seven stocks than the Nasdaq.
The fund was incepted in 1997 and has US$8.8 billion in assets.
Morningstar has a “medallist rating” of neutral for the fund. It is rated above average for the people and parent pillars, and average for process. Morningstar said the portfolio is underweight in terms of its quality exposure and overweight in volatility compared to its category peers.
“Low-quality exposure is attributed to stocks with higher financial leverage and lower profitability,” it added.
The fund’s choice of an equal-weighted benchmark enables flexibility in stock selection.
“When you have benchmarks that have 10 to 20 per cent in a single name, even if you do not like the company and are underweight, you may still have a large amount of capital locked into a stock,” said Wilson. “This limits the ability to free capital to invest into emerging opportunities, companies that may be a double, or a 10- or 100-bagger.”
The fund limits the absolute size of its positions to between 5 and 6 per cent, depending on whether the stock is in the benchmark.
The fund’s top holding at end-October, for instance, was Nvidia, at 5.2 per cent, compared to more than 12 per cent in the Nasdaq. Its second-largest holding was software company Snowflake.
In the year to end-October, the fund returned 26.5 per cent, outperforming its benchmark (16.5 per cent) and the Nasdaq (22.9 per cent).
Wilson said the fund was an early investor in companies such as Nvidia and Tesla. “We invested in Nvidia in 2016 because we were becoming curious about GPU computing… We had a co-founder of a research group come in, and he told us that for the first time computers can see or hear at a human level or better. We thought that was great for investing in Nvidia.”
The team was also impressed with how Tesla was infusing AI into robotics and using software as a platform to differentiate itself.
“The only constant in technology is disruption,” said Wilson. “For every company that’s at the top of the market-cap leaderboard, we’re constantly thinking: What is going to disrupt them? Who is going to disrupt a Google or Meta in the future?”
He added: “What I’ve seen over twenty years of covering technology is that it’s very hard to displace the leader. The leader may not even feel any of the pain from the disruptor. But the alpha generated from the disruptor on that path of trying to disrupt is pretty great.”
Investors are understandably worried about overvaluation and timing risk. But the key, Wilson said, is to zoom out of short-term volatility, which feels nerve-racking.
“If you look at a company like Apple on a 20-year chart, you won’t see the little blip in 2008/09. If I look at a three- or five-year chart of a tech index or my strategy, there are a couple of times you might have a heart attack, because of the volatility… But if you pull back and take a 20-year view, the trend is linear. I think it shows technology’s importance to society,” he said.
“It shows how much technology you’re using this year versus last year, or five or 20 years ago. How much tech will you use in one or three years? We don’t know, but it’s more, whether it’s the car you’re driving in or a humanoid robot or an automated process.”