Opportunities in medium-term bonds as US yield curve steepens
Medium-term yields may drift lower as the Fed cuts rates, but likely in smaller magnitudes relative to each cut
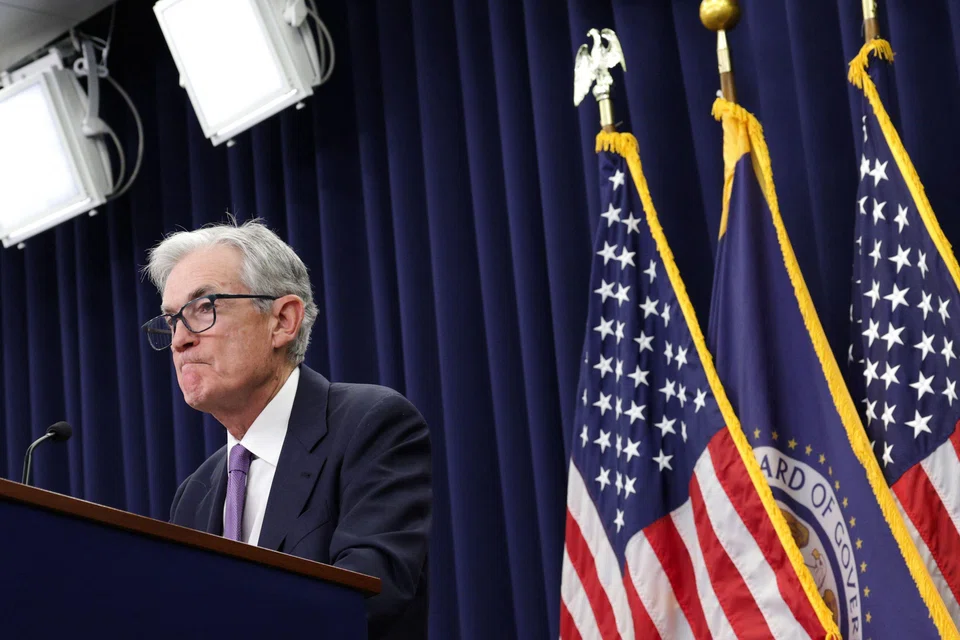
THE US Federal Reserve delivered two 25 basis point cuts in September and October. The latest move came amid a since-concluded US government shutdown, which temporarily contributed to gaps in inflation and employment data.
Markets quickly latched onto Fed chair Jerome Powell’s comments in October that a December rate cut was “not a foregone conclusion – far from it”.
The data gaps during the shutdown heightened uncertainty over the US economic outlook and likely contributed to his cautious tone. Other Fed officials have since pushed back against expectations for aggressive cuts, citing lingering inflation risks.
While markets were pricing in a near-certain December cut just a month or two ago, they now see the outcome as closer to a coin toss.
Labour market conditions have softened over recent months, with ADP reporting more job losses and slower hiring across many sectors, though not at levels signalling a sharp downturn.
In addition, inflation remains sticky across multiple measures. Consumer price index (CPI) inflation, for instance, remained around 3 per cent in September, while survey expectations for inflation from University of Michigan and Conference Board still sit above 4 per cent.
Given the uncertain economic backdrop, predicting the exact number of cuts is challenging even for professional investors. What seems more certain is that any easing will be gradual and data-dependent, as the Fed seeks to balance its dual mandate of maximum employment and stable prices.
For most investors, it would be more relevant to focus on the expected steepening of the US Treasury (UST) yield curve as cuts come through. Rate cuts will most directly impact the short end, where money market rates should fall roughly in line with the Fed’s moves.
Medium-term yields may drift lower as the Fed cuts rates, but likely in smaller magnitudes relative to each cut. Meanwhile, longer-term yields (10 years and above) may even face upward pressure from the risks of higher inflation expectations and/or fiscal concerns, even if we see modest policy easing in 2026.
Under this base case of yield-curve steepening, short to medium-term bonds look attractive to us, as they are expected to see larger yield declines compared to the long end.
Medium-term bonds can benefit from larger price appreciation due to their larger duration profiles. In addition, they can also benefit from “rolling down the curve”, or in other words, the natural price appreciation as their tenor shortens over time.
With these two drivers in mind, we think opportunities are emerging where the yield curve is steepest – currently, the five to 10-year tenors for USTs, and the two to five-year tenors for Singapore government bonds.
Meanwhile, there is also no urgency to rush out of short-term bonds.
In the US dollar space, yields on the front end (under six months) remain elevated and continue to offer a compelling source of low-risk income.
While short-term yields may eventually fall as the Fed eases, we still see some distance to go before longer-term yields become definitively attractive on a relative basis.
Taking these together, we favour a mix of short-term and medium-term bonds within a fixed income portfolio. Short-term bonds provide portfolio stability at attractive yields, while medium-term bonds allow investors to lock in yields ahead of further rate cuts.
As the Fed continues easing, we expect short-term yields to trend lower, which may broaden the opportunity set in medium-term bonds.
As for longer-term bonds, investors here should be mindful of the higher associated risks and volatility due to their naturally higher duration.
We do not yet see sufficient yield pickups over short-term bonds today, and prefer to wait for the yield curve to first steepen sufficiently. For now, we think longer-term bonds are more suitable for those comfortable locking in yields over a longer time horizon, or for traders looking to benefit from the price volatility.
Within the short and medium-term bond universe, our broad preference is for investment-grade bonds. While spreads have tightened significantly over the past years, all-in yields still look attractive at generally 4+ per cent for BBB-rated US dollar bonds, and can help to buffer total returns over time.
As with USTs, there is value on the steepest part of the curve – also in the five to 10-year range – where a large part of the investment-grade bond universe currently sits.
Even if economic conditions worsen globally, investment-grade bonds are expected to hold up better versus riskier market segments.
To summarise, we prefer high-quality bonds with short to medium tenors. With the Fed looking to cut rates gradually into 2026, investors may wish to gradually rotate out of cash-like products into medium-tenor fixed-income instruments.
We reiterate that the steepest parts of the yield curve are where opportunities seem most compelling in general.
The writer is a senior analyst in the Bondsupermart team at iFast Financial, the Singapore subsidiary of iFast Corporation