

Political stability in emerging markets is good news for debt investors
Election outcomes across the developing world appear to support growth as US elections loom
FOR most of 2024, the global backdrop has been supportive of emerging-market debt, despite rising geopolitical tensions.
More than 70 countries – representing more than half of global gross domestic product – undergo pivotal elections this year, and while geopolitics remains a headwind, election outcomes in key emerging markets thus far should provide some level of comfort for investors.
First, in a welcome break from the past, elections have generally been free and fair, with no major violent events – Venezuela being an exception, though it is unlikely to cause contagion in the region beyond immigration issues for the US.
Second, incumbents have largely stayed in place, though some saw their support reduced and others formed coalition governments. None of the elections will likely lead to significant global shocks or dislocations in the short term, but investors need to keep an eye on how each country manages their fiscal responsibilities and courts foreign investment from the US and China.
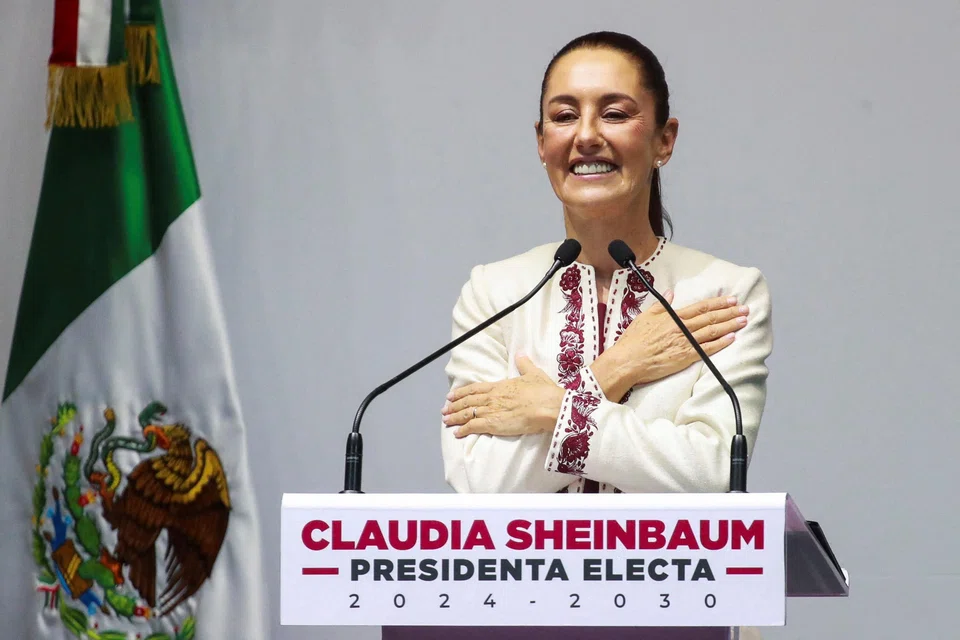
Among major emerging-market economies, one surprise was the strong margin of victory for Mexico president-elect Claudia Sheinbaum. Endorsed by the popular outgoing president, Sheinbaum and her party won a near-qualified majority in Congress, granting the ability to implement constitutional reforms.
Many of the proposed reforms seek to address corruption and inequality, however some amendments risk weakening democratic institutions or imposing greater permanent fiscal burdens. Mexico’s current fiscal deficit of near 6 per cent of GDP already demands strong consolidation efforts to reach a 3-per-cent-of-GDP target next year.
Despite the fiscal risks, Sheinbaum should be more supportive of US nearshoring efforts and public-private investments than her predecessor. For now, Mexico’s investment grade status is stable, but investors should monitor nearshoring inflows, the nature of energy reform and the extent to which Banxico remains independent, as well as US Fed expectations and strength of the US dollar.
In South Africa, the African National Congress party, in power since the fall of apartheid, lost their simple majority – raising fears that coalition partners might demand radical policies.
Fortunately, President Cyril Ramaphosa and his pro-reform faction formed a coalition with parties that largely share his pragmatic economic approach, boosting hopes of policy continuity and structural reform. The country is rich in minerals coveted by the US and China, and needed for the global energy transition to renewables. However, the challenge of reforming the South African economy likely belies a rapid turnaround in macro performance.
In India, Prime Minister Narendra Modi will serve a third term, which was won by a smaller margin than expected. Post-election, the Indian stock market sold off dramatically before rebounding.
India is becoming a more important participant in global production chains and will remain exposed to disruptions in global trade, especially electronics. Spreads look fair to attractive in select India corporates and quasi-sovereigns, and the FX and rates are performing more in line with other emerging markets. Major risks will continue to arise from global commodity prices.
Of course, the outcome of elections in the US may make the biggest impact on emerging markets. Any new restrictions on trade with China or more broadly, under a Trump or Harris administration, will cause deflationary dislocations across the region. An economically weakened China will hurt emerging markets, especially in the short term, because it implies less financing and less demand for global commodities.
While political risk has long suppressed emerging-market valuations, more election cycles of relative calm will only help stabilise the dynamics that make emerging markets attractive investments.
The US and China continue efforts to bring emerging-market countries into their orbits, current yields in hard currency sovereigns are near 6.25 per cent (providing a buffer for near-term spread volatility or rising US Treasury yields), and the growth differential between emerging and developed markets remains above 2 per cent, a historical indicator that emerging-market bonds will outperform US high yield.
The outlook for emerging-market corporate spreads is still favourable despite spreads at the tighter end of the range; the spreads are still attractive relative to US high-yield corporates, with a yield of 7 per cent on what is an investment grade asset class.
The best value remains in emerging-market BB-rated corporates at current spread levels of 320 basis points (bps) and select longer-dated BBB issuers at spread levels around 175 bps. Emerging markets’ local rates have underperformed core rates, but a US economic slowdown and rate cuts on the way could provide a tailwind to an oversold asset class.
The writer is head of emerging markets debt at PGIM Fixed Income
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

If AI has a one-in-five chance of destroying us, what do we do with the remaining four?

