

Private credit: A crowded space for large deals, but healthy pipeline for smaller ticket sizes
Funding gap in Asia to serve small and medium enterprises signals potential growth
Raphael Lim
INVESTMENT firm Muzinich & Co expects greater competition for large-cap private credit deals in Asia-Pacific. But the pipeline remains healthy in smaller ticket sizes.
The firm, which specialises in corporate credit, also believes there are opportunities for more non-bank financing to take place in the region.
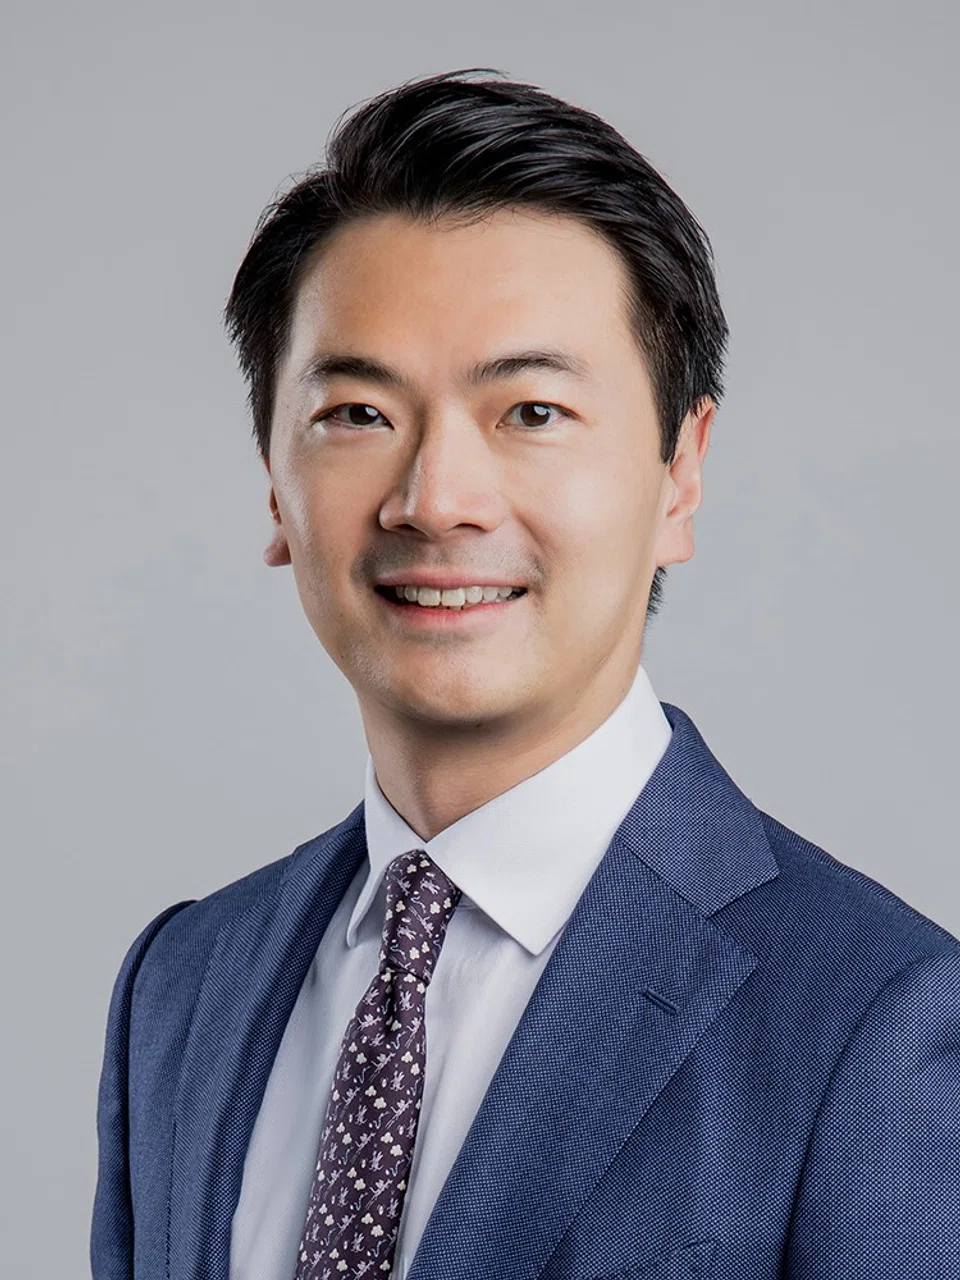
Andrew Tan, Asia-Pacific chief executive of Muzinich & Co, told The Business Times in an interview that there are two markets at play, with most funds being raised for the large cap or the upper-middle segment of the market.
“They are chasing transactions where they can deploy at least US$100 million or more in a single ticket transaction. That space is a little bit crowded,” he said, noting that large-cap acquisition financing volumes are down in the region.
However, there is still a “healthy pipeline” in the smaller ticket sizes ranging between US$15 million and US$50 million.
“A lot of smaller, mid-market, private equity guys are buying companies from second or third generation family-owned businesses, because the second or third generation is not looking to to run the business,” he added.
Private credit has seen growing popularity in recent years.
Citing Preqin data, Monetary Authority of Singapore (MAS) executive director Lim Cheng Khai said in a speech in March that total assets under management (AUM) in private credit had grown from US$342 billion in 2011 to US$1.4 trillion in June last year. This is also projected to grow further to US$2.3 trillion in 2027.
The growth is driven by demand from companies which find it more challenging to borrow from banks, which are facing stricter regulatory requirements.
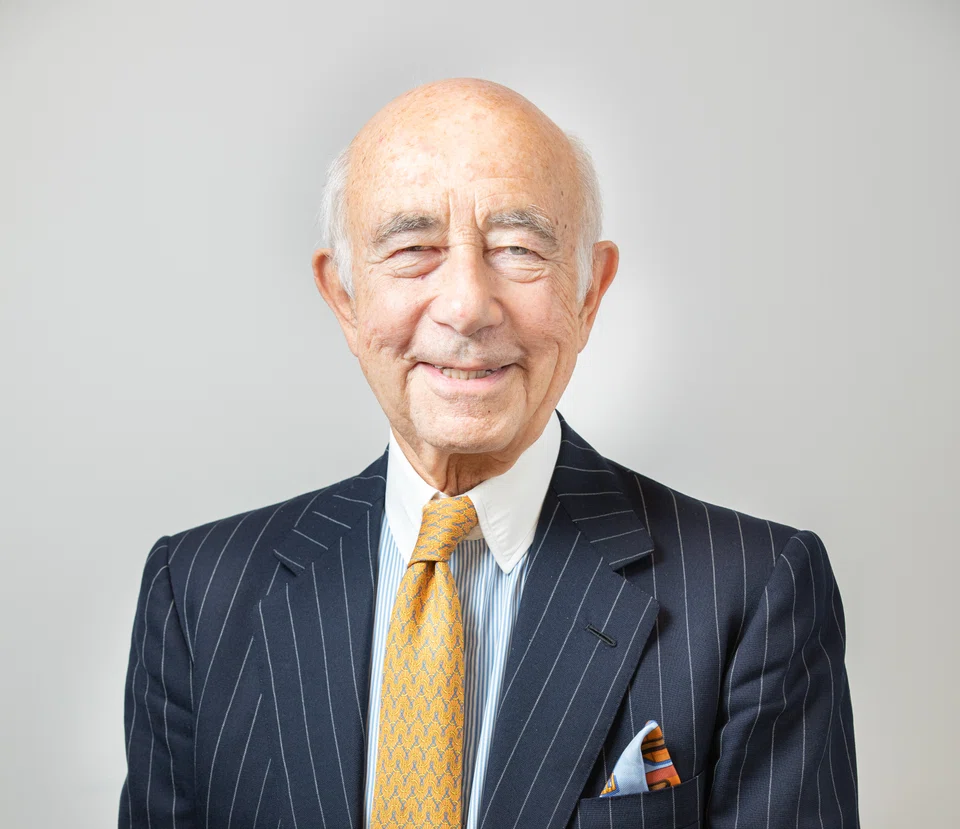
Muzinich & Co founder and executive chairman George Muzinich said: “What we do is work with the banking system to provide longer-term financing, flexible financing, to companies which… need longer-term cash flow financing, as opposed to purely asset-based financing.”
He noted that in the United States, capital markets account for over 70 per cent of financing, and under 50 per cent in Europe. This is significantly higher than Asia, where non-bank financing only accounts for around 30 per cent of financing.
Tan believes “there’s room to grow”, given the funding gap for small-to-medium enterprises that are underserved due to tighter bank regulatory capital requirements.
Muzinich noted that in public markets investors are largely “takers” of what the market offers, whereas in private markets, they are able to set the investment terms.
“You make your own conditions… you tell the business, I want this kind of covenants, I want this kind of return, I want this to protect myself,” he said.
Private credit is also a hedge against inflation as deals are done with floating rates instead of fixed rates. Tan added that the premiums are typically between 200 basis points and 400 basis points above the public market.
In July, Muzinich & Co announced the final close of its US$500-million Asia-Pacific private debt fund to provide funding solutions for underserved core and lower middle market companies in the region.
The recent popularity in private credit investing comes as rising interest rates result in better yields for investors.
A Schroders report last month noted that the new market regime has led to “enticing yields”, and an environment in which the pendulum has swung in favour of creditors instead of asset owners for the first time in many years.
The authors observed that cashflows of leveraged companies are no longer directed principally to equity holders, but are also directed to creditors. “We see a broad range of opportunities to put money to work in performing high-yield credits today in the 7-11 per cent yield range,” they said.
Muzinich said that the era of zero or negative interest rates over the past decade or so was an “artificial world”.
“You had an enormous amount of monetary and fiscal stimulation, which created a speculative frenzy,” he said. “It created its own sort of unhealthy environment, and bred a kind of speculative mentality, which had to be cleansed.”
He added that the rapid rise in interest rates brings people back to traditional reality. “A lot of people still think they’re in la-la land.. so it is a period of, I think, adjustment, and people have to be aware there’s a new reality.”
TRENDING NOW

Singapore expects all parties to honour commitments, says PM Wong after Indonesia cuts gas exports

Gas Supply may pursue remedies if contract breached following Indonesia’s export cuts: Tan See Leng
SoftBank’s Son plans US$50 billion Malaysia tech outlay: Anwar Ibrahim

Is Manila Asia’s new dining hot spot?

