

Property outlook 2025: Are home prices stabilising?
A cautious approach is advisable for prospective buyers, particularly considering current elevated price levels and interest rates
THE Singapore property market begins 2025 with renewed confidence, following a period of reduced transaction volume. While prices continue their upward trend, affordability is nearing its peak, which requires commensurate growth in household incomes to sustain this momentum.
Given the government’s ongoing cooling measures, the DBS Research team anticipates a moderation in property price growth in 2025. The projection for the Singapore property price index (PPI) is a 1 to 2 per cent increase, aligning with inflation expectations and representing a significant decrease from the 6.8 and 3.9 per cent increases observed in 2023 and 2024, respectively.
Stabilising home prices
Singapore’s positive economic outlook and low unemployment rate underpin the property market’s fundamentals, although potential escalation of global trade tensions poses a downside risk. Buyer sentiment is heavily influenced by economic conditions and employment levels. Our DBS economist forecasts robust GDP growth of 2.8 per cent year-on-year for Singapore in 2025, exceeding the midpoint of the Ministry of Trade and Industry’s forecast range of 1 to 3 per cent.
Following interest rate cuts by the Federal Reserve between September and December 2024, the more favourable interest rate environment leading to lower mortgage rates will likely support buyers’ sentiment. With current rates around the 2.5 to 2.6 per cent range (down from around 4 per cent a year ago), homebuyers can enjoy substantial savings of close to S$800 per month on a S$1 million loan.
While sentiment is positive on the demand side, supply side factors such as stable land prices and high construction costs indicate that new home prices will likely remain firm. Developer participation in land tenders has been significantly lower in the past two years (averaging two to three bidders compared to a historical average of 10), suggesting caution in the market. Given that overall tender prices have remained relatively stable, along with persistently high construction costs, we foresee limited potential for a decrease in new home launch prices.
For the HDB resale market, the DBS Research team anticipates prices will be supported by: (i) permanent residents (PRs) and (ii) former private homeowners who have completed the 15-month wait-out period after selling their private homes. These buyers, potentially with substantial gains from the sale of their private property, could provide more momentum for HDB prices to rise in 2025.
New households and upgraders drive demand for private property
New household formation is a key driver of property demand in Singapore. Based on SingStat data, an average of 20,000 new households have been formed annually over the past five years. While the government has increased the supply of HDB flats, a segment of the population may still require private or resale public housing due to factors such as exceeding income eligibility limits for Build-to-Order (BTO) flats (S$14,000 household income ceiling), location preferences or desired purchase timelines.
Using marriage rates as a proxy for future household formation (averaging 27,000 annually over the past five years), we project sustained housing demand. While the number of marriages exceeds the number of newly formed households – due to perhaps young couples residing with parents, for instance – the strong desire for homeownership in Singapore suggests that demand for private homes will remain robust in 2025.
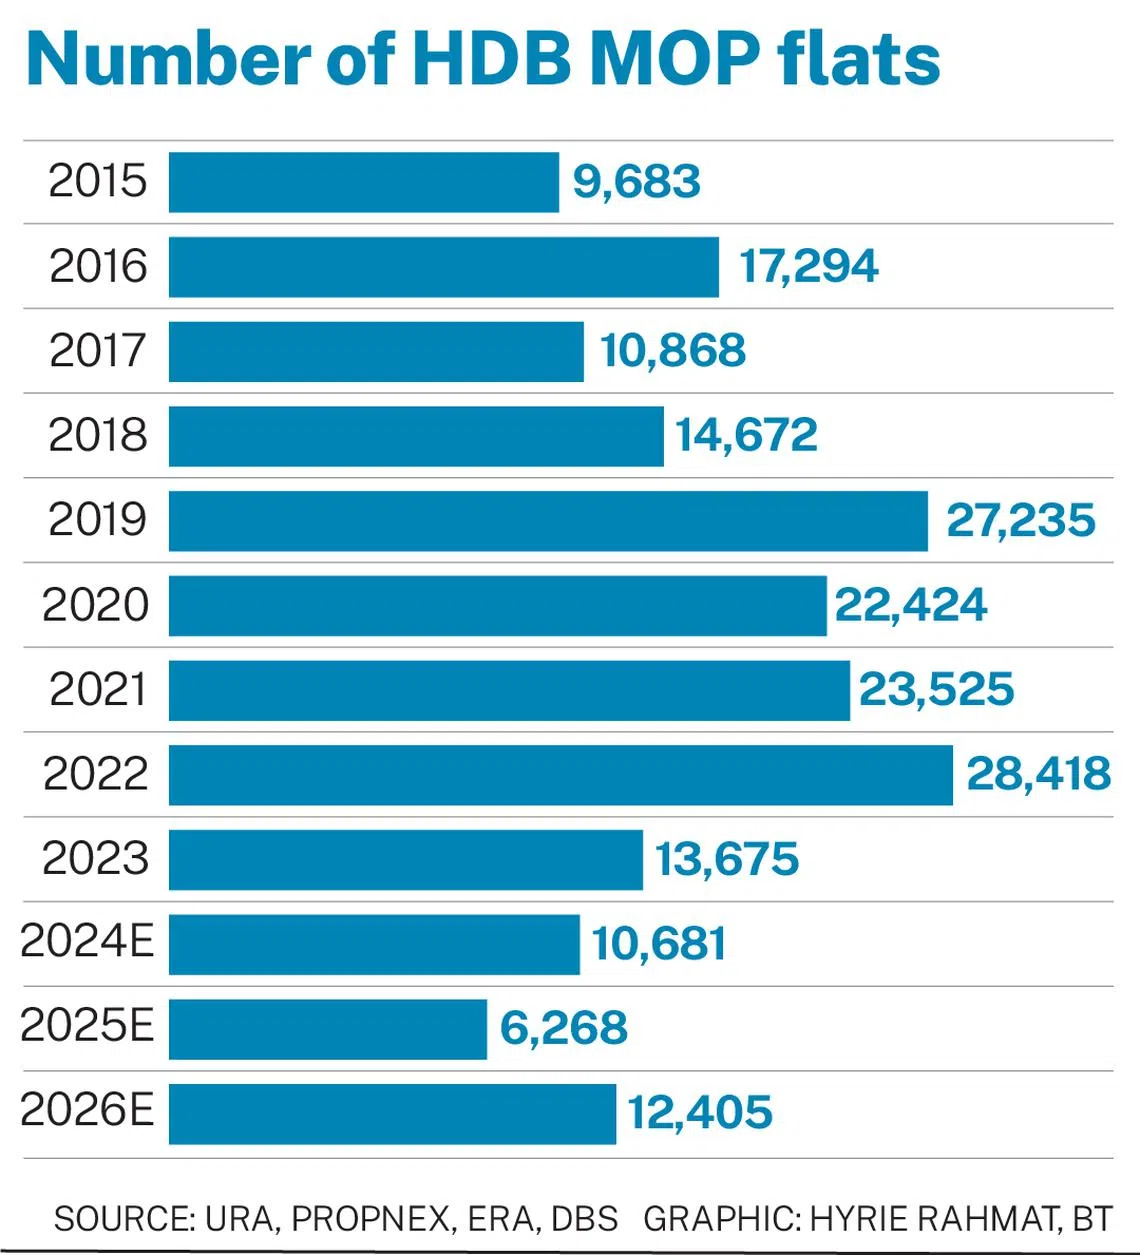
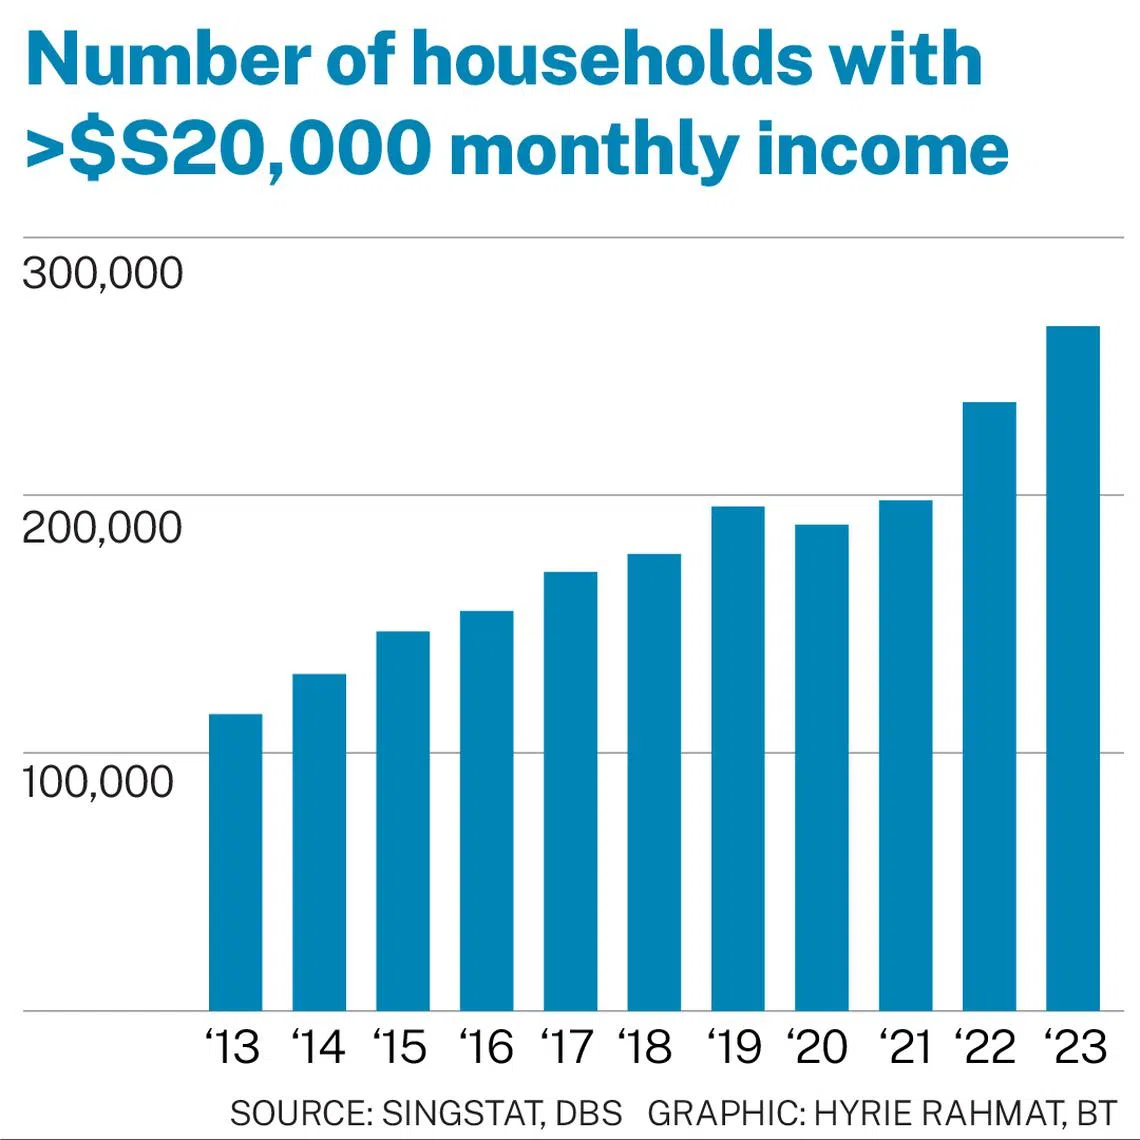
Upgraders represent a significant segment of the private home market. They typically leverage the proceeds from selling their HDB flats and accumulated savings for downpayments. A large pool of potential upgraders is expected, with more than 100,000 HDB flats reaching their Minimum Occupation Period (MOP) between 2019 and 2023. Furthermore, rising household incomes, with a growing number exceeding S$20,000 a month, suggest an increased capacity to afford private properties, supporting continued demand.
Are homes still affordable?
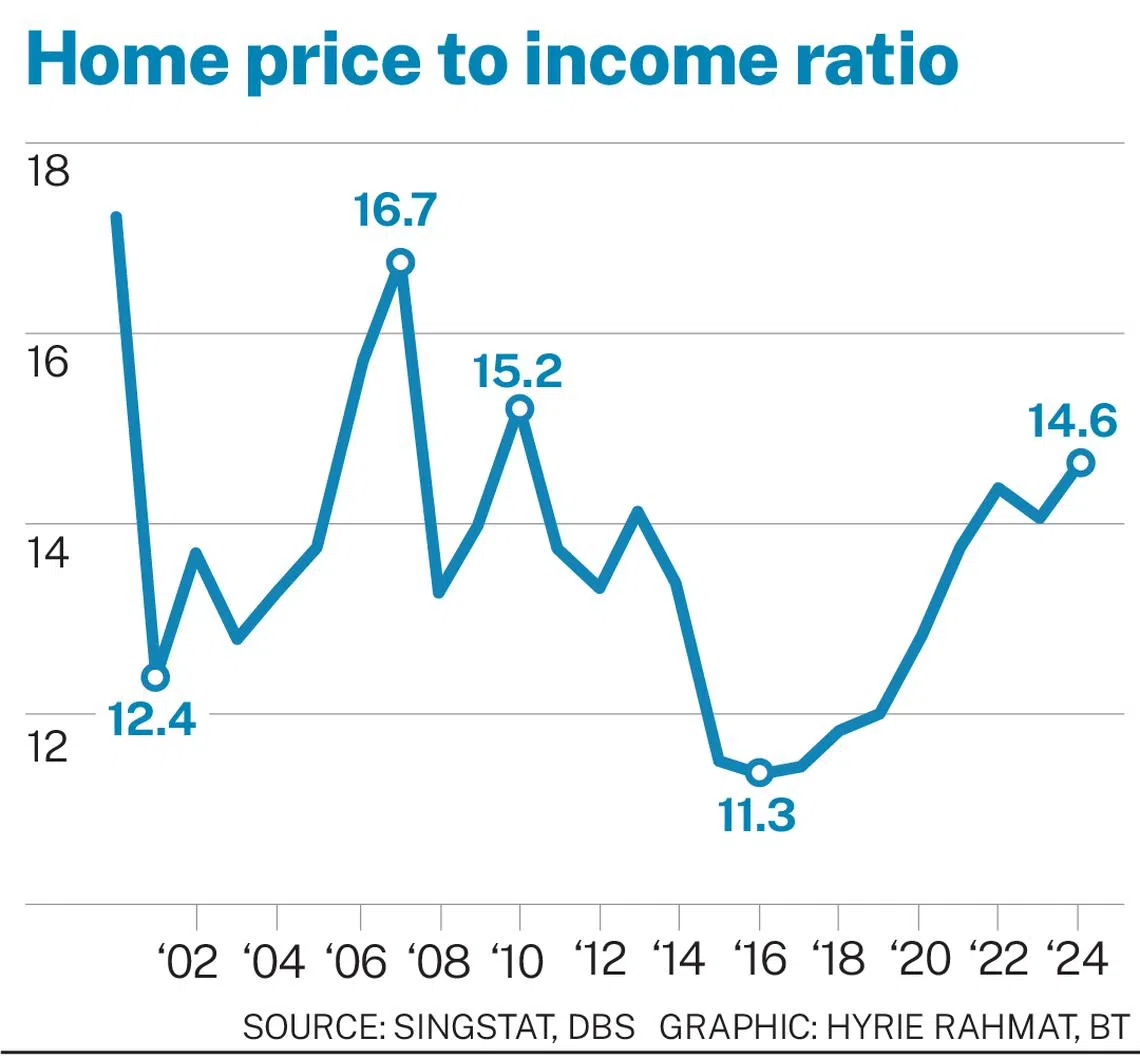
Analysis of the price-to-income ratio for Singaporean homes suggests that affordability is nearing the upper end of historical ranges. Comparing median home prices to annual household income growth since 2000 reveals that while incomes generally kept pace with home prices, recent price growth has outstripped income growth.
The average price-to-income ratio was 13.4 times between 2000 and 2023. However, this has increased to 14.1 times in 2023 and was approaching 14.6 times in 2024, reaching the upper bound of historical affordability levels. This implies that, for price increases to be sustainable, it requires faster income growth, larger downpayments from buyers, or a shift towards smaller, lower-priced homes.
With lending limits (such as Total Debt Servicing Ratio) in place and rising private property prices, a homebuyer’s purchasing power is increasingly determined by their borrowing capacity, as based on household income. Consequently, the total property price is now a more crucial factor than price per square foot (psf).
For example, an older 1,200 sq ft, three-bedroom condominium priced at S$2,200 psf totals over S$2.6 million. A newer, 900 sq ft, three-bedroom unit priced at S$2,600 psf costs less than S$2.3 million.
This illustrates that, given a fixed borrowing limit, buyers would need to pay an additional S$300,000 for the older, more expensive unit despite its lower psf price.
New launch transaction volumes expected to rise in 2025
The DBS Research team projects a year-on-year increase in new home sales volume this year, driven by a strong pipeline of upcoming launches and attractive buyer interest. Prime Government Land Sales (GLS) sites in desirable locations (Orchard Boulevard, Zion Road, Holland Drive, and River Valley Green) are expected to attract significant attention, particularly if competitively priced.
The anticipated launch of three executive condominiums (ECs) in 2025 – Aurelle of Tampines (Q1 2025), Plantation Close (Q2 2025) and Jalan Loyang Besar (Q4 2025) – typically experiencing strong sales due to affordability, will further contribute to this growth. Overall, declining interest rates are expected to support robust transaction volumes in the new launch market in 2025.
Financing a private home purchase
The Singapore property market is anticipated to maintain price stability in 2025, driven by sustained demand. Given the significant financial commitment involved in property purchases, a cautious approach is advisable for prospective buyers, particularly considering current elevated price levels and interest rates. Careful budgeting and comprehensive savings strategies are crucial to ensure long-term financial health and responsible homeownership.
Let’s consider the example of a new Rest of Central Region (RCR) condominium that cost S$2.4 million and assuming the case of a 35-year old Singaporean couple with a household monthly income of $18,000; here are the financing details (using DBS MyHome Planner).
Using the loan-to-value limit of 75 per cent, they will be able to take a maximum loan of S$1.8 million. The downpayment will be S$600,000, with a minimum of S120,000 paid in cash. Assuming a 30 per cent household savings rate, it will take the couple close to two years to save for the downpayment. The monthly repayment for a 30-year loan tenure is estimated to be S$7,589, based on a 3 per cent per annum interest rate.
Hence, careful planning is essential, particularly given today’s higher prices and interest rates. A well-defined budget and savings plan will greatly benefit homebuyers and ensure a smoother, more successful home financing experience. Furthermore, continue to track the mortgage rates over the years and explore re-financing and switching of loan packages, when it makes sense.
For those who are asset-rich and cash-poor, a home is a valuable asset that can be monetised through various options to close money gaps, if and when the need arises.
Buying a home is a significant investment and affordability is key.
Lorna Tan is head of financial planning literacy at DBS Bank, and author of bestsellers ‘Money Smart’ and ‘Retire Smart’. Lynette Tan is a financial literacy specialist at the bank.
TRENDING NOW

Why US$100 oil, 5% US yields affect Singdollar, ringgit differently vs other Asean currencies
Singapore fintechs struggle to find finance and tech talent

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing

Why Tan Aik Keong of digital solutions specialist Agmo wants to make himself less indispensable

