

Room to boom or boom to bust?
While global economies appear to be on the upswing as we enter 2014, investors must now contend with new challenges
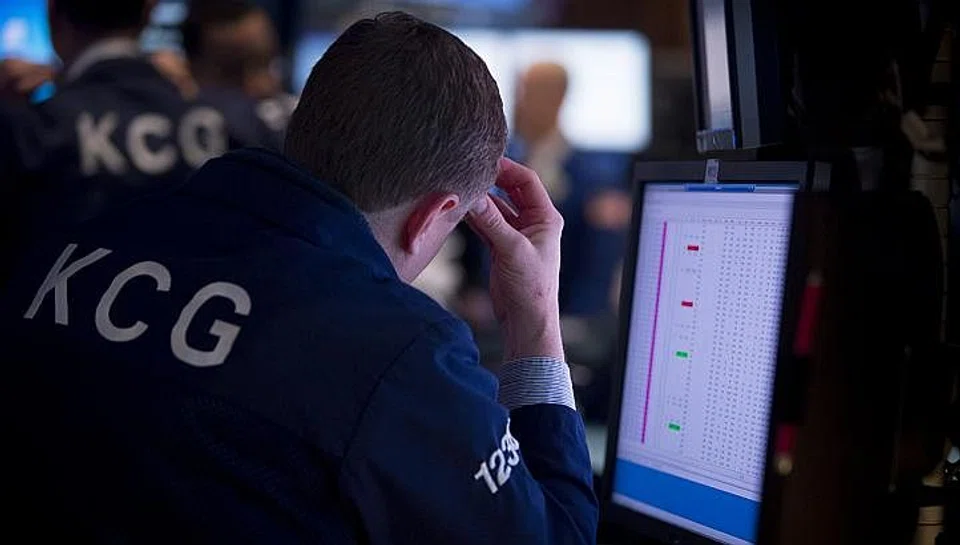
A YEAR and a half ago - despite nearly four years of unprecedented global monetary stimulus - investors were still uncertain as to whether the global macro environment was in fact improving, whether the great monetary experiment following the 2008 crisis was working or whether deflation would take hold on a global basis.
It is easy to forget, in light of recent events, that equity markets in the summer of 2012 turned sharply lower, led by the eurozone, China and Japan, all revisiting levels close to their 2009 troughs. Long-duration US bond yields were hitting their all-time lows, two-year paper traded at 20 basis points and peripheral European government bond yields, which had dropped sharply in early 2012, spiked for a second time to 25-per-cent-plus levels.
I am sure many investors entered 2012 thinking that after three years of massive monetary stimulus, fiscal austerity, bank restructuring, regulatory reforms and cheap equity markets, 2012 would mark the key "turnaround" year for asset appreciation and economic recovery. Six months into the year, those same concerns that plagued investors in 2008 and 2009 were back with a vengeance.
What a difference 18 months makes. As investors enter 2014, there is a sense that the 2008 crisis and the risks associated with a deflation spiral have finally begun to fade; while central banks continue to have their "stimulus" feet pressed firmly on the gas pedal - leaving few options open should another event rattle markets - global economies appear to be on the upswing, interest rate sensitivity to macro data is returning and even the Federal Reserve, which took the initial steps to zero interest rates and quantitative easing five years ago, announced their move to reduce bond-buying programmes.
Investors must now contend with new challenges. After five years of concern that central banks would remove stimulus prematurely, are we now at the point of worrying that they will react too slowly to recovering economic conditions? Coordinated easing seemed to work to shore up asset valuations, but will region-specific monetary policies - some tightening, some remaining easy - create greater volatility in coming quarters?
As global economies gradually heal and unemployment rates tick through central banks' stated thresholds, how will equity and fixed-income markets react to rate-hike expectations being pulled forward?
With global equity markets rallying, the US now trades at nearly 16 times normalised 12-month forward earnings, the top end of a 30-year range excluding the 2000 technology bubble.
Multiple expansion has been the primary driver of the US' strong returns and our own analysis shows that during transitions from easing to tightening monetary policy, multiples begin to contract and earnings estimates typically begin to climb (See chart above).
An issue for US equities, then, may be the strength with which earnings forecasts can rise, considering that profit margins are already at historically high levels and companies have been reluctant to invest profits back into their businesses and develop future revenue-generating sources.
A region with more attractive valuations and greater visibility for an accelerating earnings-recovery cycle may be the eurozone, the developed market's deep-value market.
While valuations have climbed a bit and now stand at 13.5 times forward earnings, the inflection point from recession to growth, albeit disappointing growth, should be enough to attract investors to depressed balance sheets with cyclical recovery potential.
As consumption improves, a similar multiple expansion cycle as experienced in the US could take hold in Europe. Our portfolios are positioned in diversified European sectors and thematic baskets to take advantage of these opportunities.
In emerging markets, for so long a single bet across Asia, Latin America and Eastern Europe, extremely diverse conditions persist - from the central bank aggressively tightening policy in Brazil to recalcitrant policy-makers in India reluctant to take action.
China continues to seek ways to deal with their highly leveraged balance sheet, but it appears to us that even a gradual adjustment over time will depress macro growth further. We continue to maintain a significant underweight to China-related investments globally and a minor negative bias to the remainder of emerging markets, primarily through currency shorts relative to the US dollar and the euro.
This 2013 to 2014 period may in fact mark the start of the long-awaited transition from investors focused on the repercussions and risks associated with the 2008 crisis to a less risk-averse, more forward-looking view towards global recovery and risky assets.
We believe that the past cycle's preferred strategic allocation to bonds and cash, and tactical trading approach to global equities (remember "buy-and-hold" is over?), may in fact reverse.
While equity returns are not likely to match their average annualised return over the last five years (MSCI All-Country World Index +15.6 per cent, Standard and Poor's 500 Index +17.9 per cent per annum from Dec 31, 2008, to Dec 31, 2013), our five-year expected return forecasts indicate that they should on average beat bonds, which should exhibit above-average volatility as investors are forced to deal with global monetary-policy uncertainty.
Additionally, while developed-market equities have rewarded investors handsomely over the last five years, especially more recently, the emerging markets, after a very difficult readjustment to substantially lower growth expectations, could provide the value opportunities in portfolios over the next five years.
The key differences ahead, in our view, include substantially lower-return expectations compared to the 1995-to-2007 period, and distinct country-by-country results, with winners and losers.
In our view, investors will likely only profit by selectively investing in a few countries' equity, bond and currency markets going forward.
Overall, our long-term expected returns for global equities are below historic rates of return and most consensus market views, but we believe that equities will beat global fixed income returns handily over the next five years, and on a regional basis, provide sufficient returns to beat inflation as well.
The writer is a senior portfolio manager on the Global Multi-Asset team with Morgan Stanley Investment Management
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
China’s Pinglu Canal likely to benefit Singapore, other South-east Asia ports in the long term
Suntec Reit to increase Singapore focus, sell three Australia properties

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing

