

Seeking clarity in rules for retail ESG funds
In a welcome move, MAS guidelines for the labelling of such funds go further than EU rules, by specifying an ESG investment threshold
Genevieve Cua
THE rules around the labelling of funds as ESG (environment, social and governance) and/or sustainable are only recently gaining clarity. In Europe in particular, they are causing a shake-out among asset managers, who are braced for the possibility that some or many of their funds may need to be downgraded.
Regulators in Asia – including Singapore, Hong Kong and Japan – have begun to tighten ESG funds’ disclosure requirements. The Monetary Authority of Singapore’s (MAS) disclosure guidelines for retail ESG funds were issued in July and will take effect in January 2023.
In Japan, no new fund has claimed the ESG label in the past five months since the Financial Services Agency signalled new regulations on ESG-labelled funds, according to Bloomberg reports.
Although Europe took the lead in 2021 with the SFDR (Sustainable Finance Disclosure Regulation), asset managers continue to face challenges in complying with the rulebook, which is still being finetuned.
Fund managers run the risk of taking a blow to their reputations should they be forced to relabel or downgrade their ESG funds. They also need to strike a balance in a landscape where fund regulations around ESG are fluid and uneven, raising the knotty question of whether their funds can be marketed across borders. For investors, there is the risk that funds in which they invested – believing these were sustainable – may be deemed to fall short.
Interestingly, MAS’ guidelines go a step further than the EU’s SFDR, in specifying a threshold for funds to merit the ESG label. An ESG/sustainable fund’s strategy and portfolio must reflect an ESG focus in a “substantial’’ manner, with at least two-thirds of the fund’s net asset value being invested according to its ESG strategy.
In addition, a fund that only uses negative screening or “merely incorporates or integrates ESG considerations into its investment process to seek financial returns’’ cannot use the ESG/sustainable label.
By specifying this two-thirds threshold, MAS has arguably increased clarity. This is in contrast to the SFDR framework, where fund managers remain uncertain whether an ESG investment threshold will be specified for Article 9 or “dark green’’ funds.
Based on Morningstar’s database, there are just over 75 funds in the ESG/sustainable category registered for retail distribution in Singapore. Based on SFDR labelling rules, more than 45 are currently Article 8 or ‘light green’ funds. Just under 20 are Article 9 or ‘dark green’ funds. Morningstar’s classification is based on intentionality and not fund holdings, and does not take into account MAS’ guidelines.
Understanding the landscape and definitions of retail ESG funds may help you to raise questions with your fund managers or advisers, particularly if you have already invested in such funds and need more clarity.
Broad agreement on the ESG continuum
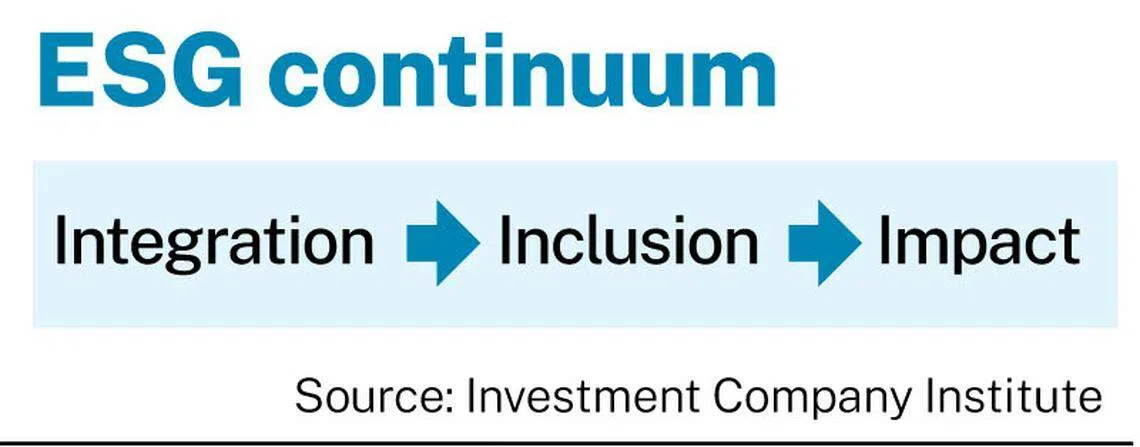
There is today some broad agreement on the spectrum of ESG strategies, indicating a portfolio’s degree of ESG adoption. Perhaps the clearest is in a paper by the Investment Company Institute, which describes a continuum that runs from ESG integration, to ESG inclusionary investing, to impact investing.
Similarly, the US Securities and Exchange Commission posits three broad types of strategies:
- Integration funds which integrate ESG alongside non-ESG factors in investment decisions.
- ESG-focused funds where ESG factors are a “significant or main consideration’’.
- Impact funds that seek a particular ESG impact.
The basic thing to note is that ESG-integrated funds are seen as having the lightest degree of ESG consideration. In this segment, ESG factors are among many others, and may not drive investment decisions. This segment also covers a wide range of strategies, including exclusionary screening.
The second category is inclusionary, with the positive intent and action to screen and pick securities for ESG characteristics.
Impact, of course, is at the extreme end. This strategy compels funds to spell out explicit ESG targets and commit to measuring impact.
Striking a balance between frameworks
SFDR rules are important for funds marketed in Singapore as most funds here are domiciled in Dublin or Luxembourg. SFDR spells out three types of ESG-related strategies:
- Article 6 funds merely integrate ESG considerations.
- Article 8 funds “promote’’ ESG characteristics.
- Article 9 funds set measurable ESG objectives.
SFDR Level II, an “upgraded’’ disclosure framework, is expected to take effect in January 2023. But it is currently unclear whether a minimum threshold for sustainable assets will be set for Article 9 funds.
For ESG funds marketed in Singapore, those already classified as Article 8 and 9 funds under SFDR rules may still fail to qualify for the MAS’ ESG label. Gabriel Wilson-Otto, Fidelity International’s head of sustainable investment strategy, says that even for Article 8 and 9 funds that are deemed to have complied, a sticking point may be MAS’ requirement for two-thirds of fund assets to be managed according to an ESG strategy.
“This implies that it is possible for an Article 8 fund under SFDR to not meet the MAS requirement’’, due to the prescribed threshold, he said. But Fidelity International says its funds with the “sustainable’’ name will meet the MAS criteria, and ESG funds marketed in Singapore already qualify. Based on Morningstar compilation, Fidelity has 11 sustainable funds for Singapore distribution, the largest among fund managers.
Another asset manager, who declines to be named, says: “We recognise the regulatory fragmentation in ESG labelling which remains at risk, with impacts on product scalability, potential reputational risks and greenwashing concerns for the fund managers. We believe coordinated, high-quality disclosure frameworks will benefit investors, and support a harmonised approach among the regulators. We also encourage (regulators) to allow flexibility as the market continues to evolve and to engage with the industry early and extensively before issuing any new requirement.’’
At end-September, according to Morningstar’s Hortense Bioy, 33.6 per cent of EU funds are Article 8 funds and 4.3 per cent are Article 9 funds. “Asset managers continued to upgrade funds by enhancing ESG integration processes, adding binding ESG criteria (including carbon reduction objectives), or in some cases completely changing the mandate of the strategy,’’ she wrote in an article.
For Article 9 funds, the SFDR sets minimum high-level requirements: They should invest in companies with economic activities that contribute to an environmental or social objective; comply with the ‘Do No Significant Harm’ principle; and follow good governance practices. However, the dust has far from settled on SFDR. Eurosif, an European industry group representing some US$20 trillion in assets, has issued a report calling for clarity and suggesting ways to make SFDR “fit for purpose’’. Eurosif contends that the SFDR was meant to serve as a disclosure framework, but in the absence of a common taxonomy, the industry has seized on it as a fund classification system.
Limited supply and higher fees
Growing demand for sustainable investments makes it even more imperative to have clear regulations around labelling. In a report, PwC forecasts that ESG-related institutional assets under management (AUM) will grow from US$18.4 trillion in 2021 to US$33.9 trillion by 2026, an annual compound growth rate of nearly 13 per cent.
In its survey, asset managers and institutional investors cite complex and inconsistent regulation as a hurdle, as well as the need for trusted and transparent ESG data. Globally, 57 per cent of asset managers are looking into charging ESG-based performance fees, with more than half indicating a range of 3 to 5 per cent. Asset managers believe higher fees are needed to pay for higher ESG compliance costs, which have risen by 10 to 20 per cent.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Fed hike throws Singapore banks a margin lifeline; UOB likely to benefit more

Luxury properties seized in S$3 billion money laundering case fail to sell at auction
US stocks: Tech leads Wall Street to higher close as oil eases, Treasury yields dip

