Silver lining for savers and retirees as rates rise: More 3-in-1 options
Higher interest rates and inflation are challenging, but more options are emerging for the risk averse
Genevieve Cua
VOLATILITY in stocks and bonds is set to continue as higher interest rates and inflation pose valuation challenges. But there is a silver lining for savers and retirees who aim for the 3-in-1 benefits of capital preservation, income and liquidity - all in a single asset.
The robust response for the most recent Singapore Savings Bond (SSB) issue reflects the keen appetite for 3-in-1 benefits. The Aug 1 issuance received applications worth a whopping S$2.4 billion, the highest since SSB issuance began in 2015. The 10-year average return rate of 3 per cent was also the highest on record.
Meanwhile, fixed deposit rates are also crossing the 2 per cent threshold, albeit on a promotional basis.
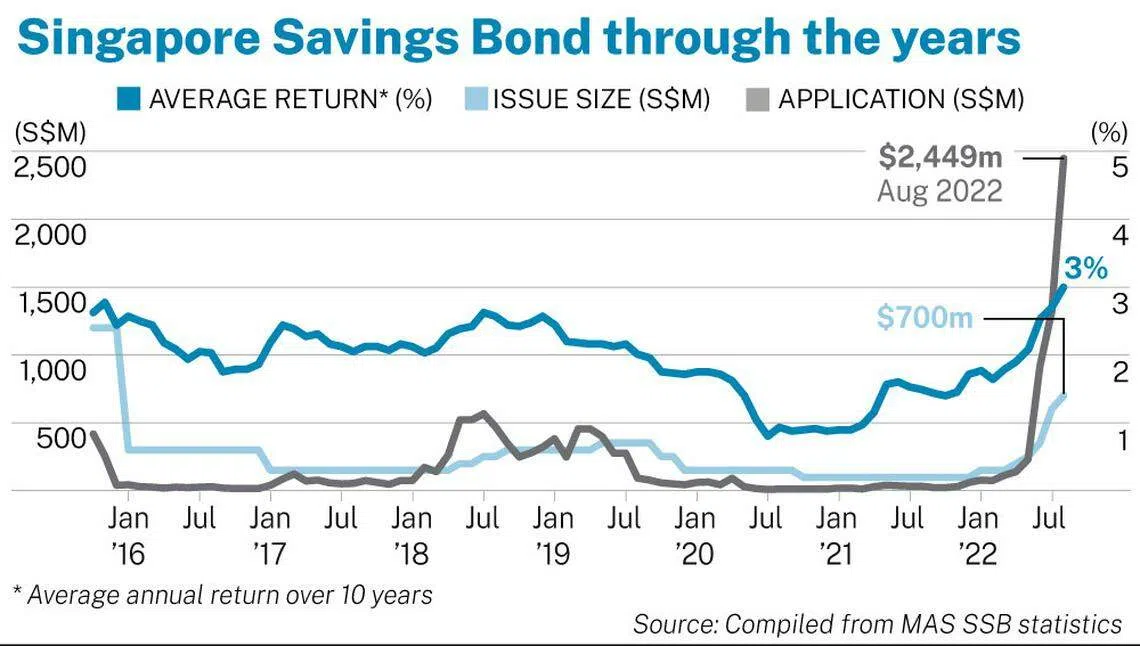
The good news is that as rates trend higher, more attractive options will emerge for risk-averse individuals and retirees. But they face some challenges.
First, they need to be vigilant on what is available and make their applications before any deadline. Second, they are unlikely to get all the allotment they want because of strong demand. Three, because returns from lower-risk options are unlikely to keep pace with inflation, savers will need to take some risk in their portfolios.
Still, it’s possible to build a portfolio over time to enable you to “ladder’’ your exposures. Laddering is a strategy to purchase instruments like bonds over time, with varying maturities and periodic coupon payments which may coincide with when you need the income and principal. The relatively low quantity ceiling for SSBs, for instance, suggests that you can build a portfolio over time by applying when you find the SSB rate attractive.
If you want direct bond investments, remember to pick bonds of good credit standing given the economic uncertainties, and shorter durations to mitigate their interest rate sensitivity. Make sure to diversify, since direct bond investments typically call for a larger ticket size of at least S$200,000 and you do not want to be too concentrated in single-name credits. This piece does not look into direct bond investments.
Here are some options that I have found attractive. I have invested in some of them, as detailed below.
Top up your Retirement Account/CPF Life
This option is a must, even if your retirement is not imminent. The RA interest rate is the highest within the CPF at up to 6 per cent for those age 55 and older. You can choose to top up the premium payment for your CPF Life according to your desired retirement income. The younger you are, the lower the premium is likely to be. You could also choose to receive the income later – up to age 70.
CPF Life pays an income for life, and is the most attractive annuity around as there are no commissions or management fees. There are 3 plans, including an “escalating’’ plan where monthly payouts rise every year.
There is a chance that the interest rate of market instruments like the SSB could creep up and become competitive with the CPF rates. But there is no volatility nor risk to your savings. CPF Life’s annuity income is based on an actuarial calculation, taking into account your age, gender, CPF rates and mortality rates. I believe it’s a must-have building block for retirement income planning. Topping up my CPF Life, which entailed an application to the CPF to raise my premium, gives me peace of mind.
Singapore Savings Bond
I have long considered the SSB but made my first application in the most recent issue (closed Jul 26) which pays an average 3 per cent over 10 years. Not surprisingly, response to the issuance was robust and a record. I received the quantity ceiling of S$9,000, a fraction of what I applied for, and was not lucky enough to get an extra S$500 allocation. Still, I’m grateful - the process was easy and now that interest rates are trending up, I’ll be watching future issuances.
There are some things to note about SSBs. While your principal and interest payouts are secure, it isn’t cash on tap. You can redeem the bond in multiples of S$500, and withdrawals take around a month. But there is no withdrawal penalty and you still earn the accrued interest rate.
Cash-plus alternatives/Fixed deposits
Fixed deposit rates vary widely and are adjusted fairly frequently. Rates have trended upwards, and this is a boon for the risk averse. In fact, fixed deposit rates today give cash management funds - positioned as deposit alternatives - a run for the money.
Among deposits, depending on the bank and the tenure, you can get over 2 per cent per annum. RHB’s promotional rate, for instance, is 2.25 per cent for a 24-month tenure and a minimum deposit of S$20,000. Bank of China also pays 2.25 per cent for the same tenure, but requires a minimum deposit of just S$5,000.
CIMB’s online promotional rate up to Jul 31 was 2.05 and 2.25 per cent for 12- and 18-month tenures, respectively, for a minimum amount of $10,000. While fixed deposits are very liquid, you may not get the full interest should you break the deposit prematurely.
Robo advisers here also offer cash-management accounts, which are invested in lower-risk unit trusts such as money-market and short-duration bond funds with an overall return target higher than cash. These are not exactly comparable to cash or fixed deposits, because depending on the underlying exposures, there may be interest rate sensitivity and even some credit risk.
Stashaway, for example, states that the historical maximum drawdown of its Simple Plus portfolio is minus 2.32 per cent as at end-June.
Endowus offers 3 choices of “Cash Smart’’ portfolios – Secure, Enhanced and Ultra where the return and risk profiles dial up incrementally. The Secure portfolio, for example, has an indicative annual return of 1.5 to 1.6 per cent, and Ultra 2.6 to 3 per cent.
Endowus chief investment officer Samuel Rhee says: “Each client requires a different way to manage their cash. Investors should set their expectations based on their personal circumstances, risk appetite and goals in setting aside these cash pots.’’
The Enhanced and Ultra portfolios suffered losses in the first quarter, but the losses were muted compared to other fixed income assets. Returns improved in the second quarter.
Rhee says: “The short-term environment may be one where we see inflation peaking in the coming months and interest rates also peaking, which means that the mark-to-market price impact on bonds and fixed income markets may start to ease and reverse. “
He adds: “In recent months, we’ve seen a rebound in fixed income market performance. This is likely to filter down to the cash alternatives which have bonds and credit in their portfolios. We have had periods where the cash alternatives with bonds outperformed tremendously, like in 2020 and 2021, and so we should be careful not to be too bearish at the bottom of the cycle.’’
Astrea 7 PE bonds
Astrea 7 closed in May but its manager, Azalea Asset Management, has a programme of regular issuance. I have written about Azalea’s efforts to widen access to private equity since its first PE bond offering for retail investors in 2018. But it is only this year that I applied for Astrea 7’s retail tranche A-1 bonds, which pay a fixed coupon of 4.125 per cent pa.
While the underlying assets – a portfolio of PE funds – entail market risks, the structure of the bond itself incorporates safeguards, particularly for retail investors. The safeguards include over-collateralisation and a cash-flow “waterfall’’ where distributions are paid to the most senior (or retail) tranche first before it flows down to other tranches.
The coupon rate seemed fair to me, given where cash rates were, even with interest rates already on an uptrend. In addition, the bond price has remained resilient.
In response to questions, Azalea said the PE market has not been spared the market downdraft. Deal activity softened in Q2, and distributions and contributions were more muted compared to 2021. Broad PE fund valuations in Q1 also declined.
“In terms of potential impact on Astrea, each transaction is robustly structured to withstand downside scenarios as indicated in the prospectuses,” Azalea said. The structure, it added, is conservative with a low loan-to-value ratio of less than 50 per cent, which provides a strong equity cushion for bondholders.
It said Astrea bonds have also significantly deleveraged as cash reserves increased. Sizeable credit facilities are also in place to pay for expenses and interest in case of shortfalls. To date, these facilities have not been drawn by any Astrea issuances.