Singapore equities gain traction into 2026
Initiatives in 2025 have strengthened market performance
THE Straits Times Index (STI) extended its record-breaking rally into the second half of 2025, lifting its price return for 11 months of the year to 19.4 per cent. This surpasses the 15.4 per cent gain over the same period in 2024, underscoring the market’s resilient fundamentals and the renewed investor interest in Singapore equities.
Stronger listings, rising flows
Equity market initiatives rolled out in 2025 have strengthened Singapore’s market performance and set a constructive tone for 2026. Measures such as the Equity Market Development Programme (EQDP), the enhanced Grant for Equity Market Singapore scheme, the newly announced “Value Unlock” package, and the Singapore Exchange (SGX)-Nasdaq dual-listing bridge are all aimed at boosting the competitiveness of the local equity market.
The impact is evident across multiple fronts. Listing activity on SGX has picked up, with 36 new listings in 2025 – the highest in a decade. A more streamlined listing process, together with the upcoming SGX-Nasdaq dual-listing bridge, is expected to further attract regional growth companies and strengthen SGX’s pipeline of future listings.
Investor participation has also broadened. SGX-listed exchange-traded funds (ETFs) saw strong inflows in 2025, recording S$1.4 billion in net inflows year to date. By end-September, Singapore’s ETF market reached a record S$16.3 billion in assets under management (AUM), a 40 per cent year-on-year increase. Trading activity improved as well, with ETF daily turnover rising 68 per cent on the year in the third quarter of 2025.
Meanwhile, flows into Singapore securities have accelerated, with overall ETF fund flows in 2025 reaching their highest level since 2021, signalling rising investor confidence.
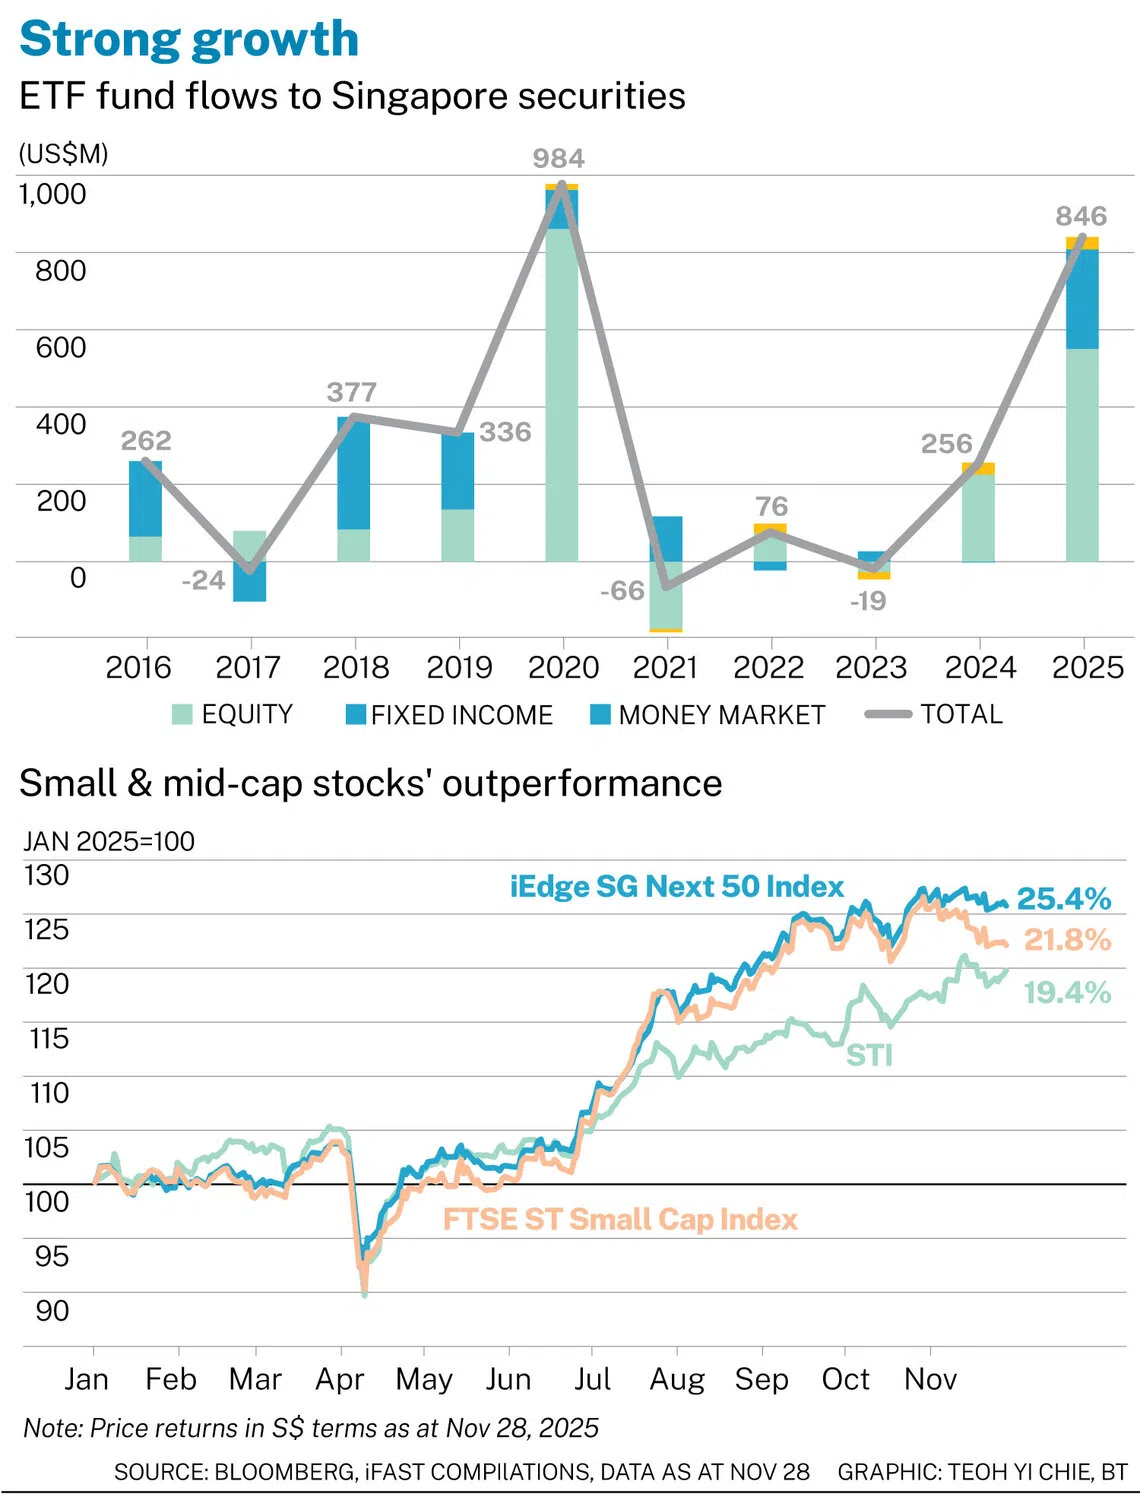
Against this backdrop, small and mid-cap stocks (Smids) have shown more pronounced improvement than large caps, given that many of the recent policy initiatives have a clear emphasis on this segment. Investor appetite strengthened meaningfully in the second half of 2025: Smids recorded S$472 million in net institutional inflows as at Oct 30, 2025. Excluding Singapore-listed real estate investment trusts (S-Reits), institutional net inflows across other Smid sectors climbed to nearly S$890 million – reversing the S$150 million outflow in the first half.
More catalysts are emerging. In addition to several upcoming Singapore-focused funds launched under the EQDP, the introduction of the iEdge Singapore Next 50 Index is expected to spur new ETFs and fund products targeting the small and mid-cap universe.
Performance has been encouraging so far, with both the iEdge Singapore Next 50 Index and the FTSE ST Small Cap Index outperforming the STI since mid-year, highlighting the return potential across the broader market.
Reinforcing market fundamentals
Key market initiatives are not only benefiting small and mid-cap companies, but also supporting the broader market. STI constituents stand to gain from improved liquidity, greater corporate engagement and enhanced investor visibility. Also, an index-wide earnings recovery is anticipated, laying a solid foundation for 2026.
Of the 30 STI companies, 26 are projected to deliver positive earnings per share growth in 2026, marking a broad-based improvement from 2025. This points to a clear upward trajectory in aggregate index earnings and reinforces the fundamental strength underpinning the STI.
The financial sector outlook remains constructive despite net interest margin compression. Singapore banks recorded an 8.7 per cent year-on-year deposit growth in the first eight months of 2025, up from 4.9 per cent in the same period of 2024. Deposit expansion remains a key earnings driver. According to Goldman’s report, every one percentage point increase in deposits could lift operating income by 0.6 to 0.7 per cent when directed into wealth and AUM-related activities. Together with higher fee income, these trends help offset softer net interest income in a lower rate environment and support overall profitability.
S-Reits are also regaining momentum following a strong Q3 2025 showing. Consensus forecasts are for 5.7 per cent earnings growth in 2026 for the iEdge S-Reit Index, after an estimated 19 per cent decline in 2025.
Sector fundamentals remain intact, anchored by high occupancy rates and positive rental reversions, while valuations stay attractive at 0.95 times price-to-book ratio, slightly below the 10-year average of one time.
Expected rate cuts by major central banks are likely to provide further tailwinds by lowering financing costs. S-Reits are well-positioned to attract income-seeking investors rotating from fixed deposits and short-term instruments; the iEdge S-Reit Index offers a dividend yield above 5 per cent.
Seizing opportunities
In conclusion, market-boosting policies are drawing both institutional and retail investors back into Singapore equities, improving sentiment and potentially helping to narrow the longstanding valuation gap between the STI and major regional and global benchmarks.
At the same time, the STI’s dividend yield of around 5 per cent remains compelling, outperforming most global and regional markets and offering an attractive income opportunity in a low-interest-rate environment. We recommend that investors position for the broad-based returns, underpinned by the ongoing policy-driven revitalisation of the equity market.
The writer is a research analyst with the research and portfolio management team of FSMOne Singapore, the B2C division of iFast Financial