

Time to focus on downside risks in markets: MFS chief
Markets have over-returned and there is likely to be a correction, says Ted Maloney
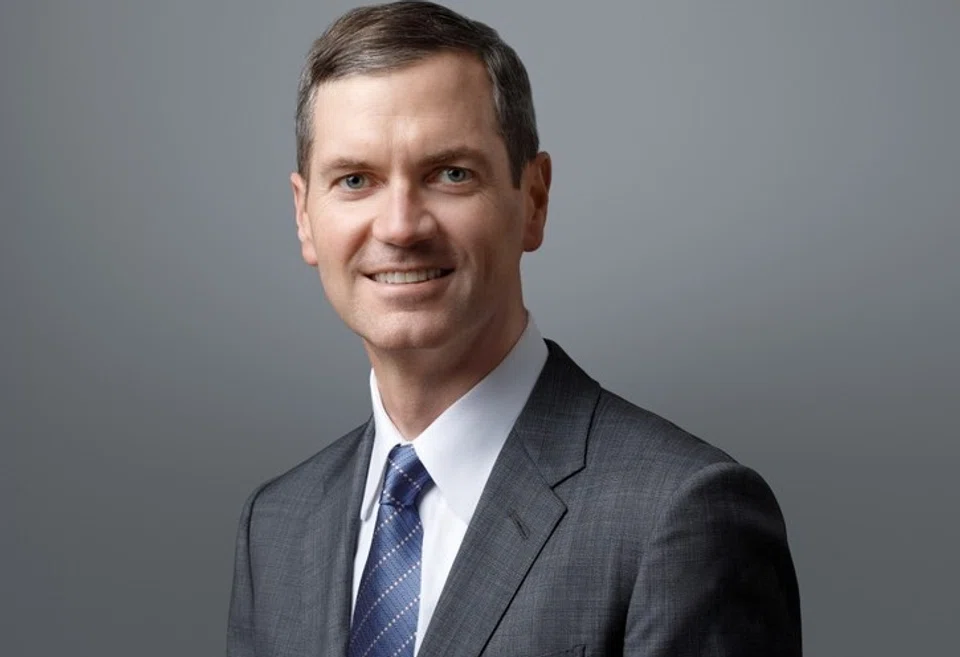
[SINGAPORE] With such robust returns from US equity markets, investors should begin to focus on downside protection, said Ted Maloney, chief executive of MFS Investment Management.
“Equity investors around the world, no matter how they’ve invested – via active, passive or global allocations – have some exposure to US technology and have done extremely well,” he observed.
“We think positioning from now, after such a prolonged and massive period of excess returns, should be to focus on how to protect on the downside. It’s human behaviour and it’s difficult for everyone, including us, to take a step back and think about where the risks may be when everyone is focused on the reward. But that’s exactly what a skilled investor gets paid to do over time.”
Maloney believes that global equity markets are amid a “paradigm shift” regarding expected returns – that is, “markets have over-returned and there is likely to be a correction”. That five to seven companies have dominated returns is “less US exceptionalism and more AI (artificial intelligence) hyper investment”, he noted.
“We’re big believers in the power of AI as an investment tool and economic engine.
“But history suggests it’s not this small number of companies that extracts all the value. History suggests that value gets extracted by the entire economy, which is one of the biggest counterarguments to stagflation – that massive productivity is unleashed that allows you to have growth without inflation.”
As active managers, MFS has sought to mitigate the overconcentration risk that has prevailed with the dominance of the Magnificent Seven stocks. This grouping comprises US tech giants such as Apple, Alphabet and Microsoft.
But this has caused underperformance. For instance, the MFS Growth Fund with US$47 billion in assets has underperformed against the Russell 1000 Growth Index over various periods, including three, five and 10 years.
MFS manages around US$659 billion in assets as at end-September. At end-2024, equities comprised more than 80 per cent. The firm is part of the Sun Life Financial group of companies.
“We manage against a benchmark that includes the Magnificent Seven. We tend to own those stocks in reasonable size, but not all of them, and in a collective underweight. While they have traded with high correlation, they are different companies with different drivers and exposures to the global economy,” said Maloney.
“We’ve underperformed because we’re worried about concentration and it’s only gotten more concentrated. I’m proud of the team. We would have underperformed more than we have, given how dominant the trend has been. But we’ve been able to add value in lots of other places. But being underweight has been a drag on performance.”
The positioning has caused net outflows in some funds, he added.
“We have explained to clients very clearly how we invest, and that we manage risk and pick stocks and bonds on a long-term basis. Clients themselves have built good portfolios that have exposures elsewhere that counteract their exposure to us; we tend to be a bit more conservative in a market like this.
“Certainly, it has been a headwind in our business and, on the margin, we’ve had net outflows in strategies that run against global benchmarks.
“The average investor is overexposed to equities and US tech, and having some diversification at the margins away from US equities and tech and towards fixed income is a good idea. In a 60/40 portfolio (60 per cent equities, 40 per cent bonds), structurally what you would have done is to reduce your equity exposure and increase your bonds. It may not seem the right thing to do on a trailing two-year basis, but over time, you’ll do well.”
Looking ahead
The firm’s latest long-term capital-market expectations forecast a modest appreciation for US large-cap equities of just 1.8 per cent a year compared with 3.3 per cent for global equities over the next 10 years. The expectations for international and emerging-markets equities are substantially higher at 6.6 and 8.4 per cent, respectively.
“This disparity is driven by cheaper valuations and expectations for profit margin expansion outside the US,” said the report. Year to date, the rest of the world has outperformed the S&P 500’s 13 per cent return. The MSCI Asia Pacific Index has returned 22 per cent, the MSCI Emerging Markets Index 27.9 per cent, and the MSCI World index 17.5 per cent.
As many of its peers scramble to get a foothold in private markets, either by partnerships or acquisitions, MFS is steering clear for now.
Maloney said: “It’s not because we don’t think there is a good place for private-market exposure in client portfolios, or that we think it’s a bad asset class.
“But just like (for) our business of public equities and fixed income, the power of scale and brand is extremely important. We have scale and brand in public equity and fixed income, but not in private markets.
“There are players with enormous scale and wonderful brands in private markets. We expect they will take all of the market… It’s the No 1 strategic question that my team and I spend the most time on because it’s a big decision relative to all the trends in the marketplace. If we were to enter, we’d almost certainly do so in partnership with one or more of the great players in that space.”






