The time is right to invest in sustainable Asian cities
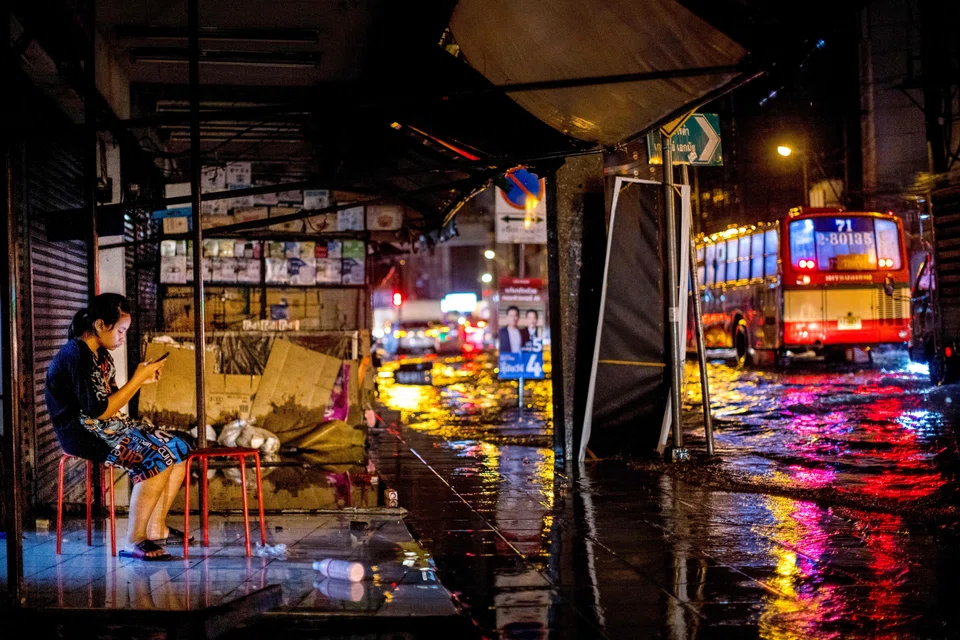
ASIAN cities have experienced rapid urbanisation, driven by the rural-urban migration of people seeking a higher quality of life and better economic opportunities. A report from the United Nations (UN) estimates that an additional 1.2 billion people will live in Asian cities by 2050.
Yet current infrastructure in most Asian cities is insufficient to support the increased needs from this growth. Substandard housing and a lack of access to clean water, modern sanitation and power are problems that persist due to lack of funding and poor governance.
In addition, natural disasters and climate change present unprecedented challenges. According to studies by the Rockefeller Foundation and the UN, a third of the natural disasters of the last 3 decades have occurred in Asia. Asian cities are especially vulnerable to climate change-related flooding and its impact on both the population and economic assets.
To build greater climate resilience and allow Asian cities to flourish, we need sizable investments to create sustainable infrastructure. Based on research conducted by the Asian Infrastructure Investment Bank, investments should go into five areas: enhancing urban mobility, upgrading infrastructure, promoting integrated development, improving health and educational facilities, and investing in innovative technological solutions.
Increasing regulatory support for sustainable change
From a regulatory perspective, sustainability and ESG (environmental, social, and governance) investing are increasingly important to central banks. The establishment of the Network of Central Banks and Supervisors for Greening the Financial System (NGFS) in December 2017 signals more concerted efforts by financial institutions to meet the goals of the Paris Agreement. Asian central banks, including the Monetary Authority of Singapore, have also made sustainable investment a priority in recent years.
Beyond central banks, governments too have begun to strengthen their commitments to addressing climate change and broader sustainability issues. Various Asian countries including China, South Korea, Indonesia, Thailand and India have committed to net zero emissions by the next 30 to 40 years.
With growing awareness of the need for sustainable change, we anticipate a stronger regulatory push for ESG disclosure, more ESG-focused financing, and improving standards in ESG investing in Asian financial markets.
An opportune entry for Asia credit
Bonds are especially appropriate as an asset class to support infrastructure development in Asia, since such projects require multiple rounds of large capital injections over the long term. We view investing in bonds that contribute to or enable the development of Asian sustainable cities as a long term opportunity instead of a passing fad, with a strong growth in the supply of related bonds, and an even stronger demand from investors.
We also observe the opportunity to tap into the early development of a ‘greenium’ in Asia. A greenium is a premium that investors can earn from holding green, social and/or sustainability-linked (GSS) bonds, compared to equivalent conventional bonds.
In more mature GSS bond markets in Europe, there is some evidence of a greenium associated with holding these GSS bonds. In Asia, we believe greenium development is still in the early stage, and being an early adopter of GSS bonds can place investors in a beneficial position to harvest these premiums in the future.
Lastly, the recent selloff in Asia US dollar credit (due in part to headlines concerning the China real estate segment) provides long-term investors with an attractive entry point into the asset class.
Despite recent headwinds, we are optimistic about the longer-term prospects of this asset class. We are of the view that 2022 will be the year of great normalisation of Asia credit spreads. We have also observed policy changes in recent months supportive of the real estate sector in China, and are expecting local governments to tweak property regulations that will promote sales and alleviate stress in the sector
What investments are relevant?
In our view, GSS bonds are a direct way to connect capital to what sustainable Asian cities require. For example, a green bond whose use of proceeds include loans for electric vehicles can enhance low carbon urban mobility in cities.
The market for these bonds has grown over the last 5 years, with total issuance in Asia reaching more than US$60 billion in 2021 alone. We expect this trend to continue over the medium to long term, given increasing demand from investors and greater regulatory support.
Besides those GSS bonds above, relevant investments include conventional bonds from issuers with business activities that are materially aligned with the theme. For example, a conventional bond from a water utility company in Asia which carries out water recycling and treatment activities in a responsible manner – reducing water leaks, improving energy efficiency, protecting health and safety of employees, engaging with local communities – is an investment contributing to improving basic infrastructure in cities, which is well aligned with the theme.
In summary, there is an opportunity to direct capital towards developing sustainable Asian cities. Investors will be able to tap into the emerging greenium of GSS bonds in Asia, which we believe will widen with time as the market grows. Asia bonds also offer a source of idiosyncratic returns that can bring diversification benefits to investors. Finally, we believe that spread widening in Asia credit provides investors with an attractive entry point, especially after a dovish tone from Beijing in recent weeks.
With all these factors lining up in harmony, the time is now, rather than later, for investors to seize the opportunity to invest in the future of sustainable Asian cities.
Jean-Charles Sambor is head of emerging market debt and Xuan Sheng Ou Yong is an ESG and green bond analyst at BNP Paribas Asset Management.