

Trend following amid irrational exuberance
It can help investors to protect their capital during market downturns and ensure that they can also stick to their portfolios through thick and thin
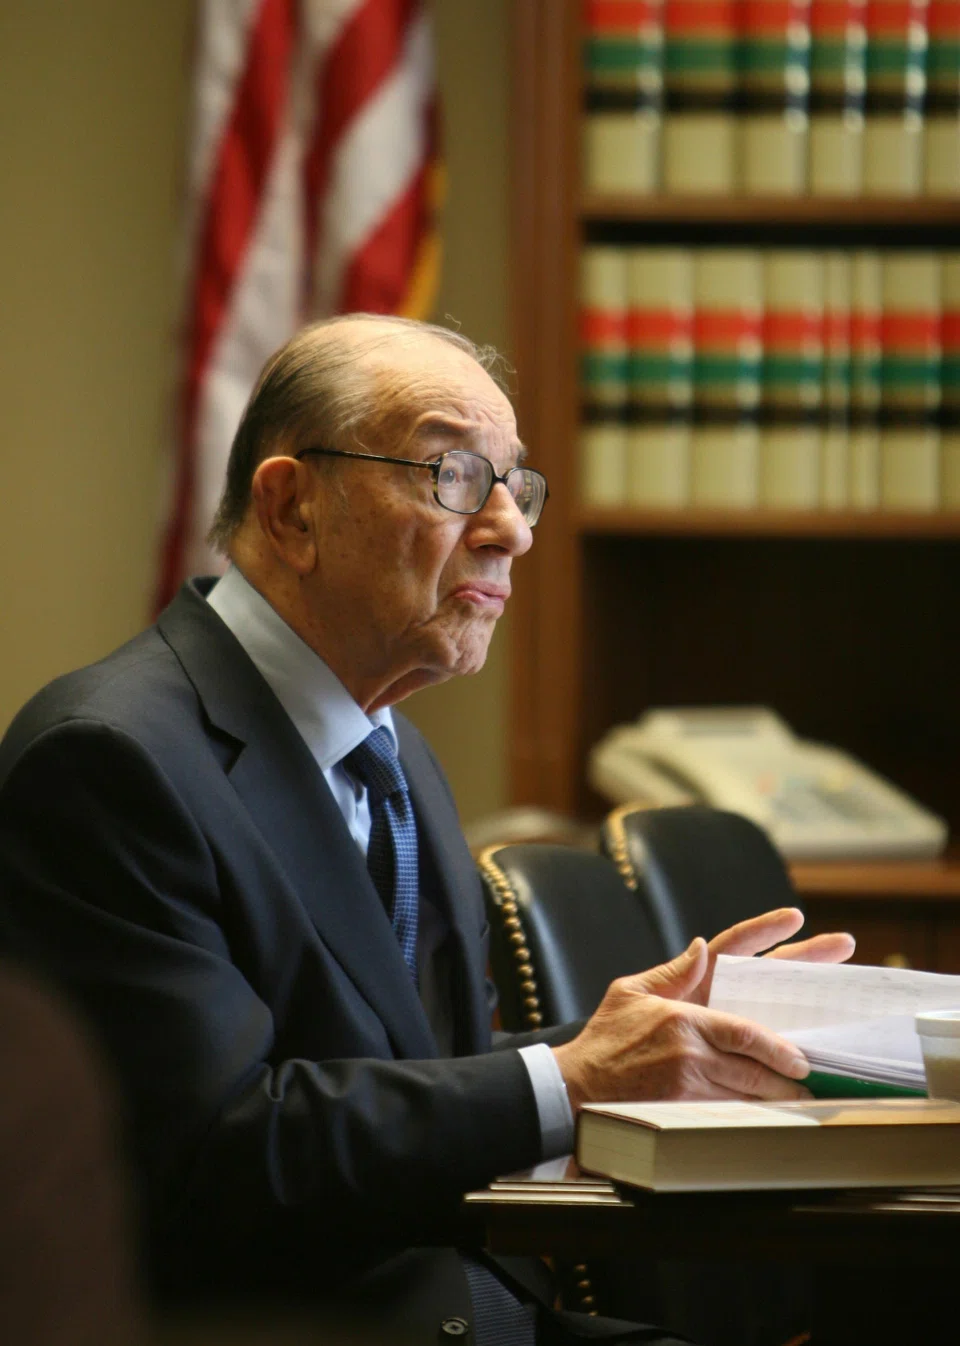
ON DEC 5, 1996, Alan Greenspan, then chairman of the Federal Reserve, first used the phrase “irrational exuberance” in a speech to warn investors that the stock market could be overvalued and about the ensuing consequences.
Greenspan said: “But how do we know when irrational exuberance has unduly escalated asset values, which then become subject to unexpected and prolonged contractions as they have in Japan over the past decade? And how do we factor that assessment into monetary policy?”
Despite his stern warning, the US stock market rallied strongly till early 2000. Investors who sold their stocks due to expensive stock valuation regretted selling too early. Those who shorted the stocks early also fared poorly. In the end, investors who “buy and hold” stocks after the “irrational exuberance” speech made good gains.
Buy-and-hold approach
Since then, leading academics and investors have urged investors to just stick to the buy-and-hold approach and to not try to time the market as it would be a futile venture.
By the way, the cyclically adjusted price-earnings (CAPE) ratio for US stocks was about 28 times in December 1996 when Greenspan issued the warning on stock overvaluation.
The CAPE ratio is the index price divided by the average of 10 years’ earnings adjusted for inflation. The ratio – also known as the Shiller PE ratio – helps to smooth out the earnings and provides a more accurate valuation measure.
Over the long term, the CAPE ratio mostly remains in the range of 10 to 22 times. Since World War II, the CAPE ratio briefly breached the upper range during the period 1964 to 1968 but it did not end well for the markets. It was not until 1995 that we saw the CAPE ratio cross its upper range again. Hence, Greenspan’s warning was not without basis.
Since 1995 until now, the CAPE ratio has mostly been above the upper range. In other words, investors are mostly “irrationally exuberant” during this long period.
What if you use a simple “trend following” approach when investors are mostly irrationally exuberant?
A simple “trend following” approach would see investors buying in an uptrend when the monthly price is more than the 10-month simple moving average (SMA), and sell and move to cash in a downtrend when the monthly price is below the SMA. An investor needs only to check the investment once a month, say, on the last day of the month, if the monthly price is above or below the 10-month SMA and act accordingly.
Here is the backtest result on Vanguard Index Fund (VFINX), from January 1995 to August 2023 (28 years and eight months).
The annualised return of “trend following” not only beat the buy-and hold approach but did so with a much lower drawdown. Its Sharpe ratio, a measure of risk-adjusted return, also beat that of the buy-and-hold approach handsomely.
Importantly, a trend following approach managed to mitigate severe drawdowns during the 2000 bear market and the 2008 bear market. From March 2000 to October 2002, the drawdown for the buy-and-hold approach was -45 per cent and, about -6 per cent for the trend following approach. From November 2007 to March 2009, the drawdown for the buy-and-hold approach was -51 per cent, and for the trend following approach, it was about -5 per cent.
The other key point is that the trend following approach tends to outperform “buy-and-hold” in an extended subpar market.
Though US stocks probably offer the best returns in the long term (10 per cent annually) among major asset classes such as non-US stocks, bonds, and commodities, they deliver sub-par returns for an extended period from time to time. This usually occurs when stocks move from overvaluation to undervaluation.
For instance, the CAPE ratio exceeded 22 times by mid-1995 and went on to hit 44 times by December 1999, which is the all-time high in its roughly 140 years of history. The ratio then came down to about 15 times by December 2008, which was below its long-term average of 17 times.
From 1995 to 2008 (14 years), the annualised return for the buy-and-hold approach was about 6.8 per cent and stocks had also experienced two major market crashes.
If investors had bought near the top in 2000, they would have seen a lost decade (2000-2009) as the annualised return for US stocks over the period was only -0.9 per cent. This might come as a shock to many investors as it is way below the often-cited long-term return of about 10 per cent annually.
What would have been the results if investors had used the trend following approach during those periods?
The annualised return with the trend following approach for the period 1995 to 2008 was 12.2 per cent and for the 2000s, it was 7.7 per cent.
What is there not to like about “trend following” ?
Initially, the buy-and-hold approach outperformed “trend following” from 1995 onwards but the table only started to turn in 2001. Hence, it requires patience before you see trend following outperforming the buy-and-hold approach.
Currently, the CAPE ratio is awfully expensive at 36 times by July 2024. As and when mean reversion kicks into the high gear, there is a strong possibility that stocks might move from overvaluation to undervaluation again.
In sum, it is time to consider the trend following approach when stocks are awfully expensive. However, many investors tend to ignore “trend following” as it is a market timing approach. Somehow the market timing approach has not been popular among investors.
Though trend following is a market timing approach, it can help investors to protect their capital during market downturns and ensure that they can also stick to their portfolios through thick and thin. At times, trend following can even enhance investment returns when investors are irrationally exuberant. The evidence so far is irrefutable.
The writer is a private investor. He was previously a researcher at an international business school in Europe, and an Asia-Pacific director at multinational corporations.






