

Weighing bank AT1 perps: Are you compensated enough for the risk?
Not all bank perpetuals are alike. Investors should get familiar with the loss-absorption mechanism of AT1 debt
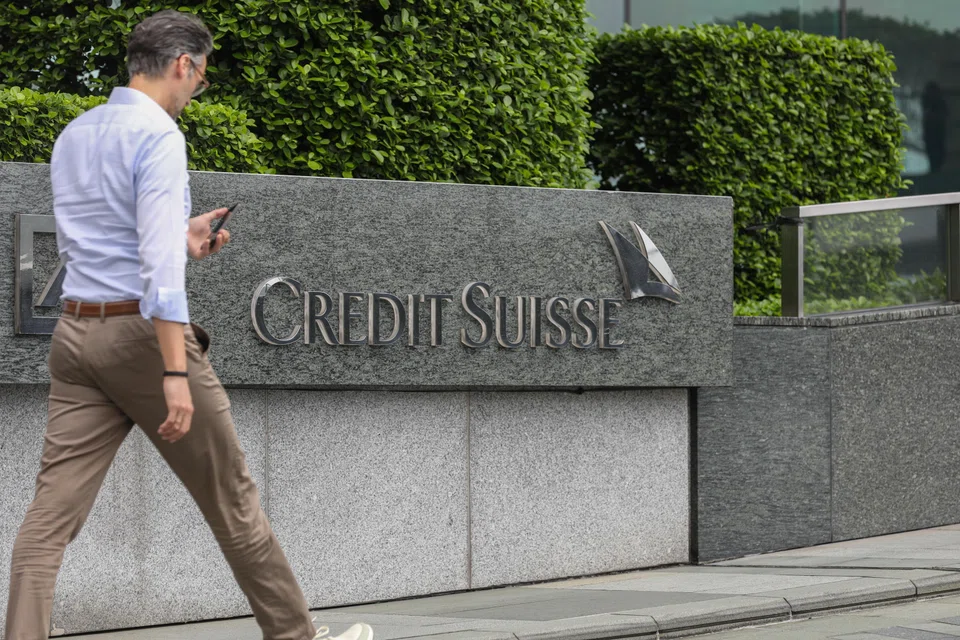
A SWISS bank perpetual note was recently in our portfolio, and I was none the wiser on its inherent risks – until the unprecedented, total writedown of Credit Suisse’s entire 16 billion Swiss francs worth of perpetuals.
Our investment in UBS’ 5 per cent US dollar perp was called in January, a happy outcome since our holding was short. The decision to invest wasn’t entirely by chance: Interest rates rose sharply last year, but when we invested in mid-2022, the note’s duration was short with less than a year to go before the expected call date. If the issue hadn’t been called, a step-up interest rate would compensate for a longer holding period.
Would I invest in a bank perp again? Perhaps. But such notes’ outsized risks – relative to banks’ senior bonds – would now make me think twice or three times. I would certainly peruse the offer documents, which I hardly did with the UBS issue, our portfolio’s first bank perp investment.
UBS was – and remains – a strong bank. At the time, deterioration in financial strength seemed remote. The US dollar exposure was also part of our portfolio’s currency diversification.
And yes, the banker’s argument was persuasive. Most banks would take pains to call their perps, so we were advised. Failure to call or redeem the bond sends a poor signal, and may make it more challenging for the bank to raise funds in the future. But Credit Suisse’s debacle has likely changed the calculus of bank perps in the minds of most investors and advisers – and that isn’t necessarily a bad thing.
Here are some things to note. Not all bank perps are alike. Investors need to scrutinise the offer documents. There are many reasons the instruments are classified as highly complex and open only to accredited investors and institutions.
AT1 and CoCo: Not all alike
Most articles on the takeover of Credit Suisse and the predicament of its AT1 bondholders explain the risks of perps. But it’s worth a recap. Bank perps are hybrid instruments, which emerged after the 2008 financial crisis to help cushion banks’ capital in a crisis. The instruments qualify as Additional Tier 1 or Tier 2 capital for banks under Basel III rules.
In terms of seniority in the capital structure, AT1 instruments are junior subordinated, which means they rank behind senior bonds, but ahead of equity holders.
In the Credit Suisse takeover, AT1 perps have come under the spotlight, because of the Swiss regulator’s decision to write them down completely. Shareholders have instead come out ahead as they still benefit from the 3 billion Swiss Franc (S$4.33 billion) takeover, albeit at a loss.
Many articles refer to AT1 issuances as contingent convertible (CoCo) bonds; and the terms are used interchangeably. But there are distinctions within the AT1 universe. While bank perpetuals qualify as AT1, not all AT1 issuances are CoCos. That is, not all are convertible into equity.
A paper by Lazard Freres Gestion found that of the US$254 billion in AT1 notes as at September 2020, CoCo bonds (with equity conversion) accounted for 40 per cent. About 31 per cent were issues with a temporary writedown feature, and 27 per cent of AT1s allowed a permanent writedown.
Loss-absorption mechanism
Loss-absorption triggers are broadly similar, especially Swiss bank AT1s, which comprise mainly UBS and Credit Suisse. Typically, there is a preset or mechanical trigger of a drop of the bank’s Common Equity Tier 1 (CET1) capital to 7 per cent. There is also a “viability” trigger – also called “point of non-viability’’ (PONV) – which is based on the regulator’s judgment on a bank’s solvency prospects.
A 2013 paper by Bank of International Settlement says: “PONV triggers allow a regulator to trump any lack of timeliness or unreliability of book-value triggers. However, unless the conditions under which regulators will exercise their power to activate the loss absorption mechanism are made clear, such power could create uncertainty about the timing of the activation.’’
This is what Credit Suisse perp documentation – and UBS as well – says about the viability event, described as an “irrevocable commitment of extraordinary support from the public sector” without which, in the regulator’s judgment, Credit Suisse “would have become insolvent, bankrupt, unable to pay a material part of its debts as they fall due or unable to carry on its business”.
To be clear, Credit Suisse was not insolvent. As at end-2022, its CET1 ratio was 14.1 per cent, well above the regulatory requirement, though it was loss-making. The big questions were whether client outflows could be successfully stanched, and whether the loss of confidence plus high restructuring costs would hurt their business franchises and cause CET1 ratio to deteriorate.
In a statement on its decision, Finma (Swiss Financial Market Supervisory Authority) said that as Credit Suisse was granted “extraordinary liquidity assistance loans secured by a federal default guarantee”, the conditions were met for a viability event.
At the same time, Switzerland’s Federal Council enacted an emergency ordinance which authorised Finma to order the borrower to write down its AT1 capital.
Singapore bank perps
Interestingly, perps issued by local banks have a similar loss-absorption mechanism to allow the Monetary Authority of Singapore (MAS) to make the call on a writedown of AT1s, based on documentation for DBS and UOB perps.
UOB’s documentation says the MAS could notify the issuer that it believes a write-off is necessary, or that it has decided that the bank needs a “public sector injection of capital or equivalent support” without which the issuer would become non-viable. The writedown could be partial or full.
To allay investors’ concerns following Finma’s decision on Credit Suisse’s AT1s, the MAS issued a statement that it aims to abide by the hierarchy of claims in liquidation. This means shareholders will absorb losses before AT1 and AT2 debtholders.
“Creditors who receive less in a resolution compared to what they would have received had the FI (financial institution) been liquidated would be able to claim the difference from a resolution fund that would be funded by the financial industry.
“The creditor compensation framework will also apply in the exceptional situation where MAS departs from the creditor hierarchy in order to contain the potential systemic impact of the FI’s failure or to maximise the value of the FI for the benefit of all creditors as a whole,” it said.
Scrutinising perps’ higher yield
Bank perps carry higher yields to compensate for higher risks. The most recent Credit Suisse’s AT1 issued last year carried a yield of 9.75 per cent.
While Credit Suisse’s AT1s’ legal documentation empowers Finma to make a call on when a viability event has occurred, some bondholders are reportedly looking to mount a legal challenge to Finma’s decision.
For now, if you see perps on your bank’s recommended list of bank bonds, ask yourself: Are you compensated enough for the risks you are taking, particularly at a time when deposits and short-term Treasury bills are paying you well over 3 per cent?
In the current environment, when risk aversion has caused credit spreads to widen, the risk is high that issuers may not call their AT1 debt at the expected call date. Or, issuers who are under pressure may also suspend coupon payments or, at worst, default.
The truth is, at this time when fixed income yields have risen, you need not overstretch for yield. If an issue looks very attractive, weigh the downside risks carefully.
We all know there is no free lunch in finance, but you would hate to have someone eat your lunch.






