

Where will the global economy land?
The full impact of the turmoil in the banking sector in the US and Europe may take some time to materialise. Maintain a defensive stance on risk assets
THE global economy is in flux. Financial markets provide ample evidence that they are finding it hard to gauge the way ahead.
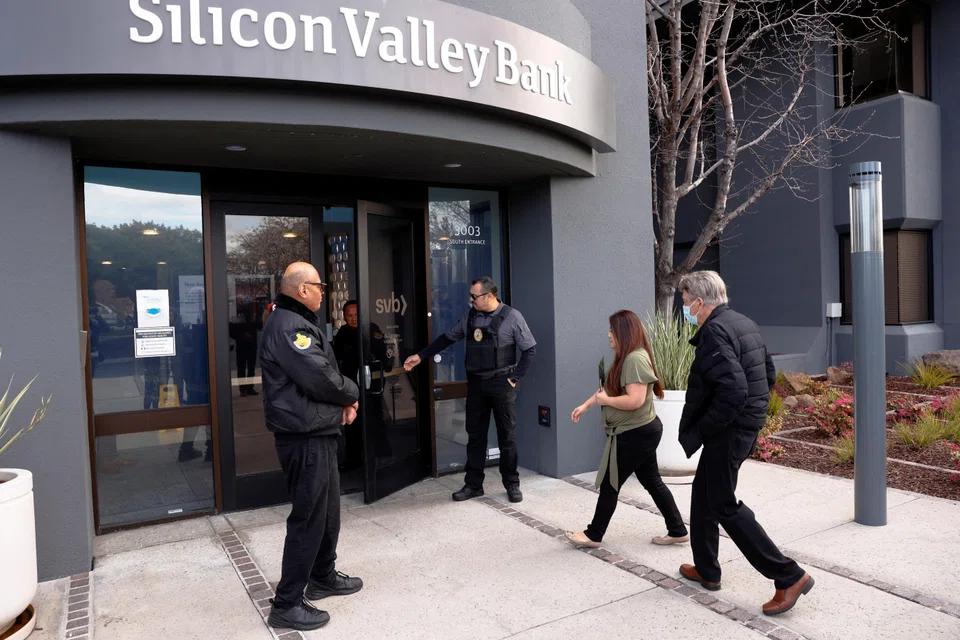
A liquidity event in the US regional banking sector in the past weeks has been the catalyst for a dramatic repricing of the macro outlook and interest rates cycle. There is no escaping the extreme level of uncertainty over the spillovers from the Silicon Valley Bank’s (SVB) collapse, and the subsequent turmoil in US and European banking.
Last week, the bond and equity markets experienced significant volatility, with the Move index, which measures bond market volatility, registering a more pronounced reaction than the VIX index, which itself reached 30 per cent on Mar 13. Notably, the Move index has risen to its highest level since the global financial crisis, surpassing its pandemic peak.
The collapse of SVB has heightened concerns that further interest rate hikes by the Federal Reserve could strain the financial industry.
Consequently, interest rates have declined sharply, with the two-year Treasury yield experiencing an unprecedented two-day movement, the likes of which have not been seen since the market crash in 1987. This has prompted many hedge funds with extreme short positions in short-term US bond futures to hedge or exit their positions, thereby amplifying the volatility in the bond market.
The full ramifications of this crisis could take some time to materialise, adding to the case for prudent policymaking. Central banks are likely to be more cautious as they monitor the tightening in credit conditions.
However, one major difference from previous banking crisis episodes is a more resilient macro backdrop, including persistent inflationary pressures. This will make for a difficult trade-off between inflation and financial stability risks, with central banks trying to resist rate cuts for as long as possible.
Given market fundamentals, our investment positioning was already defensive before the SVB event. The rise in central banks’ rates combined with already high valuations have kept us underweight on risky assets in general. Banks’ earnings will very likely need to be revised lower in the coming weeks, with negative implications for overall 2023 earnings estimates. We intend to keep a defensive stance while monitoring the situation.
Global impact of China’s reopening
S&P Global’s purchasing manager index (PMI) for global manufacturing rebounded to 50 in February, after five months in a row below the 50 mark that divides contraction from expansion.
But the situation is not universally rosy yet. There is a large discrepancy between emerging and advanced economies, and we currently see a bifurcation in global business sentiment. Given persistent inflation, businesses in western economies remain under pressure from aggressive monetary policy, whereas emerging economies are being pulled along by Chinese reopening.
No V-shape rebound expected for China
China’s economy continued to recover in February after the long Chinese New Year holiday. Urban mobility has returned to above pre-pandemic levels, with the removal of all controls on movements helping to resolve supply-chain disruptions.
The PMIs for February rose sharply for both manufacturing and non-manufacturing. The improvement was broad based, with almost all sub-indices above the 50-threshold.
The strong PMI readings are consistent with our view that China’s economic rebound will likely be front loaded in 2023. We expect growth momentum to remain elevated in the near term, perhaps peaking in the second quarter.
While the latest PMI numbers are encouraging, we are not expecting a V-shaped rebound in the Chinese economy. After a traumatic 2022 due to stringent Covid controls, we expect the improvement in household and business sentiment to be gradual.
Lingering weakness in the labour market and falling household expectations for income growth will likely constrain the rebound in domestic consumption, while waning global demand will likely weigh on China’s manufacturing sector in 2023. Our forecast for China’s gross domestic product this year remains at 5 per cent for the time being.
Risk assets still challenging
The pressure on margins, combined with still-elevated interest rates, economic and geopolitical uncertainties and high valuations explain why we remain underweight on equities overall, particularly US equities, where the equity premium over bonds has been falling.
While still underweight, a relatively satisfactory Q4 earnings season and comparatively low valuations leave us with a more upbeat view of euro area equities.
We remain neutral on equities in Emerging Markets Asia (already benefitting from China’s re-opening) and Switzerland (for their defensive qualities), as well as the United Kingdom (where large-cap indexes are dominated by energy, financial and commodities companies) and Japan (where economic growth is steady and inflation relatively mild).
Overall, higher bond yields, modest earnings expectations and an uncertain economic and geopolitical environment all offer plenty of scope for renewed equity (as well as bond) volatility.
Making sense of bonds
The fading risk of a near-term recession and some strong data out of the United States may mean that inflation issues persist, inducing central banks to remain hawkish for now.
As a result, bond yields have come under renewed upward pressure in recent weeks. Yet, 10-year yields today look more attractive than a year ago, especially compared to equities. With short-term inflation expectations still high, we believe attractive yields can be found further out along the curve, in US Treasuries in particular.
At the same time, an over-rapid tightening of credit spreads is prompting us to remain underweight non-investment-grade bonds exposed to higher default risk and to continue to favour “safe” carry in investment-grade (IG) issues – especially in Europe, where yields on short-dated IG bonds still look attractive (in the financial sector, for example) when set against the earnings yield on equities.
Emerging Market equities: China reopening trade reverses
February provided yet more evidence that emerging market equities remain a high-beta play. After outperforming developed markets in January on the back of a swift rebound in global equities, they underperformed by more than 4 per cent in February as markets digested the risk of higher-for-longer policy rates in the US, which triggered a rise in the US dollar.
Having rallied massively since November, Chinese offshore equities slumped as geopolitical tensions with the US resurfaced; tech firms produced underwhelming earnings; and many hedge funds seemingly booked gains ahead of the National People’s Congress in early March.
It is, however, worth noting that fundamentals in China remain solid, with most sectors exhibiting rising forward earnings as the economy swiftly reopens. We are keeping our positive view on Chinese equities for now.
Widening scope of private investing
As banking-sector regulations have tightened, borrowing from private sources has become a reality for European small and medium enterprises (SMEs) that have historically suffered from limited access to financial markets. Direct lending to solid SMEs may look attractive to borrowers – and to long-term investors – at a time of sticky inflation and high interest rates.
Interest is also increasing in investing directly in European SMEs, more generally. Many of them need fresh capital and specialist competence to develop, while private investors can expand the investable universe to include companies that are the backbone of Europe’s economy and often at the forefront of innovation in areas like energy and digitalisation.
Direct investments avoid the short-term pressures and volatility of public markets, allowing parties to focus on creating long-term value.
The healthcare, technology and environmental sectors are also becoming specific focuses for private equity. Global private equity deals fell sharply in H2 22 as market participants struggled to gauge a path for interest rates and growth; bank funding dried up; and doubts grew over existing investments’ valuations.
Yet the market is showing signs of improving again, with private equity and credit increasingly filling the funding gap left by cautious banks.
The writer is Asia chief investment officer and head of discretionary portfolio management, Pictet Wealth Management.






