

CapitaLand China Trust H2 DPU down 11.7% at S$0.0233 on lower retail, business park revenue
One of its manager’s priorities for 2026 is to source a replacement asset for CapitaMall Yuhuating
[SINGAPORE] The manager of CapitaLand China Trust (CLCT) on Thursday (Feb 5) posted a distribution per unit (DPU) of S$0.0233 for the second half ended Dec 31, 2025, down 11.7 per cent from S$0.0264 for the year-ago period.
Its full-year DPU of S$0.0482 was 14.7 per cent lower than the DPU of S$0.0565 for FY2024, translating to an implied yield of 6.2 per cent, based on its closing price of S$0.775 on Dec 31, 2025.
The declines were due to lower performance from the trust’s retail and business park segments, as well as a weaker renminbi against the Singapore dollar.
But these were partly offset by lower finance costs and management fees, as well as higher realised foreign exchange gain, the manager of the China-focused real estate investment trust (Reit) said.
Gerry Chan, chief executive officer of CLCT’s manager, said that the Reit delivered a “credible performance” for FY2025 amid a “challenging operating environment”.
“We continue to elevate the quality of our retail assets with targeted asset enhancement initiatives (AEIs) and customer-centric offerings to drive long-term income growth.”
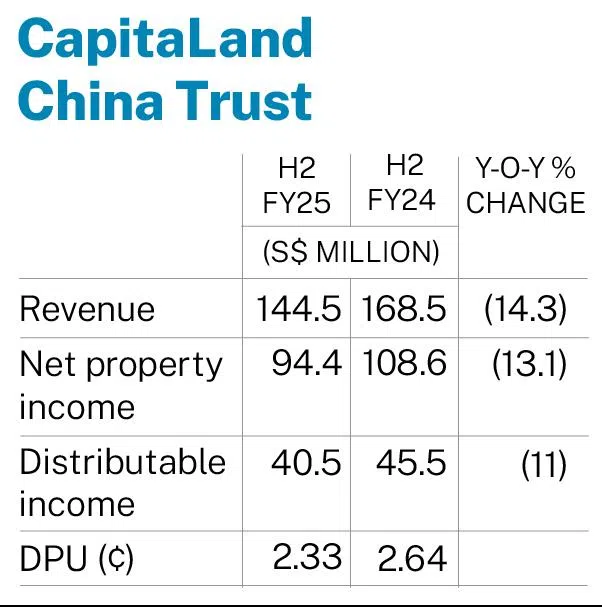
For the six months, revenue fell 14.3 per cent year on year to S$144.5 million, from S$168.5 million. Full-year revenue fell 11.1 per cent to S$303.7 million, from S$341.5 million.
This was partly due to the absence of contributions from CapitaMall Yuhuating from April to December 2025, following its divestment to CapitaLand Commercial C-Reit (CLCR) which listed on the Shanghai Stock Exchange in September.
Chan noted plans to “actively source for new investments” to reconstitute CLCT’s portfolio following the divestment of CapitaMall Yuhuating and the establishment of CLCR.
Chan said that CLCT is looking for a retail asset in the light of the sector’s defensiveness. “In terms of cities, we are casting our net wide. Right now, in our minds, it’s Tier 1 and Tier 2 cities that we are looking for,” he added.
“In terms of the size, we will calibrate it accordingly. What we have said is that we want to replenish (CapitaMall) Yuhuating’s lost income and perhaps just exceed it slightly. But I don’t think we’ll do too big an acquisition that will stretch the balance sheet.”
As to whether the asset will come from CLCT’s sponsor pipeline or be acquired externally, You Hong, the trust’s head of investment and portfolio management, said the Reit manager is open to both and would want an asset with “a bit of a value-add angle”.
“We are following (up) on a number of leads. But we also want to be prudent at the moment, because although retail is one of the more resilient asset classes, consumer sentiment and all that still remain. So I think we want to be very careful in selecting the right city, right location,” said You.
“We are cautiously confident that we should be able to do something this year.”
To make up for the loss of income from divestments, a one-off top-up of S$0.0033 – from past divestment gains – was incorporated into H2’s DPU, bringing it to S$0.0233, from S$0.02 before the top-up, the manager said.
“CLCT will leverage our unique Singapore-Reit and China-Reit connections to pursue high-quality and accretive assets over the long term,” it said.
The decline in revenue in FY2025 was also a result of downtime from AEIs at CapitaMall Xizhimen, Rock Square, CapitaMall Wangjing and CapitaMall Xuefu, alongside lower occupancy and rental rates at CapitaMall Xinnan, CapitaMall Wangjing, CapitaMall Grand Canyon and Ascendas Innovation Towers.
The retail and business park segments logged revenue declines, while the logistics park segment’s revenue increased.
Net property income (NPI) for the second half decreased 13.1 per cent to S$94.4 million, from S$108.6 million in the previous corresponding period. NPI for FY2025 was down 11.3 per cent year on year at S$200.9 million, from S$226.6 million.
This was driven by a drop in revenue and the absence of contributions from CapitaMall Yuhuating, said the manager. This was partially offset by a 4.3 per cent year-on-year cost reduction, on a same-store basis.
For H2 FY2025, the amount distributable to unitholders fell 11 per cent to S$40.5 million, from S$45.5 million in H2 FY2024. The amount distributable to unitholders for the full year stood at S$83.9 million, a 13.3 per cent decline from S$96.8 million.
The distribution will be paid out on Mar 27.
In terms of capital management, the Reit’s total debt stood at S$1.7 billion as at Dec 31, 2025, down from S$1.9 billion in the year-ago period.
CLCT had an aggregate leverage of 40.7 per cent as at Dec 31, 2025, compared with 41.9 per cent a year earlier. Its borrowings had an average term to maturity of 3.5 years.
CLCT’s retail portfolio had a committed occupancy of 97.2 per cent, down from 98.3 per cent a year earlier. Its business park portfolio occupancy inched down to 86.7 per cent, from 87.6 per cent, while its logistics park portfolio occupancy rose to 98.1 per cent, from 97.6 per cent.
Chan said: “We feel that going forward for 2026, our rents have bottomed in our logistics portfolio, and we aim to maintain the full occupancy at these rent levels.”
When asked whether CLCT has any plans to divest logistics or business parks assets as well, he said: “We want to continue to maintain stable occupancy across business parks and logistics parks, so I think that’s the first step that we have to do.
“Business parks – at the current stage, we still need to push up occupancy. When the occupancy of some of our weaker business parks has stabilised, then we can talk... If you want to reconstitute the asset or divest the asset, it has to be in good condition.”
Units of CLCT fell 0.6 per cent or S$0.005 to S$0.78 on Thursday, after the results were posted.
TRENDING NOW

Genting Singapore trails MBS, but helps anchor Malaysian parent group’s finances

Siti Hasmah Mohamad Ali, wife of former Malaysian PM Mahathir Mohamad, dies aged 100

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Why US midterm elections could power the next stock market rally

