

CapitaLand China Trust’s Q3 NPI down 5.1% at 259.6 million yuan
Revenue for Q3 declines 4.1% year on year to 399.7 million yuan
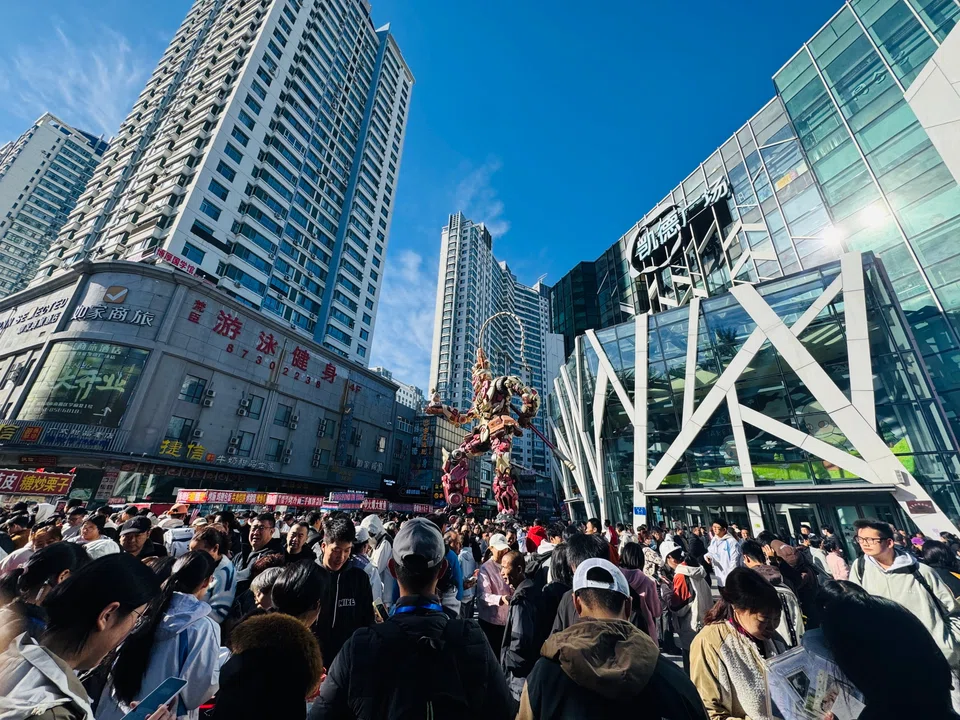
[SINGAPORE] CapitaLand China Trust (CLCT) posted net property income (NPI) of 259.6 million yuan (US$38.9 million) for its third quarter ended Sep 30, down 5.1 per cent from 273.5 million yuan in the previous corresponding period.
Revenue for the real estate investment trust (Reit) in Q3 fell 4.1 per cent year on year (yoy) to 399.7 million yuan from 416.6 million yuan, the manager said on Friday (Oct 23) in a business update.
Retail revenue declined 2.9 per cent yoy to 286.3 million yuan from 294.8 million yuan, while business park revenue fell 6.2 per cent to 100.6 million yuan from 107.3 million yuan.
Logistics park revenue dropped 11.7 per cent yoy to 12.8 million yuan from 14.5 million yuan.
For the nine months ended September, CLCT’s NPI fell 3.9 per cent yoy to 820.6 million yuan from 853.8 million yuan, while revenue declined 4.8 per cent to 1.22 billion yuan from 1.28 billion yuan.
The decline in revenue was mainly attributed to the divestment of CapitaMall Yuhuating, as well as lower occupancy and rental rates at CapitaMall Xinnan, CapitaMall Grand Canyon, CapitaMall Wangjing and CapitaMall Aidemengdun.
Revenue from the business park and logistics park segments fell 4.1 per cent yoy for the nine-month period, mainly due to weaker performance at Singapore-Hangzhou Science & Technology Park Phases I and II, Kunshan Bacheng Logistics Park, Wuhan Yangluo Logistics Park and Chengdu Shuangliu Logistics Park.
This was partially offset by improved occupancy at Shanghai Fengxian Logistics Park, the manager said.
Excluding CapitaMall Yuhuating’s contribution in the first half of 2025, NPI for the nine months would have fallen 0.8 per cent yoy on a same-store basis, while revenue would have declined 1.5 per cent.
The manager noted that the decline in nine-month NPI was partially mitigated by a 3 per cent yoy reduction in costs on a same-store basis.
However, in Singapore dollar terms, NPI increased 1.9 per cent yoy for the nine-month period, supported by a 2.6 per cent appreciation of the yuan.
Meanwhile, CLCT’s portfolio shopper traffic rose 1.9 per cent yoy for the nine months ended September, while tenant sales grew 3.5 per cent.
Excluding automobile sales, tenant sales would have increased 8.4 per cent yoy, while tenant sales per square metre would have risen 2.1 per cent.
Sales growth was led by the toys and hobbies sector, which recorded a 39.5 per cent yoy increase amid the continued popularity of collectible toys.
This was followed by the sporting goods and apparel sector, which posted 37.3 per cent growth, the IT and telecommunications sector at 10.2 per cent, and the F&B sector at 2.6 per cent.
Retail occupancy stood at 97.2 per cent as at Sep 30, up slightly from 97.1 per cent a year earlier.
Retail rental reversion came in at negative 3 per cent for the nine months ended September, reflecting strategic leasing decisions to upgrade two major anchor tenant spaces.
Excluding the two planned anchor tenant adjustments and electric vehicle tenants, retail rental reversion would have been negative 2.5 per cent.
Business park occupancy improved to 85.7 per cent as at end-September, from 85.2 per cent a year earlier.
However, rental reversion for the business park portfolio stood at negative 12.6 per cent for the nine-month period, compared with negative 8.9 per cent in the corresponding period the previous year.
The manager said it prioritised occupancy through tenant retention and active leasing, securing around 175,000 square metres of renewals and new leases in the first nine months of 2026. This represented about 22.9 per cent of the business park portfolio’s total net lettable area.
Meanwhile, logistics park occupancy rose to 98.6 per cent as at end-September, from 96.6 per cent a year earlier.
Rental reversion for the logistics park portfolio improved to negative 1.3 per cent for the nine-month period, compared with negative 24.5 per cent for the full year of 2025, supported by leasing and tenant retention initiatives.
Capital management
In terms of capital management, CLCT’s total debt as at Sep 30 stood at about S$1.78 billion.
Aggregate leverage rose to 41.1 per cent in September from 40.4 per cent as at end-June, but was below the adjusted 41.3 per cent recorded a year earlier.
The interest coverage ratio improved to three times from 2.9 times as at end-June, while the average cost of debt eased to 3.04 per cent from 3.06 per cent.
The average term to maturity shortened to 2.7 years from three years as at end-June.
The manager noted that proactive capital management contributed to a reduction in the average cost of debt, resulting in interest savings of 14 per cent yoy.
It added that a 600 million yuan bond carrying a 3.8 per cent interest rate due in October 2026 had been refinanced through credit facilities at an effective cost of around 2.3 per cent.
Outlook
The manager noted that China’s economic growth continued to be supported by policy measures and industrial momentum, with manufacturing activity returning to expansion in September.
The manager said growth in high-tech manufacturing, technology services and strategic industries continued to support demand for business parks and logistics facilities.
Retail consumption was also supported by policy initiatives aimed at stimulating household spending, although the recovery remained gradual.
However, the manager noted that an extension of the US-China trade truce could reduce near-term trade uncertainty and support business confidence and domestic consumption.
“As these developments progress, second-order effects may emerge over time and will continue to be closely monitored,” the manager said.
The Reit plans to expand its retail presence in China’s Tier 1 and Tier 2 cities while maintaining stable occupancy across its business and logistics park portfolios.
It will also continue to evaluate asset enhancement opportunities at existing malls and potential acquisition targets, while identifying mature assets for recycling to unlock value and optimise its portfolio.
On capital management, the manager aims to expand access to yuan-denominated debt to balance currency hedging requirements and lower borrowing costs.
Units of CLCT closed flat on Thursday at S$0.605.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW
Easy to rent out, hard to sell: Are buyers losing interest in Singapore’s one-bedroom condos?

GovTech retrenches another 38 staff in second round of layoffs
Stocks to watch: Seatrium, CapitaLand Investment, Keppel DC Reit, Suntec Reit, CLCT, TSH Resources

World’s largest offshore wind platform by Seatrium consortium on track to be completed by 2028

