

Centurion Accommodation Reit’s 9M net property income of S$117.7 million beats forecast by 4.8%
Gearing rises to 30.7%, but debt headroom remains at S$350.1 million
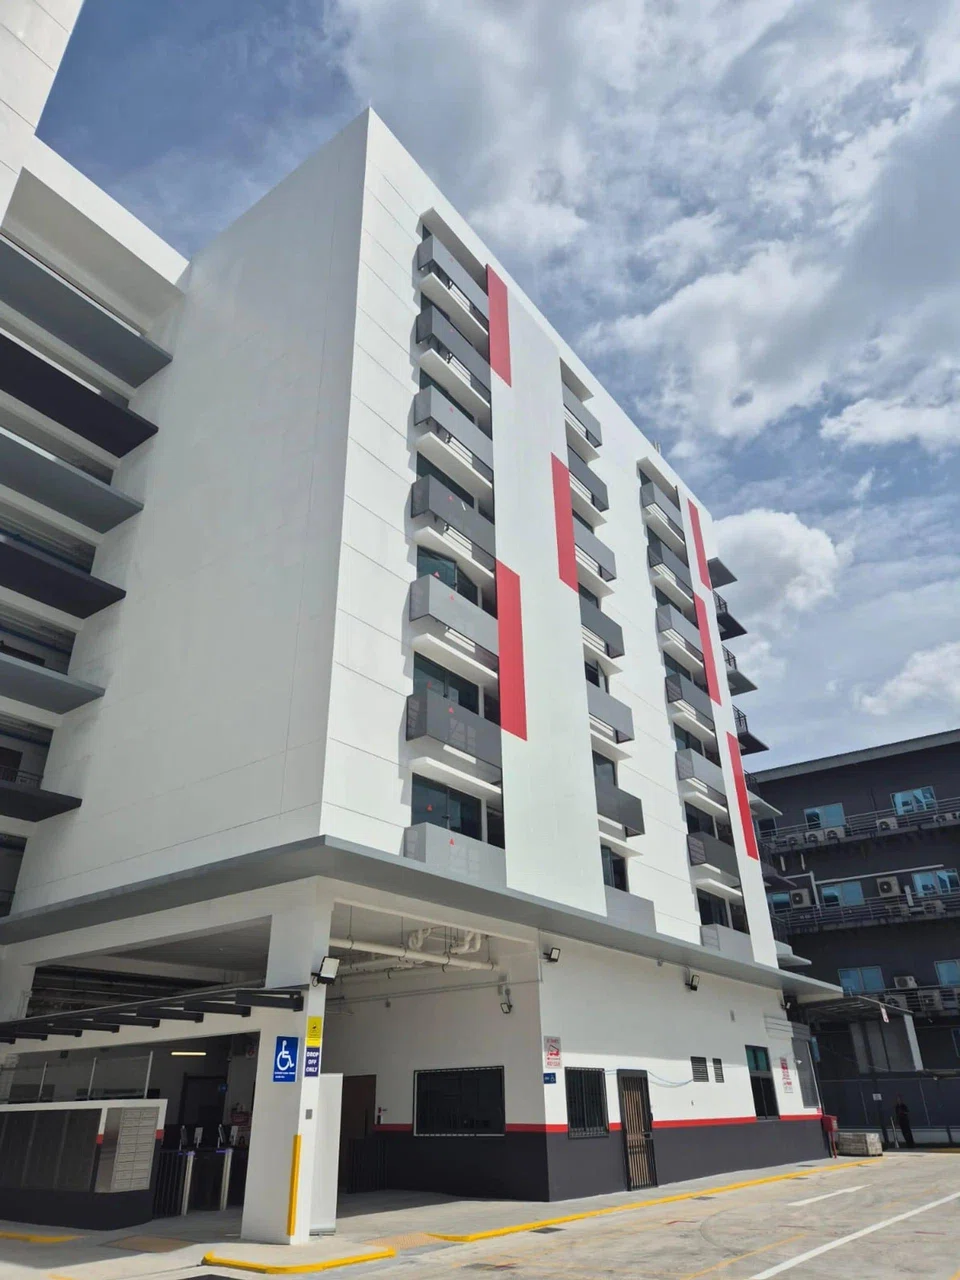
[SINGAPORE] Centurion Accommodation Reit (CAReit) posted net property income (NPI) of S$117.7 million for the nine months ended Sep 30, coming in 4.8 per cent above its prospectus forecast.
The better-than-expected performance was helped by higher rental rates at its Singapore worker dormitories and new bed capacity, the real estate investment trust’s manager said in a business update on Wednesday (Nov 4).
Gross revenue came in at S$164.4 million, 5.7 per cent ahead of the S$155.6 million forecast in the Reit’s initial public offering prospectus dated Sep 18, 2025.
For the third quarter, NPI came in at S$39.3 million, beating the forecast of S$37.2 million by 5.7 per cent. Revenue was S$55.5 million, 6.9 per cent above the S$51.9 million projected.
The Reit, which listed on Sep 25, 2025, has no year-ago figures to compare against, so results are measured against the forecast.
The manager, Centurion Asset Management, attributed the outperformance to higher rental rates across its purpose-built worker accommodation (PBWA) portfolio and higher occupancy at Westlite Ubi, Westlite Woodlands and Westlite Juniper.

Expanded capacity at Westlite Toh Guan and Westlite Mandai contributed an additional S$2.3 million in revenue. Currency movements also helped, with the pound and Australian dollar strengthening against the Singapore dollar.
These gains were partly offset by moderating rental rates and fewer beds available for sale in the UK student accommodation portfolio, because of ongoing and upcoming asset enhancement initiatives (AEIs). Sales and marketing expenses for the 2026/27 academic year were also higher.
The PBWA portfolio contributed 73.2 per cent of revenue and 75.1 per cent of NPI in 9M 2026.
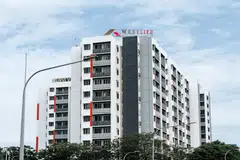
PBWA financial occupancy was 92.6 per cent, slightly below the 93.0 per cent forecast, as new capacity at Westlite Toh Guan and Westlite Mandai was phased in.
Committed occupancy rose to 98.1 per cent as at Sep 30, from 94.3 per cent at the end of June. It reached 99.7 per cent at Westlite Toh Guan and 95.1 per cent at Westlite Mandai.
Financial occupancy for its Purpose-built student accommodation, meanwhile, was 95.6 per cent, against the 96.0 per cent forecast.
UK occupancy came in at 94.7 per cent, versus the 95.1 per cent forecast, while Australia occupancy was 97.8 per cent, below the 98.1 per cent forecast.
UK rental rates moderated year on year for the 2026/27 academic year, though occupancy matched the previous year.
Capital management
CAReit’s aggregate leverage was 30.7 per cent as at Sep 30, up from 29.9 per cent at end-June. Debt headroom, based on a 40 per cent gearing limit, narrowed to S$350.1 million from S$380.0 million.
The weighted average financing cost was 3.65 per cent, excluding the amortisation of upfront and other fees, below the 4.07 per cent forecast. About 69.3 per cent of borrowings were hedged to fixed rates, down from 71.6 per cent at end-June.
The Reit’s interest coverage ratio was 5.66 times, against 5.91 times at end-June. None of its drawn debt matures until the financial year ending 2028, and the weighted average debt maturity is 3.4 years, the manager said.
Westlite Woodlands redevelopment
CAReit has obtained planning permission for an AEI at Westlite Woodlands to build two new blocks, subject to technical and regulatory requirements. Construction is targeted to begin in the first half of 2027 and be completed by the first half of 2029.
The project will raise the property’s capacity to about 5,528 beds by 2029, from about 4,100 now. It is also meant to offset capacity cuts needed to meet the Interim Dormitory Standards by 2030 and the New Dormitory Standards by 2040, under the Dormitory Transition Scheme.
Without the new blocks, capacity would fall to about 3,685 beds from 2031 and about 3,024 beds from 2041. With them, it would be about 5,190 and 4,506 beds, respectively.
At Westlite Ubi, a six-storey block adding 540 beds is expected to be operational in Q4 2027.
Outlook
For FY2026, the manager said it “expects gross revenue to exceed the prospectus forecast”.
It cited favourable rental rates and occupancy in the PBWA portfolio, plus about S$3.5 million in additional revenue from the expanded Toh Guan and Mandai capacity.
It cautioned that actual contributions depend on tenant check-in timing and the ramp-up at Westlite Mandai.
The manager will also evaluate acquisitions of PBWA and PBSA assets from its sponsor Centurion Corporation and third parties. Centurion Corporation has granted CAReit a right of first refusal over the sponsor’s stake in assets within the Reit’s mandate.
“Our revenue and NPI outperformance in 9M 2026 reflects the strength of CAReit’s underlying portfolio fundamentals and sustained demand for quality accommodation,” said Tony Bin, chief executive of Centurion Asset Management.
Units of CAReit closed 0.02 per cent or S$1.07 higher at S$1.07 on Wednesday, before the results were announced.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW
US midterms: What investors can expect after Democrats shatter Republican strongholds
Dip buyers emerge for tech stocks as traders look past midterms, focus on fundamentals
Former CEO of SGX-listed GS Holdings charged over false trading
Waymo founder predicts ‘landslide’ robotaxi adoption in Singapore, driven by high car costs

