Clas stays upbeat on US student housing despite 15% drop in segment’s H2 gross profit
Chief executive of Clas’ managers Serena Teo says they will take ‘drastic measures’ to boost occupancy and leasing rates in the next academic year
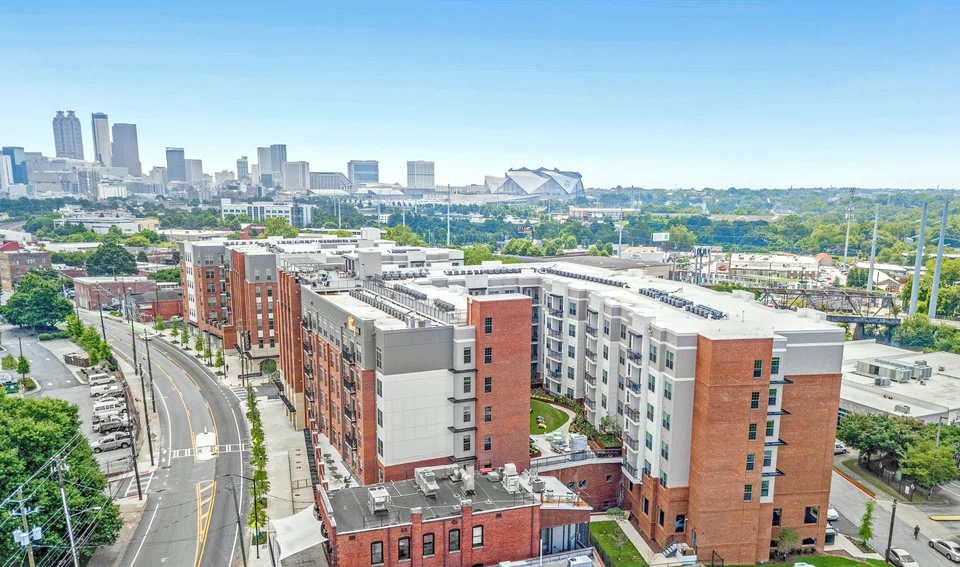
[SINGAPORE] The managers of CapitaLand Ascott Trust (Clas) said that they remain optimistic about the US student housing market even as gross profit from the segment fell 15 per cent year on year in the second half of FY2025.
In an earnings briefing on Friday (Jan 30) morning, following the results release the night before, chief executive of the managers Serena Teo pointed to temporary supply shocks and “execution” factors for the decline in gross profit, rather than a deterioration in demand fundamentals.
For one, the university markets that Clas has targeted have attracted more competition due to strong enrolment growth and rising room rates.
Lai Dongliang, the managers’ investment and asset management head, noted that the decline in gross profit is likely “a short-term blip”, given the still-healthy full-time student-to-bed ratio.
Teo added: “If you look at the overall occupancy of the student accommodation space, that has (fallen). Are we happy with it? No. It has come (down) to about 89 per cent, versus our typical 90 to 95 per cent. So there is some money left on the table, in terms of growth.”
But the 1 per cent valuation gain in Clas’ purpose-built student accommodation portfolio in the US, despite the decrease in gross profit, showed that it still has “inherent value”.
“It really comes down to execution this year,” she said.
The managers are therefore looking at “more drastic measures” to boost occupancy and leasing rates for the next academic year. These could include imposing penalties on underperforming managers or replacing them to ensure that execution on the ground “is at least on a par with what we would expect of that property”, she said.
Teo said pre-leasing levels for 2026/2027 are currently better than those in the previous year. “We’re hoping to improve some of these gaps in execution… to bring the properties back to their full potential.”
Meanwhile, the managers expect continued growth in the trust’s other key markets and sectors in the coming quarter.
Revenue and occupancy in the Singapore and Australia properties are expected to be supported by a “very vibrant” events calendar, Teo said. Also, the trust’s properties in France are likely to benefit from recent renovations and ongoing asset-enhancement initiatives (AEIs).
In Japan, she noted a slight dip in Chinese guests, given the “recent developments” between the two countries. But demand from Clas’ other markets, particularly Seoul in South Korea, is likely to offset any softness.
Over in the UK, the temporary closure of The Cavendish London hotel in the Mayfair district for renovation works could weigh on the coming quarters’ results. But Teo believes that the property will deliver higher rates and income once the works are completed and the hotel reopens in 2027.
She added that Clas could use non-recurring income to top up any potential losses from the London property or other major AEI projects.
Stable distributions
For H2 ended Dec 31, 2025, distribution per stapled security inched up around 1 per cent to S$0.0358.
This follows an about 4 per cent increase in revenue to S$439.1 million, and a more than 2 per cent rise in gross profit to S$202.8 million.
Meanwhile, income available for distribution in H2 jumped nearly 19 per cent to S$160.2 million.
At the earnings briefing, Teo highlighted that it was the first time in a while that the managers are retaining some of the distributable income. Doing so would enable them to deliver a stable distribution of around S$0.061 on a full-year basis, while “improving the quality of earnings within the trust to achieve a higher core distribution on a sustainable basis”, she added.
Gross profit margins improved 0.5 percentage point on the year, after excluding property tax and other adjustments, from 45.8 per cent in FY2024 to 46.3 per cent in FY2025.
Teo attributes the slight increase to higher occupancy rates across Clas’ properties.
“When there is an increase in the top line, typically we have a much larger revenue base to spread costs over, and that has driven the improvement in gross profit margin,” she said. “There are other factors as well, such as tighter cost control, but nothing really beats improving the top line when it comes to improving margins.”
Asked about the impact of the Singapore dollar potentially reaching parity with the US dollar on the trust’s geographical exposure or asset mix, Teo replied that the managers follow a disciplined approach to overseas investments. This includes focusing on currency management, hedging and, most importantly, risk-adjusted returns.
“When that profile falls below our required threshold, that’s when we would consider other actions, including divestments or redeploying capital into other markets,” she said. “That, I think, is the discipline that Clas applies as we assess which markets to enter or exit.”
Stapled securities of Clas closed S$0.015 or 1.6 per cent higher at S$0.98 on Friday.