

Top Glove trims Q2 loss to RM51.2 million, aims to return to profit in 2 quarters
Megan Cheah
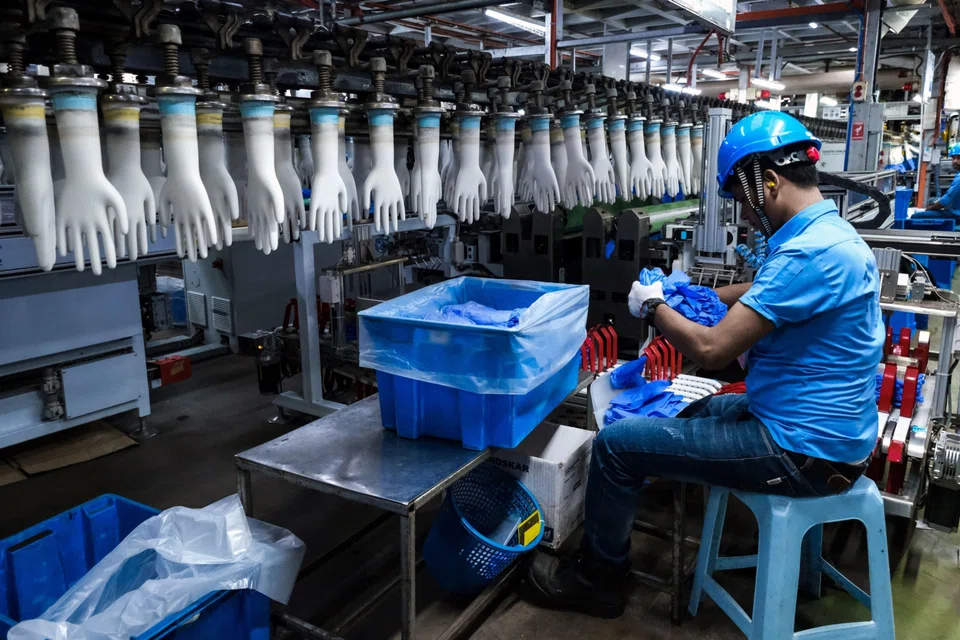
TOP Glove Corporation executive chairman Lim Wee Chai expects the company to return to the black by FY2025, as Malaysian glove-makers continue to close the price gap with competitors in Thailand and China.
Speaking at Top Glove’s second-quarter earnings briefing on Wednesday (Mar 20), Dr Lim noted that Thai and Chinese glove-makers were increasing their glove prices. This has resulted in an overall increase in the average selling prices (ASPs) of the products.
This, in turn, has allowed Top Glove to raise its own prices. It had attempted to do so in the past, but was unable to sustain the move due to its non-Malaysian peers’ low prices.
Dr Lim estimated that ASPs for the company’s products are now about 10 per cent higher compared to the last quarter, while Thai and Chinese glove prices have gone up 10 to 15 per cent.
This, coupled with expected softening of raw material prices for latex and nitrile, as well as the fact that customers have exhausted their supply of gloves purchased during the Covid-19 pandemic, has Top Glove’s management pushing for profitability.
“Give us two more quarters, and we should be able to turn (a) profit,” Dr Lim said.
The glove manufacturer said that its losses for the quarter ended Feb 29, 2024, narrowed by 68.9 per cent. The company reported a net loss of RM51.2 million (S$14.7 million), from RM164.7 million in the corresponding year-ago period.
This translated to a loss per share of 0.64 sen, falling from 2.06 sen in Q2 FY2023.
The group attributed the improved results to its ongoing quality- and cost-optimisation initiatives, coupled with operational enhancements it had previously laid out in its turnaround plan.
Revenue for the period, however, fell 11 per cent to RM550.3 million, from RM618 million year on year.
In its review, the group said sales volume strengthened 18 per cent against the preceding quarter as customers placed new orders following the depletion of excess inventory.
The increase provides a good indication of glove demand picking up, it added.
The company is targeting a monthly sales volume of 2.5 billion to three billion to achieve its goal of profitability in the second half of the year, said managing director Lim Cheong Guan. It had a monthly sales volume of around two billion in Q2 FY2024.
However, he noted that it would also depend on the raw material prices at the time, as the company recently faced raw material prices escalating at a faster pace than ASPs, which ate into profit margins.
For example, natural rubber latex concentrate prices rose 15 per cent at end-February as compared to end-November last year, the company stated in its results review.
That said, the increase in sales volume mitigated the rising raw material costs, and the company believes the expected softening of such prices later in the year will be to its advantage.
The returning demand for gloves has also allowed the company to recommence production in some factories that it had temporarily decommissioned post-Covid.
Executive director Ng Yong Lin said that Top Glove’s utilisation rate is now up to 50 per cent, from 40 per cent previously, with more plants expected to come back online in the coming months.
On a broader scale, managing director Lim noted that the ongoing Red Sea crisis has no significant impact on the company, as Top Glove uses a free onboard sales system that ensures customers shoulder the costs of shipping.
Compared to the previous quarter, Top Glove’s revenue rose 12 per cent from RM493 million. Its net loss also narrowed 12 per cent on-quarter from RM58 million.
On a half-year basis, the group’s revenue lowered 17 per cent on-year to RM1 billion from RM1.3 billion.
Its H1 net loss shrank 67.3 per cent to RM108.9 million, from RM332.9 million in the year-ago period.
The group is maintaining a positive mid- to long-term outlook on the glove industry, as gloves are “an essential, single-use item in the healthcare, industrial and F&B sectors with no viable replacement”.
Top Glove is listed in Malaysia and has a secondary listing in Singapore.
After the results were released, shares of Top Glove in Singapore closed at S$0.245, climbing 8.9 per cent or S$0.02.
On Bursa Malaysia, its counter leapt 8.2 per cent or RM0.065 to close at RM0.86.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

US dollar falters after Iran’s offer to reopen Hormuz sends oil lower

Temasek’s Wan Chee Foong to helm PIL, Lars Kastrup to be board adviser

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing

