

HK-listed engineering firm Metasurface files for dual primary listing on Catalist
Firm is issuing a new share placement as part of SGX debut
[SINGAPORE] Precision engineering services provider Metasurface Technologies has lodged a preliminary offer document with the Singapore Exchange (SGX) for a dual primary listing on the Catalist board.
The Singapore-based company, which specialises in precision machining and precision welding for international customers in the industrial sector, has been listed on the Hong Kong Stock Exchange since July 2024.
Metasurface will be issuing a new share placement as part of the Catalist listing, it said on Tuesday (Sep 29). UOB Kay Hian is the sponsor, issue manager and placement agent.
Proceeds from the placement will fund the acquisition of five-axis machines and advanced software, supporting the firm’s strategy to deepen its presence in the data storage, aerospace and oil and gas segments through potential joint ventures and acquisitions.
Shares of Metasurface in Hong Kong are up about 135 per cent in the year to date, from HK$1.50 to HK$3.52. It has a market capitalisation of about HK$523 million (US$66.7 million).
The company said the final offer document will be made available when the placement is launched.
Semiconductor exposure
Its precision component engineering services support customers in high-end manufacturing sectors, including the semiconductor industry, said Metasurface in a bourse filing.
It added that its international customer base is mainly drawn from the semiconductor, aerospace and data storage segments, and includes customers with manufacturing bases in Singapore, Malaysia, Japan, the US, South Korea and India.
Despite its international reach, the group faces concentration risks, with the semiconductor industry accounting for more than 95 per cent of revenue in the first half of 2026.
Furthermore, its major customers generated 85 per cent of total revenue during this period, with a single client contributing 27.2 per cent.
While Metasurface is headquartered in Singapore, its operations are supported by production facilities located in both Singapore and Malaysia where it has a “large fleet of machinery and equipment”.
The prospectus also flagged regulatory exposures, notably a recent notice from the Department of Environment in Johor concerning scheduled waste management lapses at its Malaysian subsidiary. While the company’s legal adviser views the risk of the maximum penalty as remote, the lapses carry potential fines of up to RM13.5 million (US$3.3 million).
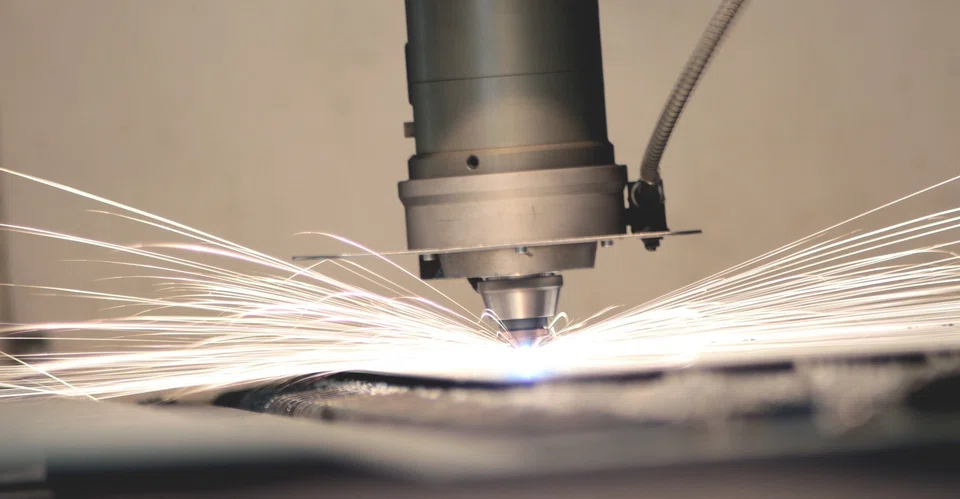
Metasurface’s services include machining processes for removing materials from a workpiece with high accuracy – in the range of hundreds of micrometres – and precision welding services that involve the application of weldment equipment and specialised welding techniques on a workpiece.
The company’s machinery is also capable of manufacturing large‑format vacuum chambers at a five-micrometre accuracy, placing its capabilities in an “advanced” category, it said, citing an independent market report.
MetaOptics impact
Metasurface recorded a revenue increase from S$37.7 million in 2024 to S$47.6 million in 2025, though its net profit fell from S$8.8 million in H1 2025 to S$3.7 million in H1 2026.
Ahead of the placement, its net asset value stood at S$0.466 per share, with an earnings per share of S$0.025 for the same six-month period.
Recently, its bottom line was significantly affected by a 12.9 per cent indirect interest in MetaOptics.
Metasurface recorded a S$6.4 million remeasurement gain in H1 2025 following reclassification of the MetaOptics stake to a financial asset. It subsequently recognised a S$13.9 million unrealised fair value loss in H1 2026 due to MetaOptics’ share price fluctuations.
Post-listing, the Metasurface board intends to recommend dividends of up to 30 per cent of net profit for FY2026 and FY2027.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

MAS allocates S$1.45 billion to five asset managers in third EQDP batch: Chee Hong Tat

‘My grandfather’s legacy’: Sherman Kwek lays out three-year plan for CDL to drive returns

‘How many will survive?’: Bubble fears arise as China’s humanoid robotics face reality check

CDL to hire dedicated CEO for fund management as it steps up push into private funds

