

Lippo Karawaci CEO wants LMIRT to own more non-Lippo assets
He also thinks that acquiring sponsor assets should be the "secondary purpose"
Singapore
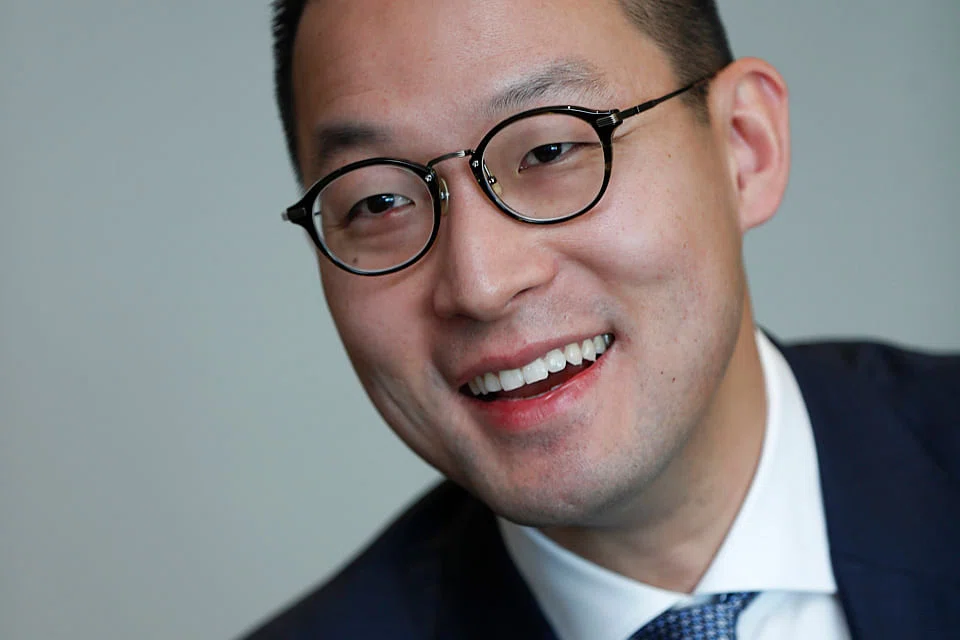
LIPPO Karawaci CEO John Riady wants what's best for the two real estate investment trusts (Reits) that his company sponsors, even if it means more third-party acquisitions and consolidation with other Reits.
"Consolidation in the Reit space in Singapore has been driven by the desire to scale. I think that's a good objective to the extent that there are opportunities that make sense for our Reits to consolidate," he said, referring also to the recent merger of OUE Commercial Reit and OUE Hospitality Trust.
"We are open to consolidation of our Reits as a way of building scale, but any successful consolidation will have to consider the respective Reits' strategy and rationale. That said, at this moment, there are no concrete plans around the consolidation of our Reits."
Lippo Karawaci and OUE, both entities of the Riady family, differ in the geographies they operate in: Indonesia and Singapore, respectively. They are helmed by two brothers, James and Stephen Riady, respectively. Lippo Karawaci sponsors First Reit (together with OUE Lippo Healthcare) and Lippo Malls Indonesia Retail Trust, while OUE sponsors OUE Commercial Reit and OUE Hospitality Trust.
On Lippo Karawaci's Reits, Mr Riady said: "I want to go with what's best for the Reits . . . Within the family, when you talk about merging, obviously scale is beneficial but it's also multi-dimensional. if you start merging a bunch of assets that don't fit together, it also doesn't make sense."
He does have hopes however that the managers of its two Reits will not simply be reliant on sponsor assets, but also seek to grow via third-party acquisitions.
In March, Lippo Karawaci said it was selling Lippo Mall Puri in West Jakarta to LMIRT for 3.7 trillion rupiah (S$354.7 million). Mr Riady said the Reit is "the most natural home" for the cash-generating asset, given the more tax-efficient structure.
Last year, Lippo Karawaci also sold the manager of First Reit, Bowsprit Capital, to OUE and OUE Lippo Healthcare (OUELH) for S$99 million, as well as a 10.63 per cent stake in First Reit for S$103 million to OUELH.
Mr Riady said: "It's the same for the sale of First Reit units to OUELH. It's a natural home there . . .They will run it better, the cost of capital will come down, prices will go up, it's a win-win for all parties."
He added that the purpose of these asset divestments was also to raise money and consolidate Lippo Karawaci's balance sheet.
Despite the sale of First Reit's manager, Lippo Karawaci remains committed to inject assets into the trust "to the extent that it makes sense". "We are not closed off to the possibility," Mr Riady said.
While capital recycling through asset injections into Reits has allowed Lippo Karawaci to grow its portfolio of properties more quickly, Mr Riady still thinks that acquiring sponsor assets should be the "secondary purpose" for Reits.
"The way I look at LMIRT and First Reit today is: how can we do what is inherently best for the Reit as an independent real estate investment trust.
"I don't wake up and think primarily what assets I can sell to the Reit, but instead what actions the Reit needs to take to optimise the value of its portfolio, improve its performance and thereby lower its yield, to become a bonafide, well-run asset manager in and of itself, and only secondarily to be acquiring Lippo Karawaci's assets."
No doubt unitholders likely bought into the Reits because of their confidence in their sponsor backing and the promise of pipeline properties. "That's fair; that's always been the plan from the beginning, but my priority first and foremost is, how do I maximise or unlock and realise the value of these Reits themselves?
"One concrete way things may change is that over time, I hope LMIRT can have a quarter of its portfolio comprising non-Lippo Indonesian malls."
He declined to comment on First Reit, as Lippo Karawaci no longer owns First Reit's manager.
LMIRT unit prices in particular have rebounded in the past month following news of its sponsor's US$1.01 billion fundraising exercise and improved credit ratings.
Mr Riady said ultimately, what's best for the Reits in the long run will also be what's best for Lippo Karawaci.
"With a higher quality portfolio, (Reit) prices go up, yields come down. When we sell, or when the Reit acquires assets around Indonesia, including ours, they can afford to purchase higher quality assets as well, and we can in turn also sell at a higher valuation. So it's really win-win for everyone.
"But if the Reit is trading at 9-10 per cent dividend yield, it has to make yield-accretive acquisitions . . . You can't buy any good assets. Who will ever sell you assets for 9-10 per cent yield? Then you get into this backward spiral. For LMIRT, that's a cycle that needs to be broken."
Based on Bloomberg consensus forecasts, LMIRT and First Reit are currently trading at forward yields of about 11.4 per cent and 9 per cent, respectively.
READ MORE: New Lippo Karawaci CEO to improve management, governance
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Hwa Seng Builder, two China companies win S$1.2 billion Tuas Road Viaduct phase two contracts

Deal between tycoon friends sparks scrutiny of Philippine power sector

Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet

