

Mapletree Industrial Trust to divest up to S$600 million of North America assets, eyes Japan and Europe for growth
The divestments are expected to be carried out within the next 1 to 2 years
[SINGAPORE] Mapletree Industrial Trust (MIT) plans to divest S$500 million to S$600 million of assets in North America within the next one to two years, as it steps up efforts to recycle capital into higher-quality properties and expand into new markets.
“With over S$500 million divested and more divestments planned, this gives us a nice headroom for acquisitions,” said Lily Ler, CEO of the manager, at the earnings briefing on Wednesday (Apr 29).
She added that MIT continues to see opportunities in data centres and is looking to grow its footprint in Japan while exploring a first entry into Europe, as it becomes more selective on the US given its substantial existing exposure.
“Greater diversification and more exposure to hyperscale tenants would improve the resilience of MIT’s portfolio.”
On the potential acquisition of the remaining 50 per cent stake in its portfolio of 13 data centres from its joint venture with sponsor Mapletree Investments, Ler said it would depend on whether the sponsor is willing to divest.
She highlighted that the portfolio is of high quality, with more than 50 per cent hyperscale tenant exposure, which MIT would like to increase its exposure to.
A “large portion” of the sale target comprises vacant or near-vacant properties, alongside selected income-producing assets with limited long-term upside, such as those with low power capacity or weaker re-leasing prospects, said Ler.
San Diego, for instance, is not in “a key data centre market”, with divestment “definitely on the cards”, she added.
The five-storey building, which comprises data centre and office space, was valued at US$49.2 million as at end-March 2026. Its tenant, AT&T, accounts for about 2.5 per cent of MIT’s overall portfolio by gross rental income, with the lease expiring in May 2026.
Ler indicated that the trust would take a pragmatic approach to divestments, aiming to achieve at least book value but remaining open to selling below valuation if required by market conditions.
For properties not seen to be contributing to portfolio income, “it’s actually better for us to just take the hard decision and divest it so we can recycle it into something that is contributing to the portfolio”, she said.
MIT is in “slightly more advanced discussions” on some potential sales and expects to provide updates within the next six months.
While North America remains a key focus for divestments, Ler said the trust is also reviewing its local portfolio for further opportunities, including properties with shorter remaining lease tenures such as Kallang 1 and 2, which have about five years left on their leases.
Selling such assets would help preserve capital value, she said, adding that the trust is also engaging JTC to explore the possibility of tenure extensions, including by securing tenants that align with government priorities.
In financial year 2026, MIT completed S$550.6 million of divestments, including the sale of the Georgia data centre for US$11.8 million at an 18.6 per cent premium over market valuation.
It also sold two business park buildings and one hi-tech building in Singapore in August 2025 for S$535.3 million, at a 2.6 per cent premium over market valuation and 22.1 per cent above the original investment cost.
FY2026 earnings
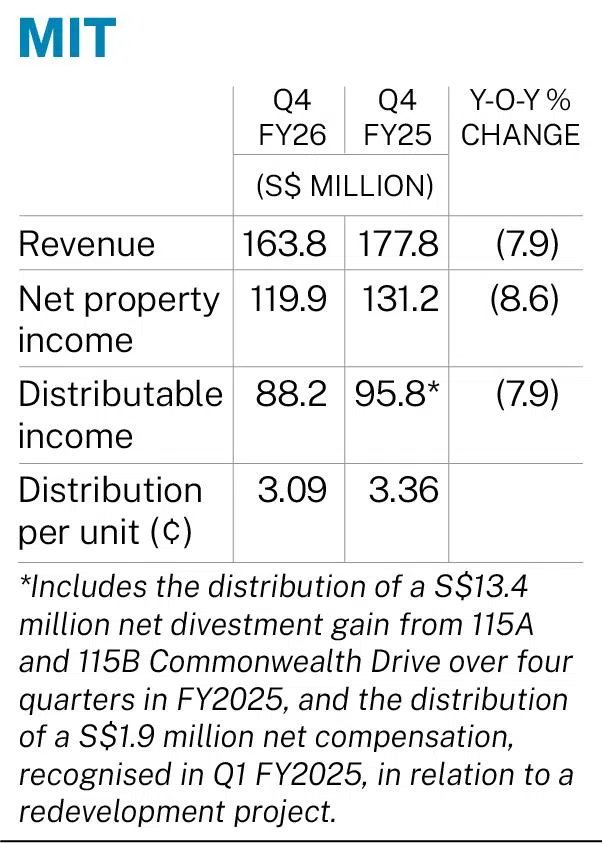
The manager posted a distribution per unit (DPU) of S$0.0309 for its fourth quarter ended Mar 31, down 8 per cent from S$0.0336 in the year-ago period.
Distributable income fell 7.9 per cent on the year to S$88.2 million in Q4. Revenue was down 7.9 per cent at S$163.8 million, and net property income declined 8.6 per cent to S$119.9 million in Q4.
For FY2026, revenue fell 5.5 per cent year on year to S$673 million, and net property income was down 5.9 per cent at S$500.4 million.
The weaker performance was driven mainly by the absence of income from the sale of the three Singapore assets, non-renewal of North American leases, and currency headwinds from the US dollar and yen.
Distributable income was down 6.1 per cent on year at S$362.6 million and DPU fell 6.3 per cent to S$0.1271.
The manager highlighted several upcoming headwinds, including the “confirmed non-renewal of leases” in its North American portfolio in FY2027, and “higher borrowing costs from the repricing of maturing interest rate swaps”.
Geopolitical tensions and inflationary pressures on operating costs also remain key concerns, it added.
Units of MIT were trading 3.9 per cent or S$0.08 lower at S$1.98, as at 12.43 pm on Wednesday.
TRENDING NOW

Prima to move out of historic Keppel Road flour mill building in 2028
Temasek-related Azalea, SeaTown, Seviora Capital to merge in 2027
Family offices see more tailored products, leverage ‘collective firepower’ for direct deal access
Singapore room rates soar, but hotels seeing mixed demand from F1 race and events

