

OCBC initiates EGP Energy with ‘buy’, target price of S$1.05
Fair value estimate implies a 43% upside from the stock’s last closing price of S$0.73
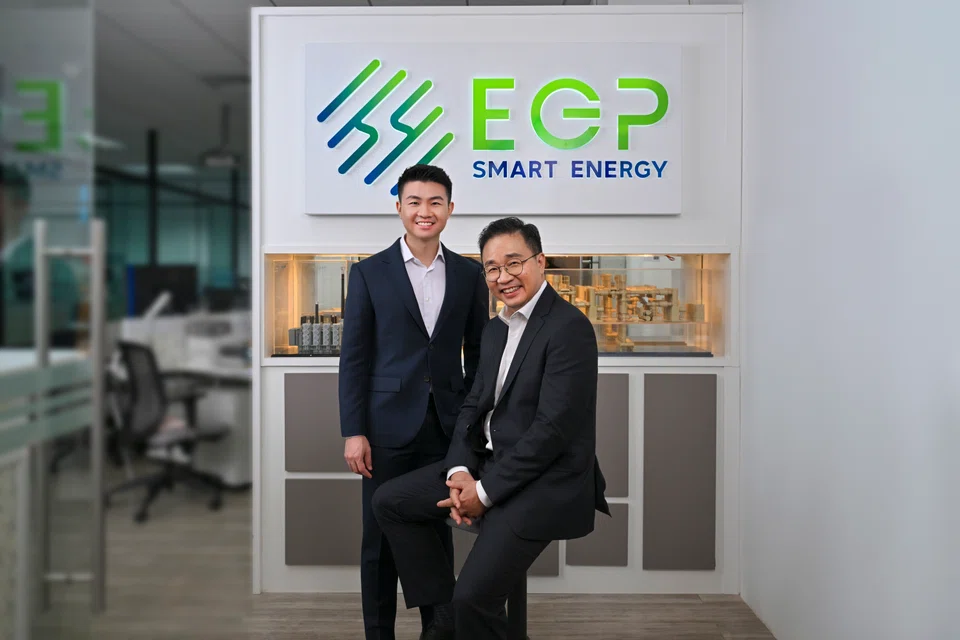
[SINGAPORE] OCBC Group Research has initiated coverage on EGP Energy Corporation with a “buy” rating and a fair value estimate of S$1.05, implying a 43 per cent upside from the stock’s last closing price of S$0.73.
In a report on Monday (Oct 5), equity research analyst Heidi Mo described the company as “Singapore’s best-performing IPO year to date” and the Republic’s “leading independent power transmission & distribution engineering, procurement, and construction specialist”.
OCBC said the firm’s market leadership is backed by regulatory moat, as EGP holds a 37.5 per cent share of the extra high voltage and high voltage switchgear market.
It is also supported by a Building and Construction Authority’s certification which allows a company to take on public electrical projects of any size and value without restrictions. 16 firms in Singapore have earned this accreditation.
The research house is upbeat on the company’s robust order book of S$296.2 million – equivalent to 4.8 times its FY25 revenue – with 65 per cent of these contracts projected to be recognised between the second half of 2026 and 2028.
Mo said that a 30-year relationship with its key utility customer, Singapore’s national grid operator, provides “legislatively mandated capex visibility through 2030”.
This pipeline is further underpinned by national structural tailwinds, as Singapore’s Power Transmission and Distribution System market grew at a compounded annual growth rate of 56 per cent from S$585 million in 2022 to S$2.24 billion in 2025. The figure is expected to reach S$2.79 billion by 2030.
OCBC forecasts EGP Energy to deliver an estimate core earnings before interest, taxes, depreciation and amortisation margin of 24.4 per cent in FY26, over the regional peer average of 11.5 per cent.
This outperformance is largely driven by its asset-light model that avoids the “heavy capex and working capital drag typical of manufacturing competitors”, OCBC said.
Furthermore, Mo noted that its maintenance and services segment offers a steady stream of recurring revenue, having generated average gross margins of 50 per cent over the FY23 to FY25 period.
OCBC’s S$1.05 target price implies a 16.5 times target price-to-earnings (P/E) multiple on its FY27E earnings, which factors in a 20 per cent discount to regional peers.
Mo said that at its current trading levels, EGP Energy is valued at 11 times FY27E P/E, marking a 46 per cent discount to its regional peer average of 20.3 times.
She added “given EGP’s superior profitability metrics, we are of the view that this discount is unjustified”.
Looking ahead, OCBC sees regional expansion as a key medium-term growth catalyst.
A recently announced 60:40 joint venture in Malaysia with Kum Fatt Engineering positions the company to tap Tenaga Nasional’s RM14.3 billion (US$3.5 billion) annual capex allocation through 2027.
The company offers “strategic flexibility for regional M&A and geographic expansion without dilution”, while comfortably sustaining a dividend payout ratio of up to 40 per cent, OCBC said.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

8 public officers referred to police over property buys near unannounced MRT stations: Chan Chun Sing

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Retrenched PMETs who return on lower pay see median 25% wage cut
Hao Mart owner resisting OG’s mortgage foreclosure on his Tanglin GCB

