Positive pivot or premature? Analysts split on Keppel Reit’s S$610.9 million buy
RHB cuts target price for the Reit to S$0.90; OCBC trims to S$0.95
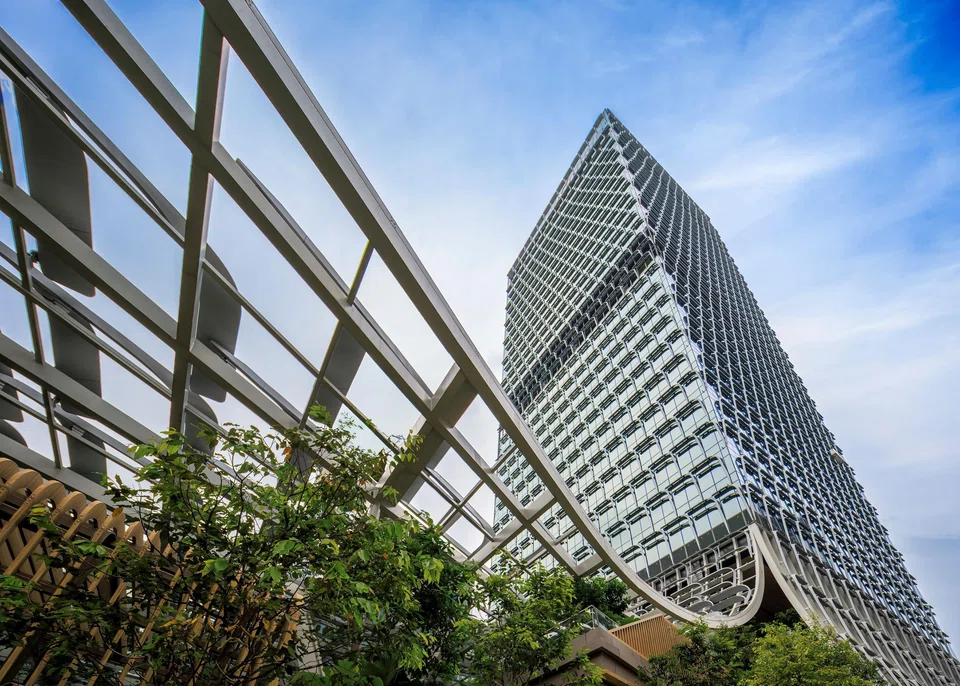
[SINGAPORE] Keppel Real Estate Investment Trust’s (Reit) proposed S$610.9 million acquisition of 51 per cent of Keppel South Central has drawn mixed reactions from research houses.
The redeployment of capital into Singapore, largely seen as positive, has been weighed by analysts against concerns over early stage leasing and potential equity fundraising.
Keppel Reit’s manager announced on Tuesday (Oct 20) that it proposed to acquire a 51 per cent interest in the newly completed 33-storey Grade A commercial development in Tanjong Pagar from sponsor Keppel. The agreed property value of S$626.2 million for the 51 per cent stake values the asset at about S$2,350 per square foot, based on net lettable area.
RHB on Tuesday maintained a “neutral” call while cutting its target price to S$0.90 from S$0.99. Analyst Vijay Natarajan said the timing of the acquisition came as “a bit of a surprise”, given that the property is still in its early stages of leasing.
“Potential equity fundraising plans will likely be a near-term share price overhang,” he said, adding that RHB raised its cost of equity assumptions by 50 basis points (bps) to reflect a more hawkish interest rate outlook.
Funding uncertainties
About 60 per cent of the acquisition is expected to be funded by a combination of internal cash and borrowings, with 25 per cent coming from perpetual securities and 15 per cent from an equity placement.
OCBC Group Research on Tuesday kept its “buy” call but trimmed its fair value estimate to S$0.95 from S$1.03, after raising its risk-free rate assumption to 2.65 per cent from 2.25 per cent.
Analyst Andy Wong noted that while the transaction is expected to deliver a 2 per cent pro-forma distribution per unit (DPU) accretion for the 2025 financial year, uncertainties remain around the deal’s financing structure.
A potential future equity fundraising and any increase in debt costs of 30 to 40 bps could erode DPU accretion, he warned.
Jefferies on Tuesday kept a “hold” call with an unchanged target price of S$0.85. Analysts Wilson Ng and Geraldine Wong said that while they favour recycling capital into a higher-yielding Singapore asset, the potential equity fundraising creates near-term overhang.
Meanwhile, the income support structure raises questions about the asset’s underlying earnings yield before full stabilisation, they added.
Room for earnings outperformance
On the other hand, DBS Group Research on Tuesday maintained a “buy” call and target price of S$1, describing the deal as a “positive pivot to Singapore, its core market”.
Analyst Dale Lai noted that the transaction allows Keppel Reit to quickly redeploy proceeds from recent divestments in Japan and South Korea into a prime Singapore Central Business District office asset where forward rent growth and demand remain robust.
To cushion the asset’s current committed occupancy of around 60 per cent, Keppel will provide a five-year income support deed guaranteeing a minimum net property income (NPI) contribution of S$2.23 million a month. This translates into an initial NPI yield of about 4.3 per cent.
Lai pointed out that committed average rents of S$11.30 to S$11.50 per square foot (psf) per month are already running ahead of the S$11.15 psf rental assumption underpinning the income support. This implies room for earnings outperformance as occupancy improves towards the 95 per cent target, he said.
On a pro-forma basis, Keppel Reit’s aggregate leverage is projected to be 39.2 per cent post-acquisition. The transaction is subject to unitholder approval at an extraordinary general meeting targeted for late 2026, with deal completion expected in the second quarter of 2027.
CGS International analysts were positive on the deal and maintained an “add” call, but cut its target price from S$1.09 to S$0.945, driven by the expectation that interest rates may rise and lower the present value of future dividends.
“Valuations are attractive with minimum guaranteed NPI, and upside for rental rates and occupancy on strong fundamentals for the Singapore office space,” they said in a Wednesday note.
Units of Keppel Reit closed flat at S$0.785 on Wednesday.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.