

S-Reits could lose out from family office investment scheme exclusion
Some industry observers say the move would divert capital away from the sector and disadvantage mid to small-cap Singapore-listed Reits that are thinly traded
[SINGAPORE] Industry watchers say the exclusion of Singapore-listed real estate investment trusts (S-Reits) and business trusts from an initiative to invigorate the equities market through family offices is “disappointing”, and could see struggling small and mid-cap Reits miss out on a much-needed liquidity boost.
The Monetary Authority of Singapore (MAS) last month announced adjustments to the Global Investor Programme (GIP) – which grants permanent residency to eligible foreign investors – among other moves to boost the Singapore equities market.
New applicants under the “family office” option of the GIP must now allocate at least S$50 million of their assets under management to equities listed on Singapore-approved exchanges.
Surprisingly, these approved equities exclude Reits and business trusts.
Previously, this capital could be spread across equities, Reits, private equity in Singapore-based businesses, and other asset classes.
Derek Tan, head of regional property research at DBS Group Research, said the boost would have provided Reits with an avenue to trade at better valuations, and “move back into a virtuous growth cycle”.
However, at least one observer felt that S-Reits, which raised around S$2.8 billion in equity last year, do not need further support from the authorities.
“We think (the Reit sector) already has an entrenched ecosystem of investors, bankers, and research coverage to support its own development,” said Liu Miao Miao, a senior research analyst at Phillip Securities Research.
Nevertheless, she acknowledged that family offices which prefer the stable dividends offered by Reits may be disadvantaged by the exclusion.
From 2020 to 2023, about 30 single family office owners were supported under the GIP.
Small and mid-cap S-Reits need liquidity
Industry observers said that the exclusion is likely intended to provide support for small and mid-cap companies in the broader equity market besides S-Reits.
This is especially so given that the S-Reit sector is “doing well” in Singapore, said Xavier Lee, an equity analyst at Morningstar. He noted that S-Reits make up 20 per cent of trading volume despite taking up 10 per cent of the total market cap of listed securities on the local bourse.
Nevertheless, Lee said the exclusion was “definitely disappointing” as it would divert capital away from investing into S-Reits.
Similarly, Tan of DBS Group Research said he was surprised by the exclusion. He felt that S-Reits should be considered in the application criteria as there are also mid to small-cap S-Reits that are thinly traded. These Reits can benefit from an influx of new capital, said Tan.
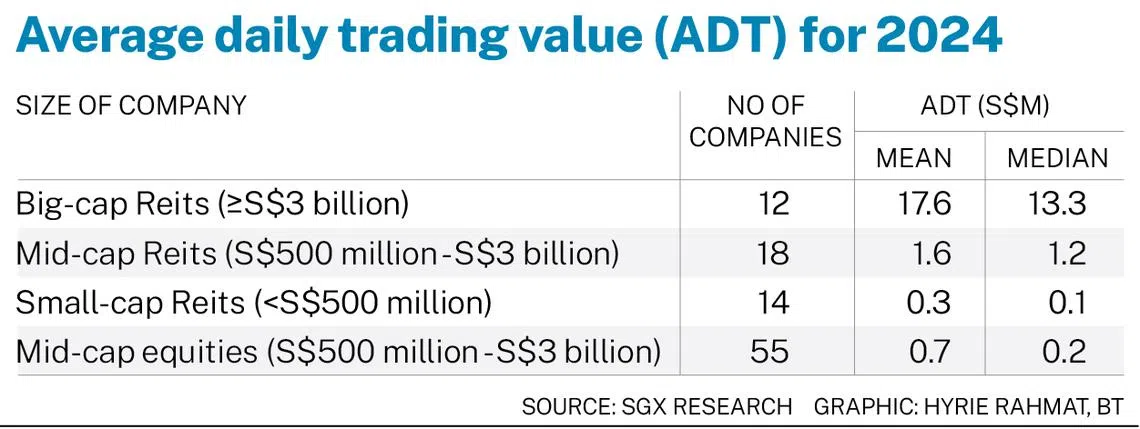
According to data from the Singapore Exchange (SGX), mid-cap Reits and business trusts with a market capitalisation of between S$500 million and S$3 billion posted an average daily trading value of S$1.6 million for 2024. This figure is more than double that of mid-cap listed companies (excluding Reits), which posted an average daily trading value of S$0.7 million for the same period.
On the other hand, the average daily trading value for mid-cap Reits trailed behind that of their big-cap counterparts for 2024. The latter, which refers to those with a market cap of at least S$3 billion, posted an average daily trading value of S$17.6 million in 2024.
In an interview with the media on Feb 28, Ng Yao Loong, the head of equities at SGX Group, said that the GIP’s focus is on listed companies’ shares as S-Reits and business trusts are “relatively okay” and not all of them suffer from a lack of liquidity.
Ng, who is also on the review committee, added that the team would consider industry feedback on the first round of proposals announced in February this year.
Ensure high-quality Reit listings
Apart from changes to the GIP application criteria, the MAS market review committee announced several other proposed changes to boost the local market. They include a S$5 billion investment initiative for asset managers with a “strong investment track record” and a focus on Singapore-listed equities.
Morningstar’s Lee said that it is difficult to tell if the other proposals by the market review committee will be enough to support the S-Reit market in Singapore.
He said that the key challenge for SGX is to ensure a continued pipeline of high-quality Reit listings, given that most of the top-quality assets in Singapore have already been injected into a Reit.
“Without this pipeline, SGX may find it hard to continue to grow its Reit market,” said Lee.
However, Liu reiterated her stance that the S-Reit market requires no further support.
Said Liu: “This sector is developed enough to access equity capital without the assistance of government funds. It already has tax privileges.”






