

Sembcorp closes down 2.8% after Indonesia cuts gas exports
The decline comes as Singapore braces for energy supply disruptions following Indonesia’s curb
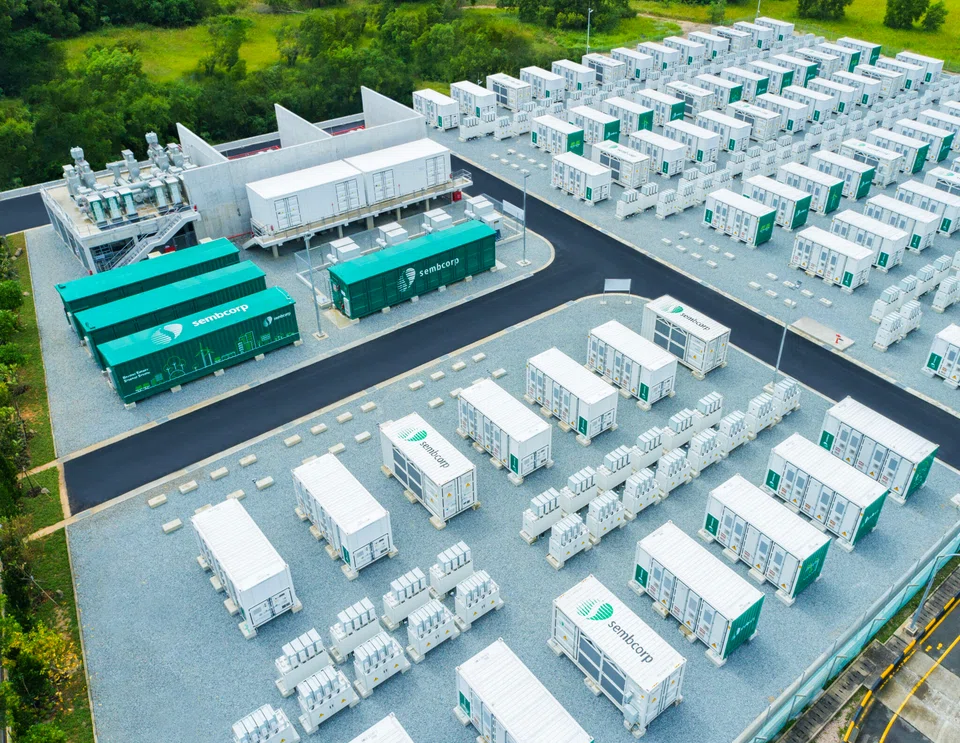
[SINGAPORE] Shares of energy and urban solutions provider Sembcorp Industries fell sharply in early trading on Monday (Oct 26), shedding over 5 per cent from their opening price.
As at 9.20 am on Monday, Sembcorp was trading at S$5.71, down S$0.30 or 5 per cent from its previous close, according to ShareInvestor. Some 2.3 million shares had changed hands. This was the lowest the stock has been trading since August.
As at 10.45 am, the counter pared some losses, and was S$0.20 or 3.3 per cent lower at S$5.81. As at noon, the stock was down S$0.17 or 2.8 per cent at S$5.84.
The counter closed at S$5.84 on Monday, down 2.8 per cent or S$0.17, with about 9.1 million shares changing hands.
Monday’s decline came shortly after Minister for Energy, Trade and Industry (Energy and Industry) Tan See Leng said that Singapore will have to brace for greater risk of energy supply disruptions.
His comments came as Indonesia began cutting natural gas exports to Singapore on Oct 24. Sembcorp is an importer of natural piped gas from Indonesia.
Sembcorp imports piped natural gas from Indonesia’s West Natuna region, making it more exposed to the cuts said DBS Group Research in a Monday report.
However, the brokerage noted that Sembcorp has long-term contracts with mechanisms allowing gas costs to be passed on to customers, as well as hedging arrangements to mitigate fluctuations in gas prices.
While the supply reductions were manageable in the near term, further cuts and higher replacement gas costs could put pressure on power generation margins, DBS cautioned.
Macquarie Equity Research, however, expects Sembcorp to benefit over the longer term from higher electricity generation margins, even as concerns over the supply disruption weigh on investor sentiment initially.
In a Monday report, analyst Foo Zhiwei said tighter gas supplies could widen spark spreads – the difference between electricity prices and gas generation costs – although the increase would likely be smaller than during the 2021 gas supply disruptions.
Macquarie expects Sembcorp to be a greater beneficiary of higher spark spreads than Keppel, given its exposure to the Singapore power market. It maintained its “neutral” rating and S$6.39 target price.
Meanwhile, Citi analyst Luis Hilado warned that a significant reduction in piped gas supplies could temporarily squeeze Sembcorp’s margins if it has to purchase more expensive liquefied natural gas (LNG) to fulfil existing customer contracts.
However, Citi noted that Sembcorp has diversified its gas supply portfolio, including long-term LNG agreements with TotalEnergies and Shell, reducing the risk of a major supply disruption.
The brokerage added that higher LNG procurement costs could eventually be reflected in Singapore’s wholesale electricity prices, potentially passing some of the burden on to consumers.
Citi maintained its “buy” rating and S$6.92 target price.
Sembcorp reported a 72 per cent year-on-year decline in net profit to S$150 million for the first half ended June 2026, weighed down by one-off costs related to its acquisition of Australian energy provider Alinta Energy and weaker contributions from its core businesses.
For H1 FY2026, the group reported a 25 per cent year-on-year drop in underlying net profit to S$369 million, although it raised its interim dividend to S$0.11 per share from S$0.09 a year earlier.
The group said it expects a stronger performance in the second half of 2026, supported by a full six-month contribution from Alinta, higher land sales and improved earnings from its gas business.
However, Sembcorp cautioned that its renewables business would continue to face headwinds, including weaker wind and solar resources and lower tariffs in China.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

Government to bring forward raising of retirement age, give employers more financial support to create flexi-load jobs

Former minister Maliki Osman, Revolut chairman join Asia Gulf Holdings advisory board

Is Manila Asia’s new dining hot spot?
Simba at risk of losing operating licence over spectrum misuse

