

Baltic Exchange Shipping Insights
A roundup of last week's tanker and dry bulk market
TANKER REPORT
VLCC
A steady week in the Middle East Gulf saw rates at WS 90 for 270,000mt to China. Going west, 280,000mt to the US Gulf was assessed in the low WS 40s Cape/Cape. West Africa to China basis 260,000mt fixed at WS 89.5 up 3.5 points over the week. US Gulf to China went at $8.65 million, while $9 million failed ex US Gulf, but agreed from Covenas.
Suezmax
West Africa firmed 25 points, with WS 145 paid for 130,000mt to UKCont. Black Sea/Mediterranean rates were steady at WS 172.5-175 for 135,000mt with West Coast India agreed at $3.75 million.
Aframax

Rates for 80,000mt in the Mediterranean firmed 17.5 points, with Statoil fixing from Ceyhan at WS 165; Libya load went at WS 170. Increased delays in the Turkish Straits saw Black Sea rates gain 25 points to WS 172.5/175.
Baltic rates for 100,000mt rose to WS 97.5 from WS 90. In the 80,000mt cross North Sea trade, WS 130 was fixed from Sture, up 12.5 points.
In the Caribbean, rates lost 65 points, with the market now in the low WS 170s, for 70,000mt from Venezuela to US Gulf.
Clean
Status quo was maintained, with the 75,000mt Middle East Gulf/Japan market close to WS 120, with 55,000mt steady at WS 127.5/130.
A busy week Continent/Baltic saw the tonnage list thin and rates marginally firmer at WS 142.5/145 for 37,000mt Continent/USAC.
The 38,000mt backhaul trade from the US Gulf enjoyed another positive week gaining 17.5 points to WS 152.5.
DRY REPORT
Capesize
It was a positive end to the week, with West Australia/China making significant gains and firing owners' resolve.
There was talk that one of the majors paid $7.00 for 7-9 December cargo on Friday, with rates gaining 85 cents in a few hours.
Timecharter activity so far remained negligible, but rates are assessed now at five figures. Brazil/China trading was spasmodic, but rates fixed were over $15.00.
However, brokers said some bids were up today and owners also increased their rate ideas with the bid-offer gap widening significantly.
Further north, there was some fronthaul business from St. Lawrence to China and voyage rates had been hovering in the upper teens, with timecharter rates in the very low $20,000s.
Those numbers were again expected to move to at least $1,000 or so.
Transatlantic trading was slow, but a Puerto Bolivar/Rotterdam cargo went on a 2007 built vessel from Gibraltar at $13,000 daily, reportedly equating to $8.25. Sources also suggested more cargo was evident in the market, lending some support.
Panamax
It seemed a new level of support from South America was found last week, after rates had tumbled the previous week.
Modern Kamsarmaxes continued to fix at $14,500/$14,750 plus $450,000/$475,000 ballast bonus for trips to the East.
Levels in the North Atlantic eased for the very early ships as they sought cover, however, the tonnage profile remained tight, with later ships more bullish.
Pacific rates continued to be eroded with short Indonesian trades very prevalent as many decided to buy some time.
However, several early ships had been forced to agree aps deliveries.
There appeared to be more Panamax types in the market last week, said to be due to a slow-down in Chinese coal demand, and whilst period rates are at a significant premium to spot rates now, there was few trades in evidence.
Supramax
Despite stronger rates being achieved from the US Gulf and East Mediterranean, the week saw overall losses on the BSI, with the Asian market suffering most.
There was however limited period activity and a 63,000dwt fixed delivery US Gulf, for a short period redelivery Singapore-Japan, at $18,000.
The Atlantic remained firm from the US Gulf, with a 63,900dwt fixed from here to West Coast Central America at $27,500.
Levels remained firm for prompt positions in the Mediterranean and a 57,000dwt was booked for a trip to the US East Coast, via Egypt, in the mid-teens.
A 60,500dwt fixed a trip delivery Canakkale via the Black Sea, redelivery Indonesia, at $27,000. Other areas traded sideways brokers said.
The Asian market stalled this week with a build-up of tonnage. Nickel ore shipments were still in evidence, a 56,000dwt fixed delivery CJK trip, via the Philippines, redelivery China.
North Pacific business saw a 57,000dwt fixing delivery Ishinomaki with redelivery South East Asia at $10,000.
Handysize
It was another week of continuous falls in both the Atlantic and Asian basins, with negative sentiment evident in all major trading areas.
Brokers suggested most of the cargoes from East Coast South America were for December, and the market had been expected to show some recovery this month.
However, brokers have now suggested they anticipate some improvement by year end.
Activity slowed down from the US with the Thanksgiving holidays at the end of the week, whilst in the East, there were fewer cargoes and rates also fell further.
A 33,000dwt open Rouen was booked to move wheat to Algeria at $13,250.
A 35,000dwt pen Tuzla was fixed for a trip with grain, via the Black Sea, to the Egyptian Mediterranean in the mid-high $14,000s.
A 37,000dwt agreed $17,000 from the US Gulf for a run to Ireland at $17,000.
In the Pacific, a 36,000dwt open North China was fixed for a trip with steel to Vietnam at a rate in the low $7,000s.
FREIGHTOS BALTIC CONTAINER REPORT
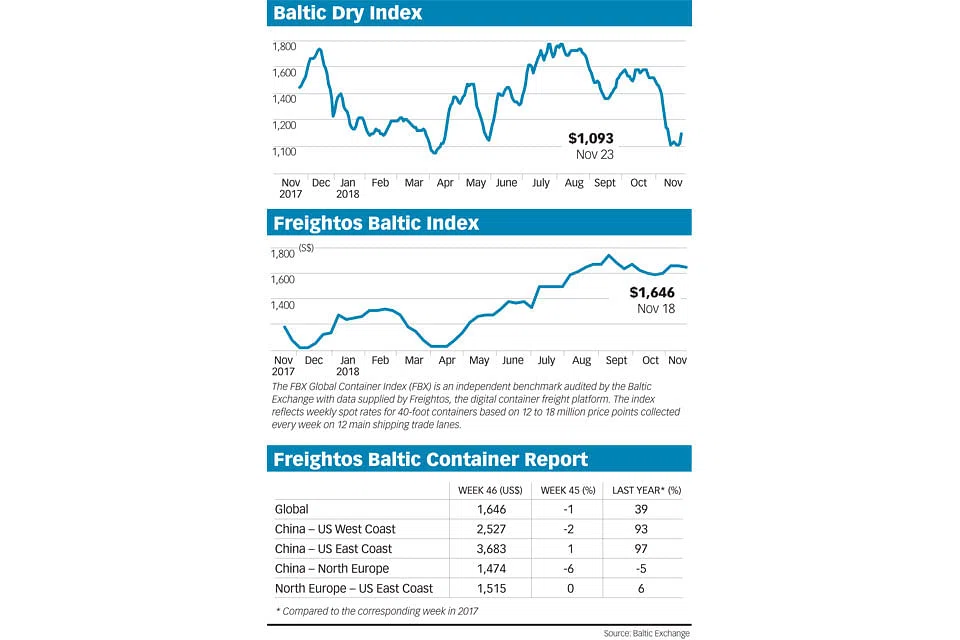
With continuing uncertainty over a potential escalation of trade tariffs on Chinese imports, the midmonth General Rate Increase (GRI) round barely influenced transpacific prices.
China-East Coast prices rose by just 1% and West Coast prices actually dropped.
Peak season is over for the China-Europe lane. This week's $1,474 is a mere 67% of where prices were just ten weeks ago ($ 2,201 on 9 September). 2M resuming the AE2/Swan Asia-North Europe loop next month should see prices drop further.
The mid-month GRI was a dud, with China-East Coast average prices rising by just $41. On the China-West Coast lane, where carriers have been more active in temporarily increasing supply, prices actually fell. Carriers have announced further GRIs for 1 December and 15 December.
Despite that, China-West Coast prices were above the $2,000 mark for the 15th week in a row. The last time it breached this mark was the week before Chinese New Year in 2017. Similarly, the China-East Coast prices breached the $3,000 mark for the 16th straight week.
Continuing high transpacific ocean prices reflects increased demand. Less Container Load (LCL) and Full Container Load (FCL) bookings on Freightos went up 40% and 42%, respectively in October, a marked contrast to last year when there was no increase at all.
China/North Asia to North America West Coast prices rose soon after the first trade tariff was announced in June and have stayed high since.
This is in stark contrast to last year, when, without anything to spur demand, chronic overcapacity saw prices falling most weeks from late August onward.
The Freightos Baltic Indices reflect weekly spot rates for 40-foot containers based on 12 to 18 million price points collected every week on 12 main shipping trade lanes.
The data includes a headline index - the FBX Global Container Index (FBX) - a weighted average of the 12 underlying route indexes. This data is published every Sunday.
See www.balticexchange.com/market-information/containers
The Baltic Exchange, a wholly-owned subsidiary of Singapore Exchange, is the world's only independent source of maritime market information for the trading and settlement of physical and derivative contracts.
Its international community of over 650 members encompasses the majority of world shipping interests and commits to a code of business conduct overseen by the Baltic.
For daily freight market reports and assessments, please visit www.balticexchange.com.
Share with us your feedback on BT's products and services
TRENDING NOW

Peter Kwee’s Ridley Park bungalow on the market with S$100 million asking price

Motoring tycoon Peter Kwee is back in court: Here are his previous legal battles

Demand, tech capabilities position Apac and AI as Skyscanner’s next growth frontiers: CEO Bryan Batista

South-east Asia has lost Nvidia’s best salesman

