

UOBKH downgrades SIA to ‘sell’ as jet fuel price nears all-time high
Brokerage is ‘largely neutral’ on Air India’s US$1.5 billion top-up request
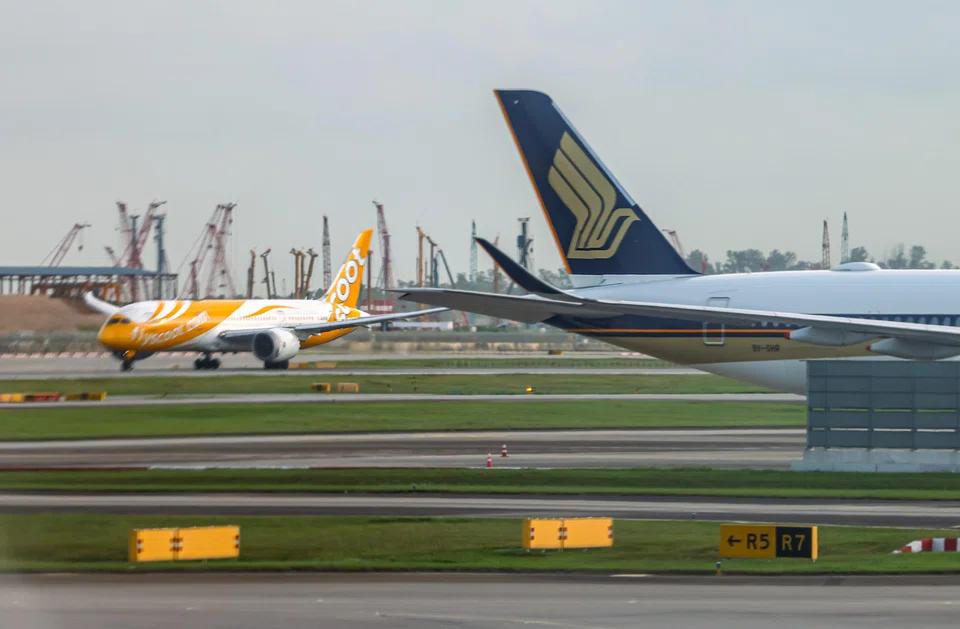
[SINGAPORE] UOB Kay Hian (UOBKH) has downgraded Singapore Airlines (SIA) to a “sell” after a re-escalation in Middle East tensions on Monday (Sep 14) sent jet fuel prices rising.
Drone attacks on Monday by the Iran-backed Houthis knocked out a key Saudi Arabia pipeline bypassing the closed Strait of Hormuz, while planned talks between Gulf Arab states and Iran were postponed.
Brent and US crude oil prices were respectively at about US$105 and US$101 a barrel on Friday. Jet fuel rose to US$190 a barrel as at Tuesday, nearing the highs of US$200 a barrel in April, and about 58 per cent higher than the US$120 a barrel price in late June.
In response, UOBKH slashed the 2027 and 2028 earnings forecasts for SIA by 21 per cent to S$831 million and by 5 per cent to S$961 million, respectively. The stock’s price target was reduced to S$6.16, from a previous target of S$6.71.
The brokerage also cut SIA’s net profit guidance for the second quarter of the 2027 financial year to between S$230 million and S$370 million, from between S$240 million and S$460 million.
“While SIA’s 40 to 50 per cent fuel hedging position for the remainder of FY2027 should provide some protection relative to its regional peers, its earnings outlook remains exposed to further fuel-price volatility,” said analyst Roy Chen. “Jet fuel prices are likely to remain elevated in the near term, creating continued pressure on SIA’s profitability.”
The airline in July posted a net loss of S$76 million for its first quarter, down from a net profit of S$186 million in the previous corresponding period. Lower operating profit followed a 78.5 per cent spike in net fuel costs, sparked by the fighting in the Middle East and a higher share of losses from Air India.
The Air India factor
Air India, in which SIA holds a 25.1 per cent stake, is likely to face greater exposure to higher jet fuel prices and related operating disruptions given its closer proximity to the conflict-affected region, said UOBKH.
The Indian flag carrier has been buffeted by headwinds, with higher fuel prices, Pakistan airspace restrictions and the crash of flight 171 last year weighing on SIA’s profitability.
SEE ALSO
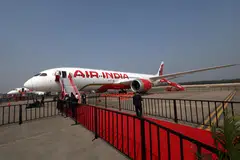
Air India is now seeking about US$1.5 billion in equity from its owners, reported Reuters, with SIA estimated to have been asked to provide about US$375 million.
Reuters in September also cited sources that SIA is expected to seek greater influence over management and stronger governance rights before approving a capital injection into Air India.
UOBKH said it was “largely neutral” on Air India’s equity top-up request, having weighed the upside opportunities in India against the uncertainties in the timeline for the Indian carrier’s turnaround.
It added that its updated forecast for SIA incorporates an estimated fuel-hedging gain of nearly S$400 million and an estimated net loss contribution of S$250 million from Air India.
“We like SIA for its strong operation track record and healthy balance sheet, but think it lacks near-term catalysts,” said the brokerage, recommending investors to wait for a “better entry point”.
Shares of SIA rose 0.5 per cent to close S$0.03 higher at S$6.51 on Thursday.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Fed hike throws Singapore banks a margin lifeline; UOB likely to benefit more

Luxury properties seized in S$3 billion money laundering case fail to sell at auction
US stocks: Tech leads Wall Street to higher close as oil eases, Treasury yields dip

