Outdated image, updated lessons for China brands in South-east Asia
AS CHINA’S brands enter South-east Asia, they strive to shed old stereotypes while banking on capabilities previously developed for the domestic market.
Overcoming the ‘outsourced vendor’ image
In the past, Chinese manufacturers were known primarily as original equipment manufacturers (OEMs) for international brands – a reputation that they could not shake off even after launching their own brands.
Back then, the “Made in China” label implied poor quality and copycat products, according to the Research Report of 2021 on Chinese Cross-Border Brands by China-based market consultancy LeadLeo Research Institute.
Said the report: “To shake off the stereotype of a low-end manufacturer, ‘Made in China’ at this stage will have to progress from shipping products to exporting Chinese brands with high added value, and moving up to the mid to high end in the global value chain.”
For years, price competitiveness was the key “Made in China” advantage. But analysts see this perception as a double-edged sword, and a potential obstacle when Chinese brands try to break into the premium segment.
EY-Parthenon Asean leader Joongshik Wang explained: “For some time, Chinese consumer brands have positioned themselves as value-for-money products or services.”
“A key challenge that Chinese consumer brands face is a perception of lower quality, which can impede their ability to move up the value chain and price themselves differently, even with the emergence of higher-quality products in recent years.”
But he added that Chinese brands have a strong market position in technology – where they have proved able to produce quality products – and could continue to strengthen their presence there.
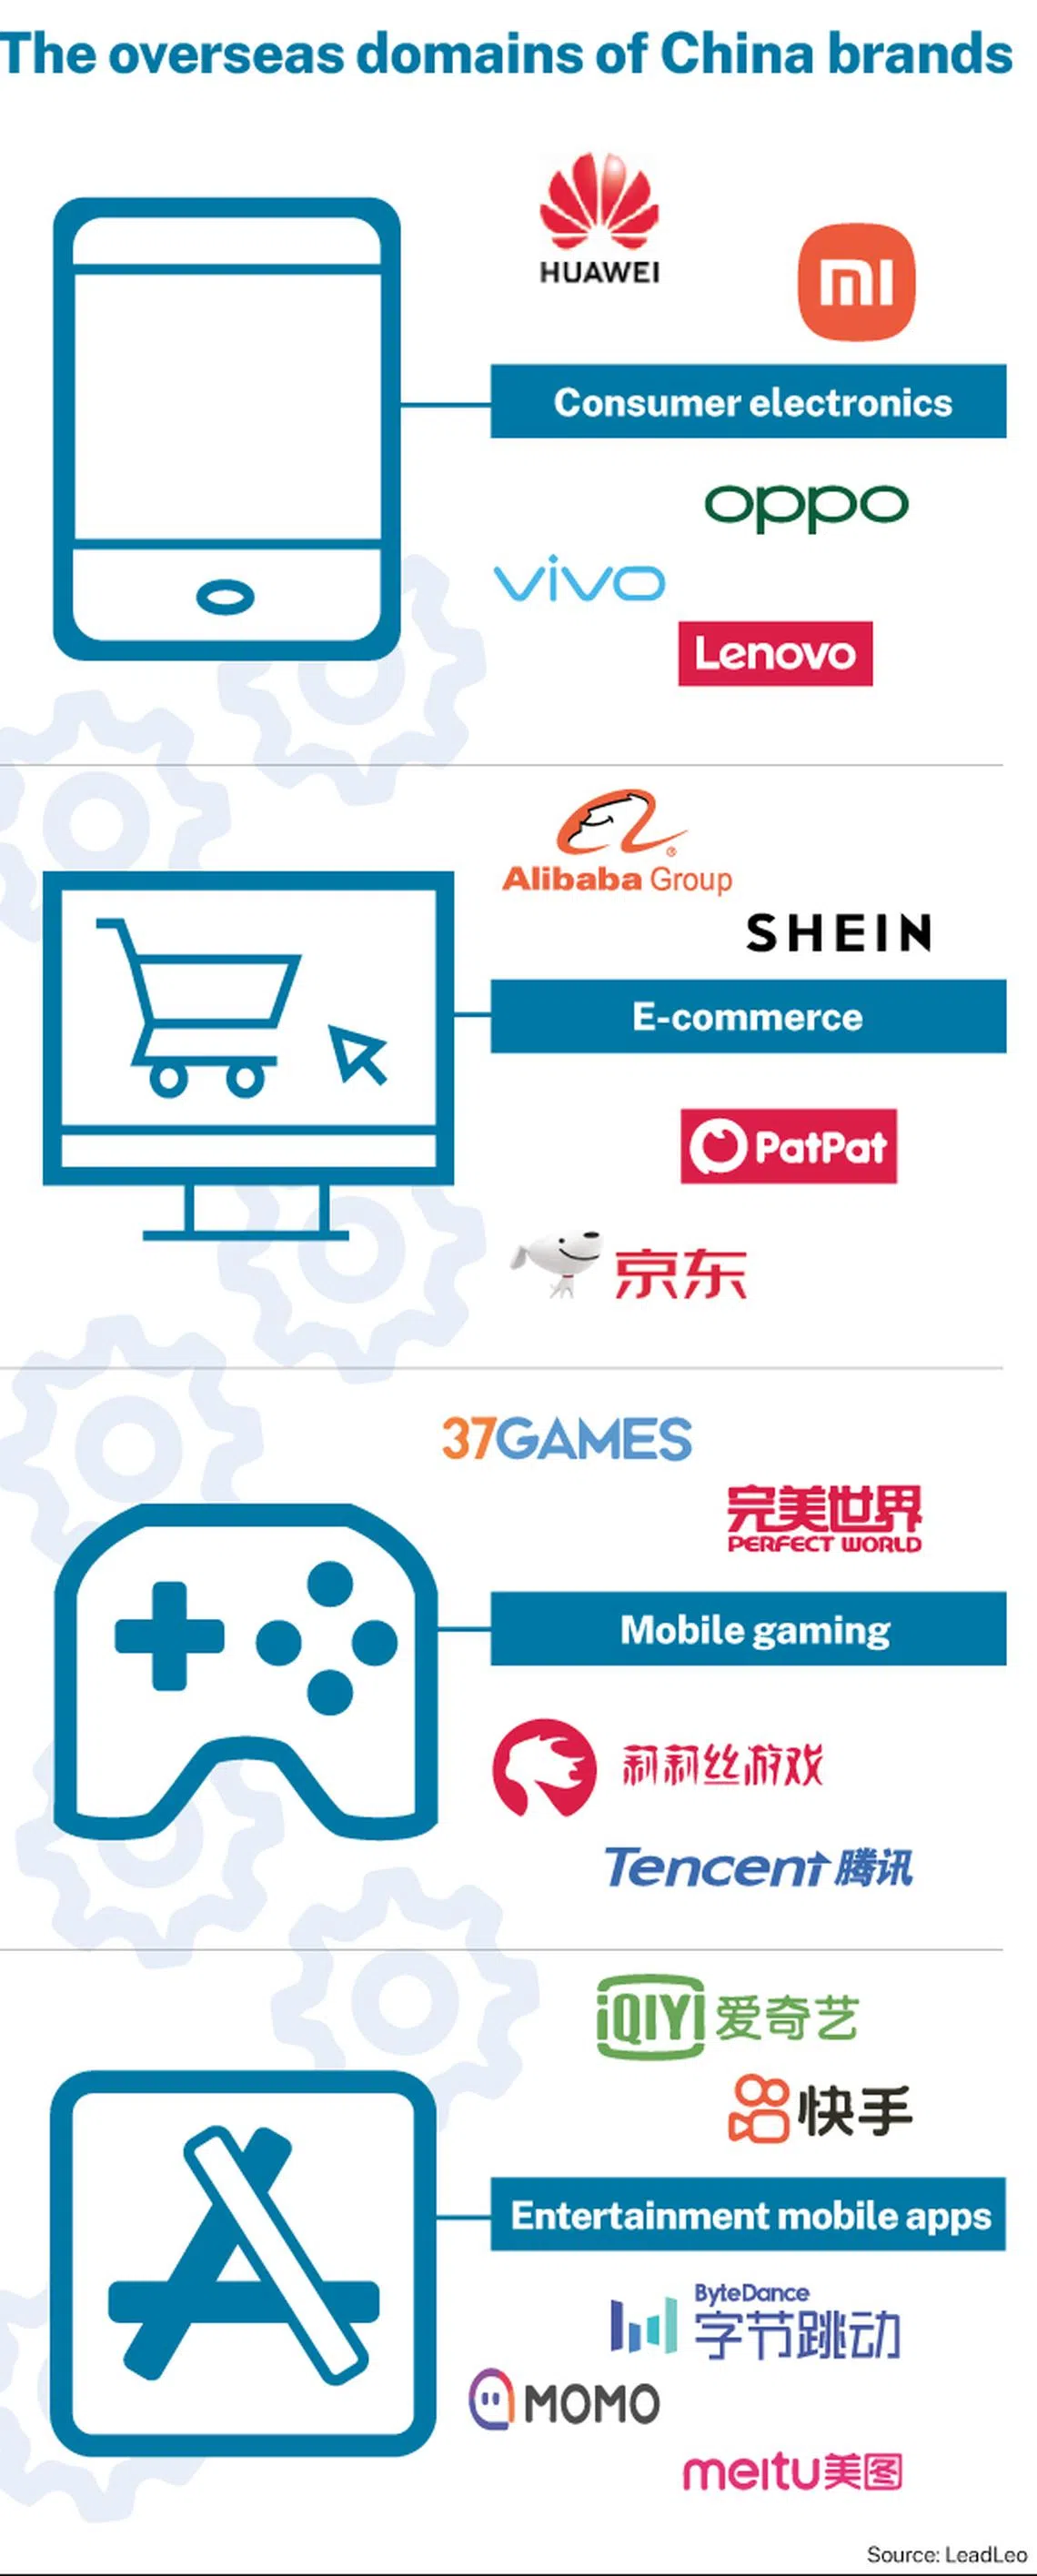
Consumer electronics, e-commerce, mobile gaming and entertainment apps are areas where Chinese brands have had a significant overseas presence in recent years.
In the Top 50 Kantar BrandZ Chinese Global Brand Builders 2021 report by market research firm Kantar and Google, China’s consumer electronics (33 per cent) and mobile gaming (15 per cent) had the largest share of “brand power”. Alibaba was the top global Chinese brand in the study, followed by ByteDance, Huawei, Xiaomi and Lenovo.
Taking domestic models overseas
The massive scale of their home market has allowed Chinese brands to draw lessons from domestic operations and replicate successful models overseas.
According to a LeadLeo report, as China’s demographic dividend dwindles and some sectors become saturated, some Chinese enterprises facing slowing revenue growth have chosen to venture abroad. These are homegrown brands with a significant market share at home.
From digital marketing to establishing a sales network, Chinese brands have been able to tweak existing business models and transplant them into South-east Asia to seize opportunities, observed KPMG China’s strategic consulting director He Ying and partner for strategy consulting, consumer and retail Willi Sun.
In addition, the established supply chains and well-developed infrastructure of these brands provide responsive support for overseas expansion, further enabling the swift development of localised products and services.
Celeste Tan, manager of Nanyang Polytechnic’s Singapore Institute of Retail Studies, noted that China is the world’s largest e-commerce market, with major domestic platforms – such as Alibaba’s Taobao and Tmall, and JD.com – also being well accepted across South-east Asia, especially in Singapore and Malaysia.
Regional e-commerce platforms such as Shopee and Lazada are active in adding Chinese sellers to their merchant pool too. Chinese brands can ease themselves into South-east Asia by using these platforms to test the receptivity of consumers, she said.
Online travel agency Trip.com Group is one of the consumer brands that ventured overseas with the rise of China, with Singapore as its first foreign base. The group established the “Trip.com” brand for the overseas market in 2017 and now has more than 600 employees across South-east Asia.
Trip.com’s chief operating officer Schubert Lou said: “Tourism in China is more sophisticated, and many elements are already integrated, such as online ticket purchase and QR code scanning to enter a park, etc.”
“These procedures are already the norm in China, but elsewhere you might still need to pick up the ticket and then go through another system for admission. This type of connectivity is worth learning from and promoting,” he added.
The group has a well-established platform in China with big data insights into user behaviour, providing a reference point for overseas expansion.
Trip.com is bullish about South-east Asia, citing its population size, younger demographic, and consumers’ willingness to go beyond established models and try out a one-stop travel agency.
Each market in the region has unique characteristics, noted Lou. For example, hotel staycations were popular among Singaporeans during the pandemic, but the concept was alien to Malaysians, Thais and Indonesians, who preferred domestic tourism. Differences across markets make it impossible to implement the same strategy across the region, with localisation thus being essential.
Localisation is a common South-east Asian strategy among Chinese brands. One example is smartphone maker Oppo’s marketing campaign in Singapore, where the brand worked with local Internet celebrities and producers to encourage young people to make short films with its phones. Another is Xiaomi’s practice of holding special events to thank its users in different markets.
Tan Chee Yun is a correspondent with Lianhe Zaobao Business News Desk. This article is part of a collaboration on a series of weekly features translated from the Chinese daily. The original story first appeared on July 17. The next package on Aug 1 will look at Vietnam’s post-pandemic emergence as an alternative to China's role as the factory of the world.