

Thai blue chips on the SGX: What you need to know
THREE Singapore depository receipts (SDRs) will commence trading on the Singapore Exchange (SGX) on May 30, allowing investors to trade in Thailand’s blue-chip names through beneficial interest.
Classified by SGX as excluded investment products, SDRs are suitable for investors who expect a low-to-moderate likelihood of loss on their principal investment amounts, with generally smaller potential returns.
For investors looking to increase their exposure to the Thai economy, this is what analysts are saying about the three companies:
CP All: An all-rounder
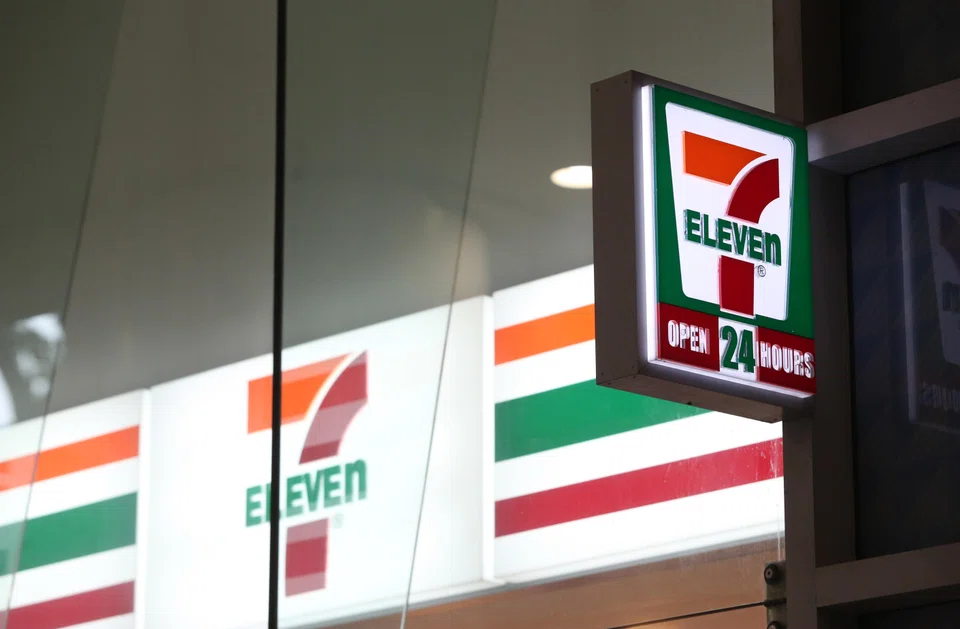
Of the three SET50 index constituents to be launched as SDRs, convenience store chain operator CP All appears to have the highest approval rating among analysts.
Bloomberg data as at Wednesday (May 24) showed that almost nine in 10 brokerages that cover the stock have a “buy” rating on it.
Most of them expect CP All’s strong earnings momentum to continue from its first quarter ended March. UOB Kay Hian (UOBKH) deems the stock as one of the biggest beneficiaries of the resumption of tourist arrivals and higher consumption in suburban areas.
DBS Group Research, Nomura Research, RHB and Maybank Securities cited other key drivers of earnings growth, including continued same-store sales growth (SSSG), a ramp-up of new stores, as well as easing finance costs amid CP All’s debt refinancing activities.
All five research houses recommend a “buy” on the counter, with their price targets ranging from 72 baht to 79 baht. Shares of CP All closed at 63.25 baht on Wednesday.
Aside from Thailand’s May general elections and lower electricity costs – which could further support SSSG – hot weather might also boost the group’s beverage sales in Q2, said DBS.
While CGS-CIMB agreed that net profit momentum from the convenience store segment will remain “robust”, it identified wholesale supermarket unit Siam Makro as a crucial earnings growth driver for CP All from Q2 FY2023.
This is because the research house expects the wholesaler to record lower interest expenses following the refinancing, which could in turn boost the group’s core net profit in the quarters ahead.
In January, RHB cautioned that Makro’s operating expenditure could remain high this year due to its online platform consolidation and wholesale store adjustments for its omnichannel business.
Nonetheless, its analyst said finance costs could peak in Q4 of the year before declining in H2 FY2023, as the subsidiary continues to refinance its US dollar-denominated loans.
Airports of Thailand: Concession boost
Roughly three-quarters of the analysts covering airport operator Airports of Thailand (AOT) recommend a “buy” on the stock, Bloomberg data showed.
Nomura is particularly bullish on the stock, which is viewed as a proxy for the recovery of Thailand’s tourism sector, and has set a price target of 87 baht. The stock closed at 70.75 baht on Wednesday.
The research house’s analysts expect the group to register record earnings in FY2024.
The stock is also RHB’s top pick within the Thai hospitality space, as the brokerage deems it a “first-tier proxy” for the tourism sector’s recovery.
Nomura analysts also predict that the expiry of the minimum annual guarantee waiver – in force from Feb 1, 2020, to Mar 31, 2023 as part of an industry-wide pandemic relief programme – will boost the group’s concession revenue. This would result in a turnaround of the group’s operating profit.
They expect “a more impactful positive operating leverage effect (on AOT’s) bottom line” in H2.
Meanwhile, DBS estimates the group’s non-aeronautical revenue to stand at 17.8 billion baht for FY2023, up 56 per cent year on year, as the end of Covid-19 relief measures provide a boost.
It said: “We expect AOT’s earnings to turn from heavy losses during the past three years to a net profit of 11.5 billion baht in FY2023, before surging 153 per cent to 29.1 billion baht in FY2024 – exceeding the pre-pandemic level.”
Besides the expiry of pandemic aid measures for airlines, CGS-CIMB also highlighted an improvement in inbound Chinese passenger numbers as a key driver of the group’s earnings per share recovery in H2.
The research house expects outbound capacity from China to rise to 70 per cent of pre-Covid levels over the April to October 2023 period, from just 30 per cent for the first three months of the year.
DBS and CGS-CIMB had price targets of 84 baht and 78 baht on the stock, respectively, as at May 15.
Morgan Stanley, which has an “overweight” rating on the stock and a price target of 82 baht, projects a US$25 million boost to the group’s annual free cash flow for every million additional international passengers.
“Multiple triggers including improving traffic, duty-free guarantees starting Apr 23, balance-sheet repair and operating leverage should (result in AOT outperforming) street earnings expectations,” said its analysts.
PTT Exploration and Production: A mixed bag
Brokerages are split on their recommendations for energy play PTT Exploration and Production (PTTEP), with the proportion of “buy” calls (44.4 per cent) slightly below that of “hold” ratings (48.1 per cent).
Another 7.4 per cent of Bloomberg poll respondents rate the energy giant at “sell”.
UOBKH, DBS, RHB and CGS-CIMB are among those who rate the stock favourably, with their target prices ranging from 170 baht to 183 baht. The stock closed at 150 baht on Wednesday.
Though DBS and RHB expect PTTEP to be hit by declining sales volumes and gas prices in Q2, they anticipate other mitigating factors to come into play.
DBS thinks oil prices pose the “lowest downside risk” as global crude inventory levels remain low. And the upcoming driving season in Europe and the United States is expected to boost global oil demand.
RHB said unit costs should stay within an “acceptable range” below 2022 levels due to lower royalty expenses, a decline in average selling prices, as well as a drop in depreciation expenses per unit.
“Despite the slight drawback caused by the decrease in sales targets for 2023, we believe PTTEP’s current share price has already taken into account many negative factors,” added UOBKH in a May 2 note.
CGS-CIMB likewise deems the group’s valuation as “not yet excessive”. It continues to rate the stock at “add” despite cautioning potentially lower sales and higher unit costs for the rest of the fiscal year.
Morgan Stanley, however, foresees limited upside for the stock due to declining government intervention as well as a slowdown in earnings as a result of lower commodity prices and higher cost inflation, amid a tightening global oil services market.
Instead, the “volume growth story” is better played via parent company PTT Group along with PTT Global Chemicals, its other SET-listed subsidiary, said its analysts.
Nomura is “neutral” on PTTEP with a 169-baht price target, as it reckons the group’s earnings may have peaked in FY2022.
It projects a 35 per cent year-on-year drop in FY2023 net profit due to lower average selling prices and exchange rate estimates. “Future mergers and acquisitions may be smaller than the deals made in the past two to three years. Management believes it may take longer to complete transactions during periods of high oil prices, as buyers and sellers may have different price expectations,” said its analysts.
TRENDING NOW
ComfortDelGro appoints two new independent directors

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
NoonTalk needs continued financial support from CEO Dasmond Koh, auditors warn
DP Architects sets the benchmark for sustainability disclosure and design

