


Fed decision this week will signal Powell’s priority: financial stability or inflation control
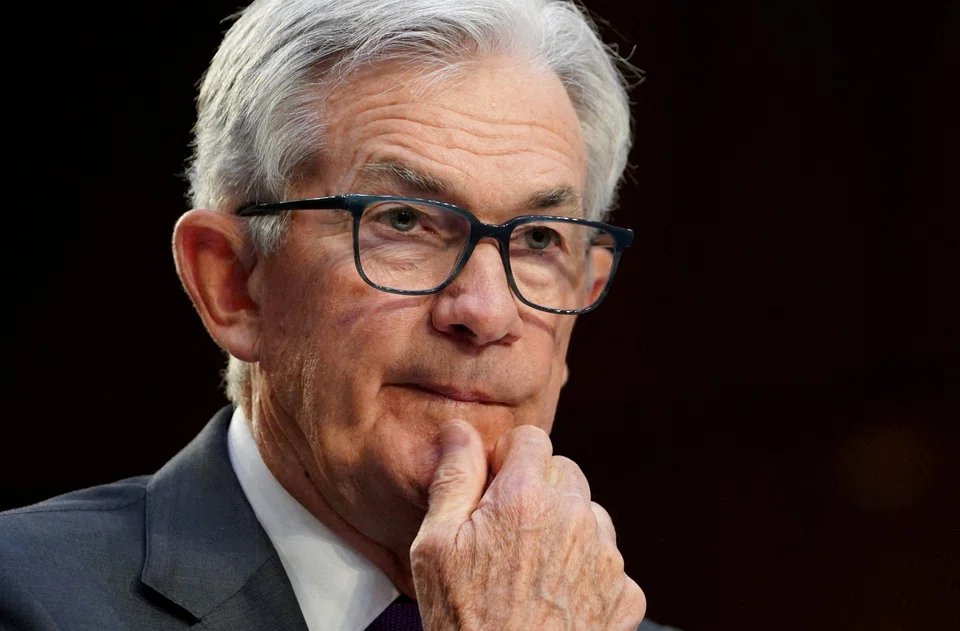
THIS week, the United States Federal Reserve will find itself trapped between a rock and a hard place: forced to choose between a financial crisis and an inflationary spiral.
The central bank is widely expected to raise interest rates by a quarter of a percentage point at the conclusion of its meeting on Wednesday (May 3), bringing its benchmark rate to a range of 5 per cent to 5.25 per cent. The Fed will have to acknowledge the ongoing distress in the banking system as it provides guidance for future moves.
For now, a financial crisis seems to be the central bank’s preferred poison. The Fed is hoping an ongoing wave of major bank failures can still be contained. Under chairman Jerome Powell, the Fed has taken on the aspect of firemen: trying to isolate massive fires in the California brush before they reach major cities.
Some Fed officials have indicated that they would like to pause interest rate hikes at the central bank’s meeting, if only to alleviate pressure on California lenders teetering on the edge of failure. Others, including key decision makers such as New York Fed president John Williams, have dismissed fears that more rate hikes would lead to more bank runs, and pointed to inflation as the more imminent threat.
Still, odds in futures markets are firmly pointed towards a final rate increase of the current policy cycle on Wednesday. The last faint hopes that the central bank could relent because of banking worries evaporated when the labour department reported last Friday that the personal consumption expenditure index – the Fed’s preferred gauge of consumer inflation – ticked up in March.
“The Fed didn’t have any problems going in and raising rates last month, and it was a much worse scenario at the time,” said Quincy Krosby, chief global strategist at brokerage LPL Financial, noting that the March meeting happened days after the failure of Silicon Valley Bank.
A rate hike may come in concert with a coordinated rescue of First Republic Bank, which is on its last legs after disclosing a flight of depositors in the first quarter. Shares of the California lender crashed late last week after reports that the Federal Deposit Insurance Corporation was preparing to take the bank into receivership.
The Fed would likely step in to limit the fallout in credit markets, such as in the mortgage-backed security market. A First Republic failure could cause significant ripples in the latter, according to analysts at brokerage Goldman Sachs.
Chances of this central bank being remembered for inducing a banking-industry collapse are rising, though. Digital-age, instantaneous bank runs have already claimed some large lenders, including Silicon Valley Bank, Signature Bank and Credit Suisse Group.
The next in line appears to be another California lender, Pacwest Bancorp, which has a comparable profile to First Republic.
The abrupt lunges up and down in California bank shares are reminiscent of mortgage-lender selloffs in the runup to the 2008-09 financial crisis.
Then, too, there were hopes that Bear Stearns, or Countrywide Financial, or Washington Mutual would be the last domino to fall. But there was always one more bank behind.
Eventually, the wildfire spread from the mortgage specialists on the fringes of the financial system to its very heart.
Most strategists see a link between the rate hikes and the current banking crisis. As a sailboat may seem seaworthy in light winds only to founder when a gale blows, so banks that thrived during the era of low interest rates are ill equipped to weather higher rates.
In this case, higher rates pressured Silicon Valley Bank and First Republic from two sides: the long-term bonds they held on their balance sheets lost value when yields rose; and depositors were quick to pull cash when they could earn higher interest rates in safer places such as money market accounts.
The critical part of this week’s meeting for the stock market will be the press conference, said one strategist. This is where investors will seek to reconcile the indications in futures markets that the central bank will start cutting rates later this year with Powell’s repeated vows that the central bank is not even considering rate cuts.
“The markets have been a little bit of a bratty child: ‘This is what we think it should be’,” said JJ Kinahan, chief executive of IG Markets North America, the parent of brokerage tastytrade. “Powell hasn’t really changed his overall stance, which is ‘I’m going to do what I have to do to bring down inflation’,” he said.
Powell is “adamant” he will not repeat the mistakes of Arthur F Burns’ Fed in the 1970s, said Krosby. Burns had a “stop-and-go” approach: the Fed interrupted its rate hikes only to resume later.
Powell has voiced his fears that a premature pause in the rate-hike cycle would, as in Burn’s era, allow inflation to settle into the system.
Powell will be confronted with one question over and over again in the press conference, Krosby said. He will not be able to answer it directly, but he will have to give some hints.
The question: Is this it?
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Share with us your feedback on BT's products and services
TRENDING NOW

Malaysian king buys stake in Singapore-listed mining firm expanding into rare earths
Family offices ‘kept captive’ by relationship managers turn to independent advisers, direct deals

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

Could stablecoins be the future of money?

