

Any pivot on rates by Fed will mean more blood in stock markets
Latest GDP, inflation data appear to be against conventional wisdom that the US central bank had engineered a ‘soft landing’
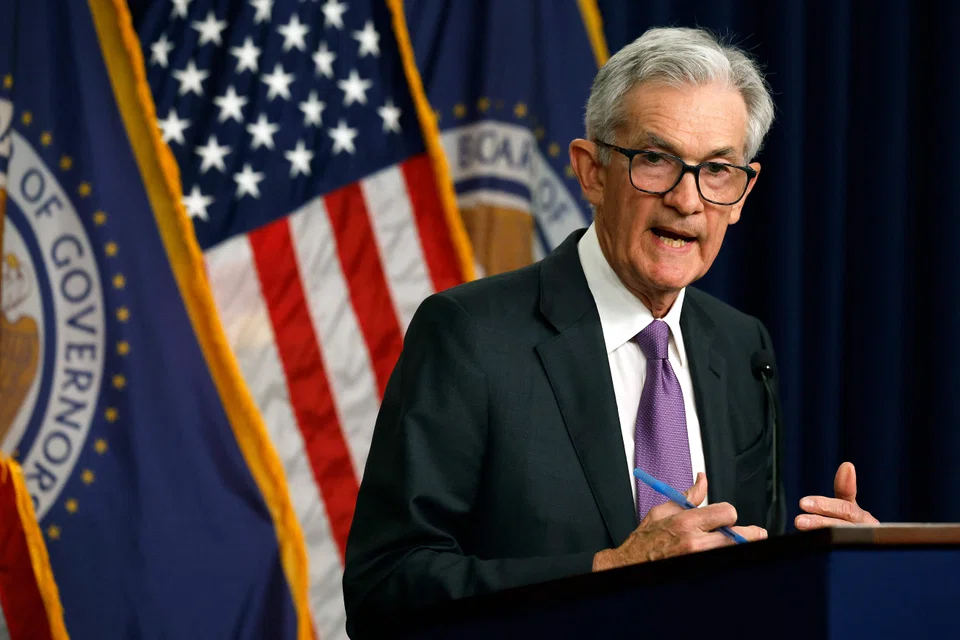
EARLIER this year, US Federal Reserve chairman Jerome Powell was keen to tell the world that the threat of inflation was gone and that the central bank was reopening the US for business by pivoting to easy-money policies.
At the Fed’s meeting in March, he again signalled that inflation had been dealt with during his 18 month rate-hike voyage.
He promised the markets that the Fed would cut rates more than once in 2024, barring what he saw as the extremely unlikely event of more inflation sightings on the horizon.
In the weeks since, it appears that Powell may have declared the threat of inflation to be over a bit too soon. Just when investors thought it was safe to return to the stock market, rising inflation reappeared on consumer-price inflation charts.
Inflation was shown rising on a month-to-month basis, confirmed in both the first-quarter gross-domestic product data and last Friday’s (Apr 26) personal-consumption expenditure index.
The price statistics in the GDP data caused terror a day earlier on Thursday as the anaemic 1.6 per cent growth rate combined with an unexpectedly high 3.4 per cent annual rate in the first quarter.
Until the recent uptick in inflation data, the conventional wisdom was that the Fed had engineered a “soft landing” – the best of both worlds where inflation would fade without a recession.
Thursday’s GDP data appeared to be the “worst of both worlds”, said David Donabedian, the chief investment officer of Canadian money manager CIBC Private Wealth, in a widely circulated commentary.
The worst of both worlds has occurred before. In the 1970s, growth was waning and inflation rising simultaneously, which marked the start of the dreaded stagflation era.
After the surprising GDP data, scores of investors fled stocks. One brokerage helped to calm the waters as economists there suggested the apparent leap in prices was likely a technical issue, involving revisions to January and February data.
The danger of inflation remains a clear and present danger. These findings were corroborated in Friday’s March personal consumption expenditure index, which showed a more modest 2.8 per cent inflation rate.
There was “no sign of ‘stagflation’” in Friday’s report, said economists at brokerage Bank of America Global Research in a note to clients.
“The US economy remains on solid footing despite some moderation in the first quarter. Spending continues to surge and consumer demand remains resilient. The first-quarter data is consistent with acceleration in services demand and not indicative of “stagflation” or a negative supply shock.”
Still, the inflation data has showed a sustained enough up-tick that the Fed is unlikely to point to June as the likely start-date of the rate-cut cycle, as markets had priced in the wake of the March meeting.
If Powell pivots yet again during Wednesday’s press conference and cancels rate-cut plans, or worse, hints that the central bank may have to return to its hiking ways to nip inflation in the bud, there will be more blood shed in the stock market.
The S&P 500 fell by more than 5 per cent from its March peak when inflation scares resurfaced earlier this month. Treasury yields tested multi-year highs, foreshadowing a cancellation of the cuts.
If yields keep rising, as they will in the event of another pivot, that could cause another drop in commercial property prices, which would lead to more bank failures and, this time, knock-on effects in the much larger single-home residential market.
At least one strategist said the strong earnings growth exhibited by tech companies and others benefitting from the blossoming of artificial intelligence capabilities could offset the negative impact of another surge in interest rates and Treasury yields.
“Investors are still going through a recalibration of what it might mean for the economy and for stocks and earnings if interest rates stay at current levels for the year,” said Oliver Pursche, the senior vice-president at financial advisory Wealthspire.
“In January, if I had told you there would be no rate cuts for the year, you’d either think I was nuts or there would be a massive market correction,” he added.
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

Inside Singapore’s government team that kills its own products
Johor’s investment boom is real, but actual contribution from JS-SEZ unclear
Inside F1: How ‘reactive’ DHL acted quickly to fit Malaysia race just before Singapore’s

