

Issue 127: Sembcorp stays on transformation course; much ado about Adani Green
This week in ESG: Contracts, deals reflect Sembcorp’s aggressive transition; funds caught holding Adani Green as bribery charges filed
Energy transition
Sembcorp’s transformation
Hardly a month goes by without Sembcorp Industries announcing a renewable-energy contract or strategic deal, the latest being a 300 megawatt (MW) wind-solar hybrid project in India that it will build, own and operate.
The deals reflect an aggressive multi-year shift into the energy transition space, putting Sembcorp on track to becoming one of the purest renewable energy plays on the Singapore Exchange. But the big bet on renewable energy comes with its own risks, including the possibility that renewable energy demand will not be as high as expected.
Sembcorp first made a strategic decision in 2021 to transform itself, once one of the biggest oil and gas rig builders in the world, into a sustainability solutions group. Two years later, the company reaffirmed its commitment to the transition with a 2024-to-2028 roadmap that included S$14 billion of capital investment over the period.
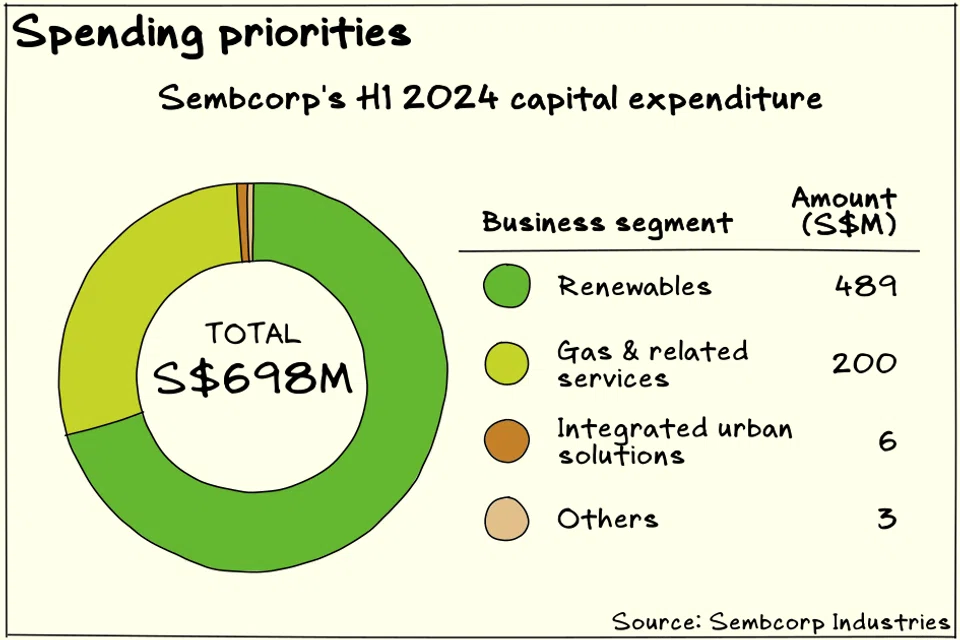
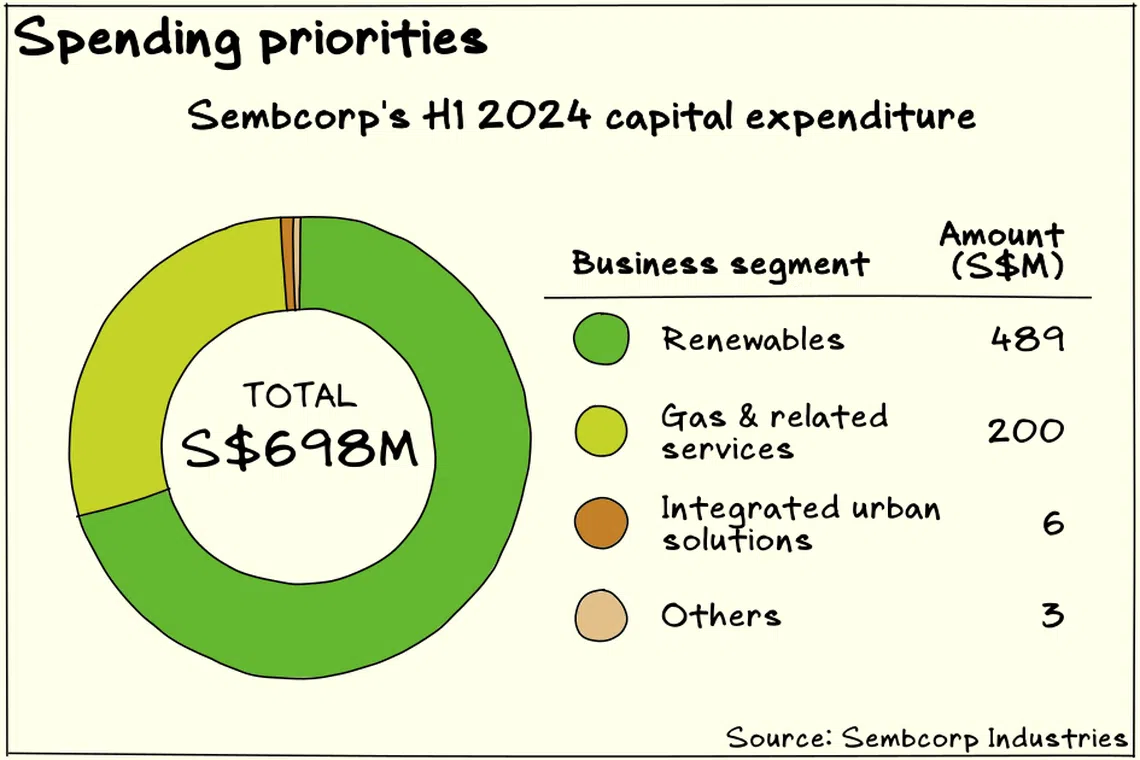
A good 90 per cent of that planned investment will go to sustainability-related businesses. About 75 per cent of the planned investments are earmarked for the renewables segment. Another 10 per cent will go towards decarbonisation solutions, a new business segment that Sembcorp is trying to develop. A further 5 per cent is reserved for integrated urban solutions, which is largely a sustainable real estate development arm.
Most of the remaining 10 per cent will be invested into “hydrogen-ready” assets and replacement capital expenditures. These can include natural gas projects, which Sembcorp undertakes as a transition business that should eventually be replaced with more sustainable solutions.
Sembcorp’s renewables business is now significantly bigger than it used to be. In 2022, Sembcorp’s renewables gross installed capacity was just 8.3 gigawatts (GW). With the new India project, global its renewables capacity increases to 16 GW, including a 49 MW acquisition that is pending completion. In India, Sembcorp’s renewables capacity now stands at 5.4 GW.
Uncertain demand
The big bet on renewables means that Sembcorp’s future performance is indelibly tied to its thesis that the energy transition will be a strong driver of growth.
While the brisk pace at which Sembcorp has been able to secure renewables contracts suggests that the thesis is sound in the long term, it’s not without some short-term bumps.
Renewables net profit in the first six months of 2024 slipped 7 per cent to S$113 million from S$120 million the year before, despite new acquisitions in China and India and an increase in capacity. Sembcorp explained that the decline was due to weak energy demand in China amid a slowdown in economic activity, which led to higher curtailment. Curtailment refers to a slowdown in energy production or supply to balance out lower demand.
With the threat of US tariffs casting a shadow on the outlook for global trade, the export economies in Sembcorp’s key Asian markets could face speedbumps in their growth for the next few years. That could not only dampen overall electricity demand but also weaken appetites for investing in replacing fossil fuels in the short term.
Gas mileage
The gas and related services business, which remains Sembcorp’s largest single business segment, saw net profit rise 30 per cent to S$809 million in 2023 from S$622 million a year earlier, driven by Sembcorp’s cogeneration plants in Singapore.
The gas operations provide an important buffer for Sembcorp as it invests in the transition. The gas assets mean that Sembcorp has some margin for error if national electricity policies in the company’s various markets move more slowly than expected towards renewables.
But Sembcorp might have to lean on its gas business for longer than its ambitions indicate. In the first half of 2024, gas and related services still accounted for almost two-thirds of net profit.
Busy dealer
All the same, Sembcorp will probably be active on the mergers and acquisitions front for the next few years.
A major divestment is set to take place by the first half of 2025 with the planned sale of its integrated waste management arm Sembcorp Environment. Buyer TBS Energi Utama, an Indonesian integrated energy group, is expected to pay S$405 million for the unit.
The proceeds of the sale will go towards Sembcorp’s renewables business.
The sale will shrink Sembcorp’s Integrated Urban Solutions business. Sembcorp Environment made pre-tax profit of S$13 million in the first half of 2024, about 16 per cent of the Integrated Urban Solutions segment’s profit of S$83 million over that period.
It will also change the nature of the Integrated Urban Solutions segment, shifting the business unit more towards development.
In August, Sembcorp announced its strategy for the Integrated Urban Solutions segment, centred on an ambition to be a leading low-carbon industrial park player in Asia.
This will involve:
- Stepping up land development by expanding the company’s land bank from 14,000 hectares as at end-June 2024 to 18,000 ha by 2028;
- Increasing industrial properties to 1.5 million square metres by 2028 from 0.1 million sq m as at end-June 2024; and
- Targeting a net profit compounded annual growth rate above 15 per cent from 2022 to 2028 and a return on equity of 10 per cent in 2028.
Committed transition
Sembcorp has largely stuck to the roadmaps it laid out in 2021 and 2023, and it is on track in terms of its investments targets. However, the transition’s success in profit terms remains to be seen.
Sustainable investing
The Adani taint
The Adani bribery spectacle in India has cast an unwelcome spotlight on the environmental, social and governance (ESG) industry, which had embraced Adani Green Energy despite its governance issues.
US prosecutors have charged Gautam Adani, head of the Adani conglomerate, with suspected bribery over allegations that he and his associates offered more than US$250 million to Indian government officials in exchange for solar projects for Adani Green.
It has been reported that about 770 ESG funds held shares of Adani Green before the charges. Furthermore, ESG rating agencies like MSCI and Morningstar Sustainalytics had given Adani Green high marks before the charges.
Stories about ESG funds holding tainted investments inevitably make the rounds after every major scandal. It’s an understandable knee-jerk since ESG investing tends to wrap itself in a holier-than-thou aura of goodness. However, it can also be unfair because investment screens are never perfect.
But just because something is imperfect doesn’t mean it’s harmful or useless. Research led by the Aggregate Confusion Project at the Massachusetts Institute of Technology (MIT) suggests that despite significant noise and divergence, ESG ratings still carry some useful signals for the market, in the sense that there is generally a positive correlation between ESG ratings and stock performance. There is also some degree of alignment across ratings providers, albeit on a narrow range of factors.
Fund managers and raters are also trying to make sense of problematic data. Not all ESG factors are reported the same way, and assurance rates remain relatively low.
Some of these issues can hopefully become less problematic as the market becomes more sophisticated. For example, the roll-out of international accounting standards for sustainability and climate reporting under IFRS could improve the quality of data, especially as assurance becomes more common.
ESG funds and ratings agencies also need to be more transparent about their methodologies. In particular, aggregate scores that combine environmental, social and governance factors into a single grade should be supplemented with a breakdown of the components and how they’re combined so that end users understand how each dimension is weighted.
ESG fund managers and rating agencies can do better. But it’s important that they’re not trying to fix the wrong problems.
Other ESG reads
- SingLand builds on sustainability efforts, sees ESG credentials as prerequisite to attracting tenants
- South-east Asia’s ESG bond proceeds jump 80% in Q3 2024 with new and existing issuers entering the market
- Used cooking oil the new black gold as it rides biofuel demand, limited supply
- HSBC sustainability chief leaves after executive committee role dropped
- India aiming to finalise carbon deals with Japan, Singapore
- Climate finance’s ‘new era’ shows new political realities
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

What role can Japan play in Asean’s future?

From folding clothes to factory work: Why China is sending humanoid robots to school

