

Andy Burnham’s victory may change Labour’s politics, but not Britain’s business direction
Regulations exert a powerful influence over 10 Downing Street
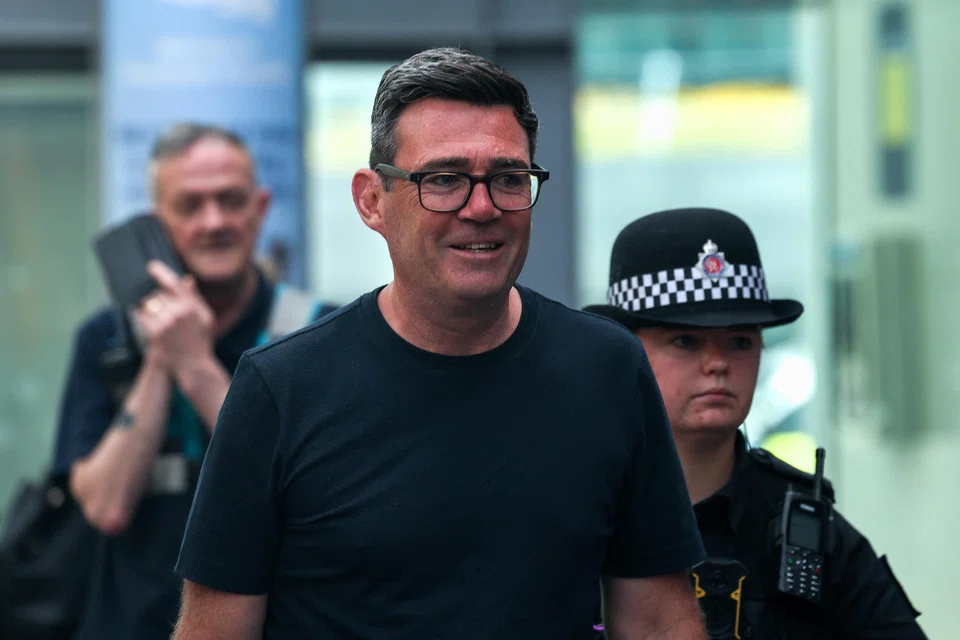
THE victory of Andy Burnham in the Makerfield parliamentary by-election has settled one question in British politics while opening another.
The first is whether the now former Greater Manchester mayor has demonstrated enough electorally to be able to replace Keir Starmer as prime minister. The second is what a Burnham-led government would mean for business, investors and heavily regulated sectors.
The answer to the latter is less dramatic than many assume.
Burnham’s victory was significant not simply because he won, but also because of how he won.
Securing 54.8 per cent of the vote in a constituency that had only weeks before voted strongly for Nigel Farage’s Reform UK, he demonstrated an ability to unite Labour’s traditional base while attracting tactical support from voters primarily motivated by opposition to Reform.
The result strengthens his claim that he can both represent Labour’s values and win elections – the two tests that often determine leadership contests in British politics.
What his victory does mean is that Burnham is more likely to end up as prime minister in weeks rather than months – a process that is more a coronation than a contest.
Now, with Starmer’s announcement on Monday (Jun 22) that he will step down as prime minister by September, that timetable has accelerated dramatically, making a Burnham premiership a more immediate prospect.
Change in tone, not tune
For markets and businesses, however, the more important question is whether political change at the top will see a significant policy shift leftwards on most major economic and regulatory issues.
The evidence suggests continuity rather than rupture.
Britain’s institutional framework limits the scope for sudden policy reversals. Fiscal rules, financial regulation, statutory climate commitments and major international security obligations are deeply embedded.
A new prime minister can alter priorities, tone and emphasis, but changing the underlying architecture is considerably harder. That distinction matters.
In financial services, for example, the foundations of regulation are unlikely to shift materially. The Basel capital framework, the Financial Conduct Authority and Prudential Regulation Authority structure, and broader market reforms are all well established.
A Burnham government would probably place greater political emphasis on the social role of finance, regional investment and economic inclusion, but the prudential regime itself would remain intact.
The practical implication for banks and asset managers is not a more hostile regulatory environment, but greater pressure to demonstrate economic value beyond London and the south-east region of the UK.
Burnham will want to encourage greater investment, both private and public, in the north of England. But this is merely a continuation of policies pursued by UK governments of every hue.
Energy policy presents a similar picture.
One common misconception is that Burnham’s political appeal in former industrial regions implies a softer approach to net-zero commitments.
His record suggests the opposite. As mayor of Greater Manchester, he championed carbon-neutral targets that were significantly more ambitious than the UK’s objective to reach zero emissions by 2050, and consistently argued that decarbonisation should be linked to jobs, skills and lower household energy bills.
What distinguishes Burnham’s approach is not scepticism about climate goals, but pragmatism about implementation. His decision to retreat from Greater Manchester’s Clean Air Zone after public opposition illustrated a willingness to abandon measures that impose visible costs on voters.
That does not indicate reduced commitment to sustainability objectives; rather, it reflects an instinct to prioritise politically sustainable delivery.
For investors and energy companies, that could translate into stronger support for place-based projects, community ownership models, grid investment and industrial decarbonisation initiatives that create local economic benefits.
In other words, the opportunity narrative around net zero may strengthen even if policymakers become more cautious about consumer costs.
Technology companies may face a more challenging environment.
Among the most notable policy areas is online safety. Burnham has historically adopted a more interventionist stance than Starmer on protecting children online, arguing for stronger action against harmful digital platforms.
As a result, tech businesses should be more concerned than others that a change at the top of British politics is likely to mean a more interventionist approach.
That could entail greater restrictions or regulations on these firms, especially social media companies already affected by the Online Safety Act and the recently proposed ban on the use of their platforms by under-16s.
More importantly, the debate is already expanding beyond age-based access restrictions to include platform design, recommendation algorithms, live-streaming functions and artificial intelligence-enabled interactions.
The larger picture is that regulatory focus is shifting from what young users can access to how digital products are designed and monetised.
For global technology firms operating in the UK, the challenge may therefore be less about compliance with a single headline measure and more about adapting to a broader product-safety agenda.
Defence is another area where continuity could mask significant shifts in emphasis.
Burnham has signalled support for higher defence spending and has argued that changing geopolitical realities require a reassessment of public spending priorities.
His approach combines support for long-term defence investment with an emphasis on employment, apprenticeships and domestic industrial capacity.
This creates opportunities for defence, aerospace and advanced manufacturing companies that can demonstrate contributions to local employment and skills development.
Procurement decisions may increasingly incorporate social-value considerations alongside traditional commercial criteria.
At the same time, more funding for defence inevitably raises questions about competing demands on public finances. Debates over welfare spending, public services and fiscal trade-offs are likely to intensify.
The political challenge for any future government will be balancing security commitments with expectations for continued investment in health, local government and social support programmes.
Regulations hold leaders in check
Taken together, these sectoral trends point to a broader conclusion.
The most important consequence of Burnham’s likely move to 10 Downing Street may not be radical policy change but a shift in political philosophy.
Businesses should expect a stronger emphasis on industrial strategy, regional economic rebalancing and the role of the state in supporting investment and growth.
There is likely to be greater scrutiny of large institutions, from banks to technology platforms, alongside stronger expectations that they contribute visibly to economic and social outcomes.
A Burnham government would also prioritise improving living standards in the north of England, expanding state intervention – if not state ownership – and promoting economic inclusion while tackling inequality.
Yet, while the language of governance and regulators may become less business-friendly, the fundamental policy environment is unlikely to alter much.
Britain’s regulatory frameworks, international commitments and fiscal constraints continue to exert powerful influence regardless of who occupies the prime minister’s office.
For investors and corporate leaders, the key lesson is that a Burnham premiership would not mean a dramatic leftward shift. Instead, interpreting opportunities and threats will be their greatest challenge.
Mark MacGregor is the former chief executive officer of the Conservative Party and currently partner of public affairs at Penta. Shawn Balakrishnan is a partner at Penta overseeing the Asia-Pacific region.






