

Big Oil faces a ‘good sweating’; some aren’t fit
For the last few years, oil industry giants have enjoyed a bonanza but the tailwind has now turned into a headwind
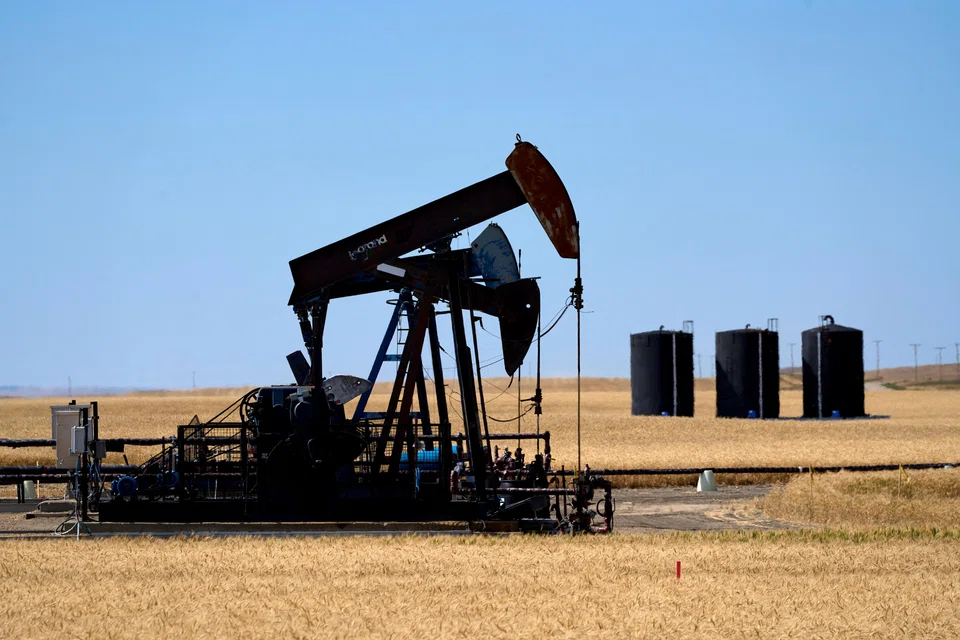
WHEN John D Rockefeller wanted to punish a rival, he cut prices to force them to operate at a loss. The father of the modern oil industry had a name for it: a “good sweating”.
A century later, the Organization of the Petroleum Exporting Countries and allies (Opec+) is giving Big Oil the modern equivalent of Rockefeller’s time-tested tactics.
Not everyone will be fit enough for it. For the last two-and-a-half years, Big Oil has enjoyed a bonanza, profiting from the impact of Russia’s invasion of Ukraine and Opec+’s tight control of the market. High prices inflated cash generation, leading to bumper payouts to shareholders – via, above all, buybacks.
But the tailwind has now turned into a headwind, and the size of the group’s share repurchases will drop, probably from 2025 onwards. Jefferies Financial Group, an investment bank, has warned that at current forward prices for next year, half of the international oil companies “can’t sustain their distribution” without taking more debt.
For Big Oil, that is a big problem. The industry does not have many allies on Wall Street and certainly even fewer in the greener financial hubs of Europe. In the climate-crisis era, Fossil Fuel Inc needs to shower shareholders with money just to keep investors – particularly the large generalists – onside.
The size of the buybacks has been huge. Only this quarter, ExxonMobil, Chevron, Shell, TotalEnergies and BP plan to repurchase more than US$16.5 billion of shares. On an annualised basis, that is equal to US$66 billion a year, or about 5.5 per cent of Big Oil’s current combined market value.
The mega buybacks made sense during the boom. But Big Oil now faces a completely different landscape.
Brent, the global oil benchmark, averaged about US$90 a barrel between 2022 and 2023. Now, it is trading below US$75 a barrel, and futures for delivery in 2025 are changing hands at about US$70 a barrel.
It is not just the price of crude. Over the last three years, the industry also profited from historically high refining margins (an average of US$35 a barrel in 2022-23, compared with less than US$15 now) and liquefied natural gas prices (an average of US$24 per million British thermal unit in 2022-2203, compared with about US$12 per million now).
The cyclical change would not hit everyone equally, though.
Exxon and Chevron are fitter than anyone. With little net debt and the highest credit ratings of all major oil companies, they could borrow to keep paying shareholders. A few quarters of debt-taking will not push either company into trouble but instead bring their leverage ratio to historical levels. Both companies anticipate significant year-over-year oil and gas production for 2025, giving them extra firepower. It could be a golden opportunity for Chevron and Exxon to showcase their stronger business model compared with their European rivals.
Shell and TotalEnergies are, in that order, in the middle of the group – and could weather a few bad quarters, even if they carry more debt than their American rivals. BP faces the biggest risk and also has the weakest balance sheet. The British company, however, has already promised investors that it will not reduce the buyback rate until the end of 2025. That is rather courageous. Even those companies that can take on debt to sustain elevated buybacks should opt for prudence.
Opec+’s plans for 2025 are unclear. The cartel has launched two price wars during the last decade – thus, it would be wise to anticipate and plan for a third. Weakening the balance sheet too much to sustain share repurchases would be a mistake until the cartel’s plans become clearer, something that is unlikely before December.
For now, Big Oil is putting on a brave face. Between the lines, however, the first warnings are emerging.
Total, for example, tweaked its guidance for buybacks during the summer. In the past, the company said it would buy US$2 billion a quarter; in August, it told investors it would buy “up to” US$2 billion a quarter. It may be the slimmest change, but directionally it matters.
BP, for its part, warned investors that its 2025 outlook of US$46 billion to US$49 billion of underlying profits was based on energy prices staying at 2023 levels, when Brent averaged about US$82 a barrel. If oil prices fall next year to an average of US$75, the company’s own rule of thumb suggests a US$4 billion shortfall. Currently, Brent for delivery next year is trading closer to US$70 a barrel.
While buybacks need to come down, I do not see a risk for dividends. That is in part thanks to the hefty buybacks of the last two years, which have reduced the number of shares outstanding and thus the overall cost of the dividend itself.
It also helps that Shell cut its dividend during the pandemic for the first time since 1945, in turn improving the affordability of the payout. Of the five major international oil companies, only Exxon, Chevron and TotalEnergies have not cut their dividends in several decades.
Lower buybacks are not catastrophic but just a natural outcome as the cycle turns. If anything, perhaps the current rate of repurchases could not hold up to begin with. For example, Total and Shell, which promised to return as high as 40 per cent of their free cash flow to investors, had at times paid close to 45 per cent via dividends and buybacks. That was unsustainable.
TRENDING NOW

Malaysian king buys stake in Singapore-listed mining firm expanding into rare earths
Family offices ‘kept captive’ by relationship managers turn to independent advisers, direct deals

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

Could stablecoins be the future of money?

