

Changi leads the world. That is not the same as leading the decade
Singapore’s aviation ecosystem earns another set of superlatives. The harder questions lie beneath the headlines
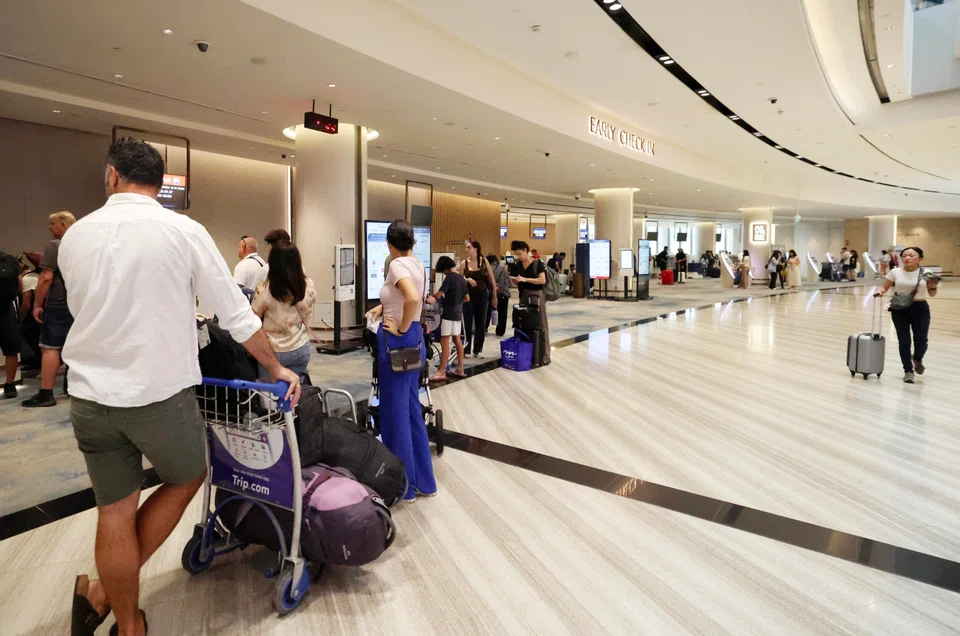
THE Brand Finance Airlines 50 2026 report lands with the reliable satisfaction of a Singapore Airlines (SIA) arrival: on time, well-presented and broadly confirming what the industry already suspects.
SIA climbs to 14th globally with a brand value of US$3.1 billion, up 12 per cent year on year. Changi Airport retains its AAA+ rating and a Brand Strength Index (BSI) score of 91.2 out of 100 – the highest of any airport brand worldwide.
The numbers are impressive. They are also, in important ways, insufficient.
Brand valuations are snapshots, not forecasts. They measure the accumulated equity of past decisions – product investments, service culture, infrastructure spend – against current market sentiment.
What they capture less well is structural fragility: the gap between a brand’s perceived strength and its actual resilience to the pressures gathering beneath the surface of global aviation.
Singapore’s aviation ecosystem deserves its accolades. It also deserves a more searching examination, one that the country’s policymakers, airline strategists and infrastructure investors are well-placed to lead.
Structural routing shifts
Changi’s brand supremacy is, by any reasonable measure, earned. Decades of disciplined investment – in passenger experience, terminal infrastructure and digital processing capability – have produced a model that most hub competitors struggle to replicate.
Jewel Changi Airport and the ongoing Terminal 5 development are expressions of a long-held conviction that infrastructure quality is a strategic asset, not a cost centre.
Yet the BSI is fundamentally a customer satisfaction construct. It measures what passengers feel at the point of experience. It does not measure how exposed the hub is to the geopolitical and structural disruptions that are quietly reshaping global aviation routing.
Consider the current environment. Gulf airspace volatility, driven by persistent Middle East tensions, has disrupted the routing assumptions that have underpinned Singapore’s connectivity model for years.
Several European carriers have been forced to reroute or reduce frequency on corridors through which a significant share of Changi’s connecting traffic flows. Simultaneously, Chinese carriers are aggressively expanding point-to-point international networks, offering European and Asia-Pacific passengers direct options that bypass traditional hub connectivity entirely.
Neither dynamic registers in a brand strength index. Both carry material consequences for Changi’s long-term traffic volumes.
Changi is demonstrably excellent. The question, however, is whether excellence at the point of experience is sufficient in an environment where structural routing shifts, not service scores, increasingly determine who lands where.
Brand premium under pressure
SIA’s 12 per cent brand value growth reflects genuine operational strength. Sustained premium and long-haul demand has validated the carrier’s strategic positioning. The dual-brand architecture with Scoot – pursuing yield optimisation at the premium end while defending share in price-sensitive segments – remains one of the more coherent strategies in Asia-Pacific aviation.
But brand value is not a competitive moat. In the premium long-haul segment, SIA faces structural pressure from carriers operating on fundamentally different cost bases.
The Gulf Big Three – Emirates, Qatar Airways and Etihad – are geographically advantaged for Europe-Asia routing and backed by sovereign capital that insulates them from fuel cost volatility in ways that commercially structured carriers simply cannot match.
ANA (All Nippon Airways), now ranked the world’s strongest airline brand with a BSI of 90.2, is expanding internationally with the discipline of a carrier that has absorbed the lessons of past overextension.
The report notes that SIA benefits from expanded cooperation with Lufthansa in Europe. That partnership merits scrutiny, not simply celebration.
Lufthansa Group is navigating one of the most structurally difficult periods in its recent history – chronic industrial disruption and a low-cost subsidiary model under strain.
Deepening interdependence with a partner under structural pressure is a risk management question as much as a brand enhancement.
Vietjet’s signal
The most consequential data point in the Brand Finance report is not about Singapore brands.
Vietjet’s 117 per cent brand value growth – fastest of any carrier globally – reflects a structural shift in Asian aviation that the Singapore ecosystem must take seriously.
Ultra-low-cost carriers with aggressive international expansion strategies and increasingly sophisticated ancillary revenue models are reshaping yield expectations across a large and rapidly growing segment of Asian travellers.
Singapore’s aviation strategy has historically been premised on premium positioning and hub connectivity. That positioning remains defensible – but increasingly at the edges of a market bifurcating at speed.
The segment that will grow fastest across South-east Asia over the next decade is not the business class passenger. It is the first-time international traveller from tier-two Vietnamese, Indonesian and Philippine cities, routed on carriers that Changi may not be optimally configured to capture.
A call for strategic candour
Brand rankings are lagging indicators. Strategy is a leading one. Singapore has long excelled at translating strategic clarity into infrastructure and policy decisions that competitors can only observe and admire. That tradition now demands a specific response.
The Civil Aviation Authority of Singapore, in close coordination with SIA Group and Changi Airport Group, should commission a public-facing stress test of Singapore’s aviation ecosystem against three scenarios: sustained Gulf airspace disruption, accelerated Chinese carrier point-to-point expansion, and a structural fuel price shock driven by Middle East supply disruption.
The outputs should inform the next iteration of Singapore’s Air Hub Development Fund allocation, bilateral air services agreement priorities, and Terminal 5 route incentive structures – not as contingency planning, but as the basis for proactive repositioning.
Singapore’s aviation brand was built on anticipation rather than reaction. The 2026 rankings confirm that the foundation remains strong. What matters now is that the strategic decisions being made today are calibrated for the aviation environment of 2030.
The writer is founder of BAA & Partners
TRENDING NOW

Tokyo reverses baby bust with AI matchmaking and generous subsidies
In a super-aged Singapore society, we must learn to differentiate independence from dignity

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing
China opens probes into four online travel booking platforms

