

‘The worst has passed’ for US office S-Reits, but investors should not jump in just yet
Investor sentiment towards the sector appears to be stabilising, but recovery among players remains uneven
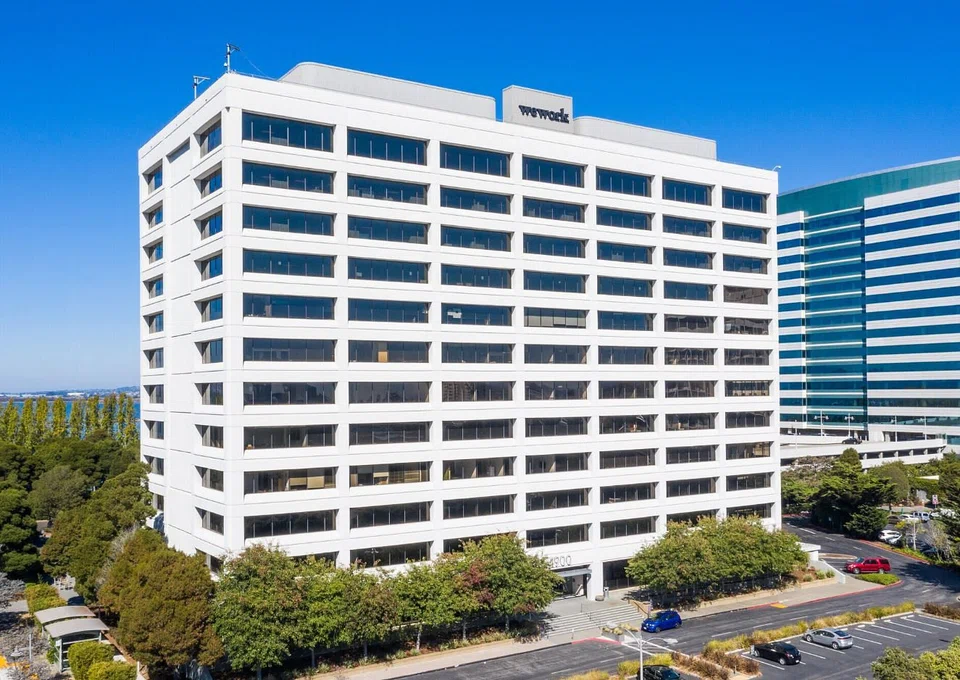
[SINGAPORE] Office S-Reits, or Singapore-listed real estate investment trusts, were among the hardest-hit sub-sectors during the Covid-19 pandemic. Remote work left many offices empty, and even after the pandemic, recovery has been slow as hybrid work models took root.
But Singapore’s office Reits have since bounced back.
Rental reversions have improved across the board. Keppel Reit , which holds predominantly Singapore office assets, posted a 12.3 per cent rental reversion in the first half of 2025, while Suntec Reit’s office segment recorded a 10 per cent increase.
The picture looks different for S-Reits with office assets in the US. Prime US Reit posted a reversion of 3.4 per cent in H1 of its financial year, while Keppel Pacific Oak Reit (Kore) had a 0.5 per cent increase. Manulife US Reit recorded a negative rent reversion of 10 per cent for the same period. The trio also still trade at about a 70 per cent discount to book value, in a stark contrast to their Singapore peers.
Flickers of recovery
That said, there are some glimmers of improvement. Investor sentiment towards the US office sector appears to be stabilising, with signs of renewed confidence.
In September, Prime US Reit raised US$25 million through a private placement at US$0.1935 per unit, and said that it would raise its dividend payout from 10 per cent to at least 50 per cent from H2 FY2025.
Kore has also indicated that it will resume dividend payouts from FY2026, and is considering a token distribution for H2 FY2025 if it successfully refinances its debt maturing in Q4 and 2026, after suspending payouts in late 2023 as part of its recapitalisation plans. Its rent reversion turned positive at 3.3 per cent in the second quarter, reversing earlier declines. (* see amendment note below)
At the macro level, conditions are also showing tentative signs of stabilisation.
RHB analyst Vijay Natarajan believes “the worst has passed” for US office Reits, noting that demand is slowly returning and deal flows are picking up as American interest rates peak.
Based on a report by property consultancy Savills, H1 2025 had the highest leasing volume since 2019, up 15 per cent year on year. This was driven mainly by return-to-office pressure rather than new job creation.
Office sales have also risen, as sellers become more realistic about current valuations.
Reality check
Even so, recovery remains uneven across the three Reits. Manulife US Reit, for one, continues to face steep challenges. It remains in the midst of asset disposals to pare down debt, having sold Capitol Mall in California (October 2024), 500 Plaza in New Jersey (February 2025), and the 28-storey Peachtree tower in Georgia (May 2025).
In contrast, Prime US Reit and Kore appear to be stabilising. But as Natarajan pointed out, the underlying dynamics of the US and Singapore office markets have diverged significantly.
Over the past few years, US office Reits have suffered from a slower return-to-office trend, lower demand due to companies downsizing, and high interest rates.
While the Fed’s expected rate cuts could lift asset valuations and ease financing pressures, challenges remain.
“We believe the sector has likely passed the worst and there are strong signs of office demand recovery now across the US, which is reflected in increased lease signings,” said Natarajan. “The momentum, if it continues, points to a stronger recovery in 2026.”
However, he warned that key risks remain, such as a volatile US interest rate outlook and the possibility of an economic recession due to tariff impacts.
Not out of the woods yet
For now, the numbers reflect a still-cautious market. The total return of office S-Reits year to date is 16.3 per cent, but US office Reits continue to lag.
Prime US Reit gained 12.4 per cent and Kore, 3.8 per cent, while Manulife US Reit posted negative returns of 20.3 per cent as at Oct 8.
The worst may indeed be behind them, but a sustained rebound is far from certain. Hybrid work arrangements continue to weigh on occupancy rates, and macroeconomic volatility could easily derail fragile gains.
For investors, patience may be the wiser course. Until clearer signs emerge, such as stabilised occupancy and consistent distributions, sitting on the sidelines could prove the more prudent move.
* Amendment note: An earlier version of this article stated that Kore is planning a token distribution for H2 FY2025. It has been revised to reflect that Kore is considering the token distribution if it refinances its debt.






