

Could Japan trigger the next global financial crisis?
The country’s changing capital flows could expose vulnerabilities in global markets
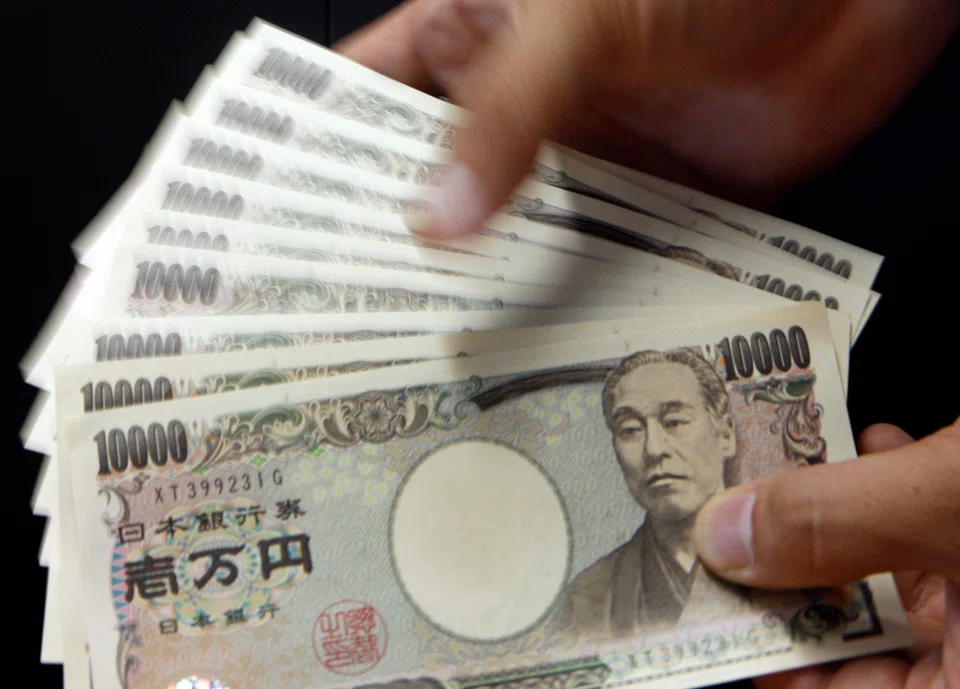
FOR decades, Japan’s exceptionally low interest rates helped finance the world. Its banks, insurers and pension funds invested heavily abroad, particularly in US government bonds. Now, as Japanese yields rise, those capital flows may be changing.
The evidence is striking.
In the five months to August 2026, major Japanese banks and insurers purchased a net 5.4 trillion yen (US$34.2 billion) of Japanese government bonds with a maturity of two years or more, and banks sold 2.5 trillion yen of foreign bonds in September, a Financial Times report indicated.
Japanese net investment in long-term US government bonds has also turned negative this year.
Could these shifts trigger the next global financial crisis? Not by themselves. But they could interact with already vulnerable sovereign bond markets and leveraged investors, turning a manageable adjustment into wider instability.
Changing investment patterns
Japan holds more than US$1 trillion in US Treasuries. For years, negligible domestic yields encouraged investment overseas.
But that behaviour might be shifting. The 30-year Japanese government bond yield recently reached 4.27 per cent, and currency-hedging costs can erode returns on foreign bonds.
Banks and insurers therefore have incentives to reconsider their allocations. They need not sell foreign securities immediately. Buying fewer overseas bonds and reinvesting maturing funds at home could gradually diminish demand for foreign assets.
Small changes matter when undertaken by institutions managing enormous portfolios. The issue is less a sudden sale of existing holdings than the possible erosion of a dependable source of demand for new government borrowing.
Why global bond markets are vulnerable
The timing is consequential. US public debt hit a record high of more than US$40 trillion in August, and the Treasury must refinance substantial obligations while funding new deficits.
As the Federal Reserve reduces its bond holdings, private investors must absorb more debt. At the recent International Monetary Fund (IMF)-World Bank annual meetings in Bangkok, mounting sovereign debt and diminishing fiscal buffers were major concerns.
France offers another warning. With debt approaching 120 per cent of gross domestic product, political resistance to budget adjustment has contributed to uncertainty and higher borrowing costs.
Reduced Japanese demand could add pressure to foreign bond yields, just as indebted governments require substantial financing.
Higher yields would raise borrowing costs and weaken asset valuations, including technology and artificial intelligence-related equities already vulnerable to a correction – making such market repricing an important risk.
The danger is cumulative: Higher sovereign yields can tighten financial conditions even before any disorderly selling begins.
The danger of yen carry trades
The more immediate threat comes from leveraged investors who borrowed cheaply in yen to buy higher-yielding foreign assets.
A sharp yen appreciation or higher Japanese rates can make these trades unprofitable, prompting forced sales and margin calls. The partial unwind in August 2024 showed how quickly stress can spread across markets.
The reported US intervention to support the yen in July underscored Washington’s concern about currency instability. Yet, yen appreciation can also accelerate the unwinding of leveraged positions, illustrating how currency and financial stability risks can interact.
Unlike gradual portfolio reallocation, leveraged deleveraging can be abrupt.
The IMF has reported that hedge fund gross assets have more than trebled since 2013 to about US$13 trillion.
Their leverage and links to banks through derivatives and financing can amplify shocks, spreading losses through bond markets, equities and emerging economies.
Non-bank financial institutions can transmit distress to banks through collateral calls, credit lines and repo financing, making the scale and speed of contagion difficult to anticipate.
A crisis is not inevitable
There is no evidence of wholesale Japanese repatriation. Pension funds bought a net 11.4 trillion yen of foreign long-term bonds in the first nine months of 2026.
Diversification, liability management and exchange-rate expectations continue to favour some overseas investment for Japanese institutions.
The real danger is a conjunction of shocks: sharp yen movements, disorderly Japanese bond-market adjustment and renewed doubts about advanced-economy fiscal sustainability.
Japan would not necessarily cause the underlying vulnerabilities; it could provide the trigger that exposes them. That distinction matters for judging both the probability of a crisis and the policy response.
An international stability test
Neither the Bank of Japan nor the Federal Reserve can subordinate domestic objectives to foreign investors’ portfolios. But both must recognise the international consequences of their decisions.
The IMF should assess how Japanese capital flows, sovereign debt risks and leveraged non-bank finance interact. Regulators need better cross-border data and stress tests covering simultaneous bond and currency-market shocks.
Japan’s monetary normalisation is appropriate, and a global crisis is far from inevitable. But it is occurring when sovereign borrowing needs are high and financial exposures increasingly interconnected.
For decades, Japan’s low interest rates helped finance the world. The question now is whether the world is prepared for Japan to bring more of its money home.
The writer is a distinguished fellow at the Centre for Social and Economic Progress and former Asia-Pacific director at the International Monetary Fund
TRENDING NOW
Philippine power giant First Gen rebuffs foreign offers, plans up to US$2.6 billion in expansion

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
Nearly half of Singapore workers put in at least six unpaid hours a week: survey
Vietnam’s data-centre investment rush faces reality check on power and site constraints

