

MARK TO MARKET
DBS, OCBC, UOB face rate hike reality check
The recent sell-off may not have been about the micro fundamentals of the 3 banks but a broader repricing of risk
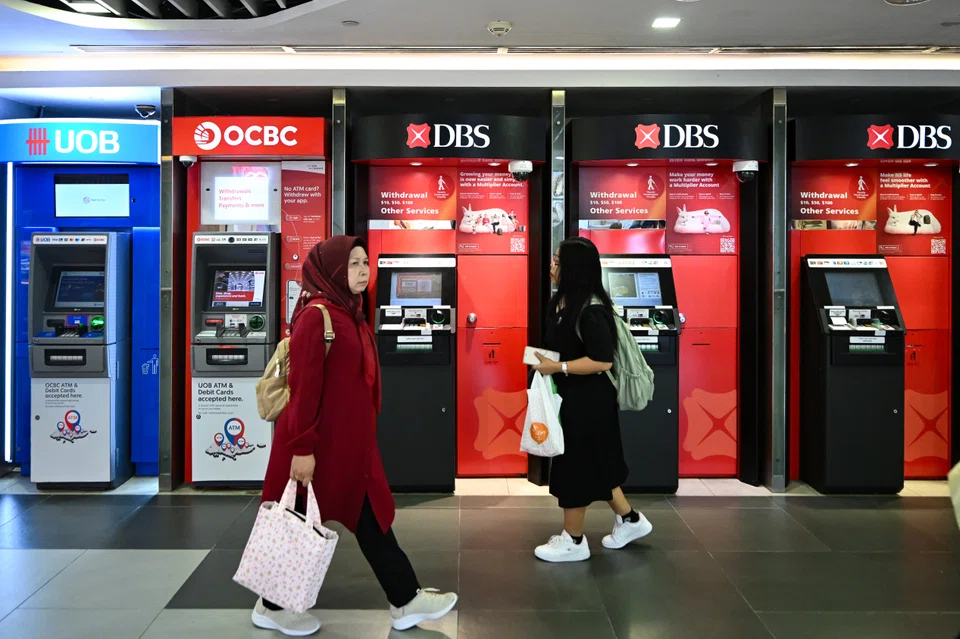
[SINGAPORE] When the US Federal Reserve hiked rates in September, some analysts said the move might help support net interest margins (NIMs) at DBS, OCBC and UOB.
Less than a month on, the most influential voices in the market are now predicting that tighter monetary conditions may actually weigh on the profitability of the three banks – and drive their share prices lower.
Notably, Citi warned last week of “misplaced optimism” surrounding higher interest rates as it lowered its earnings forecasts for OCBC, and downgraded its rating on the stock from “neutral” to “sell” – with a price target of S$27.50.






