

Don’t ‘park the bus’ with S-Reits. Now is the time for a goal rush
The worst is likely over for these ever-dependable trusts, but there could be better opportunities
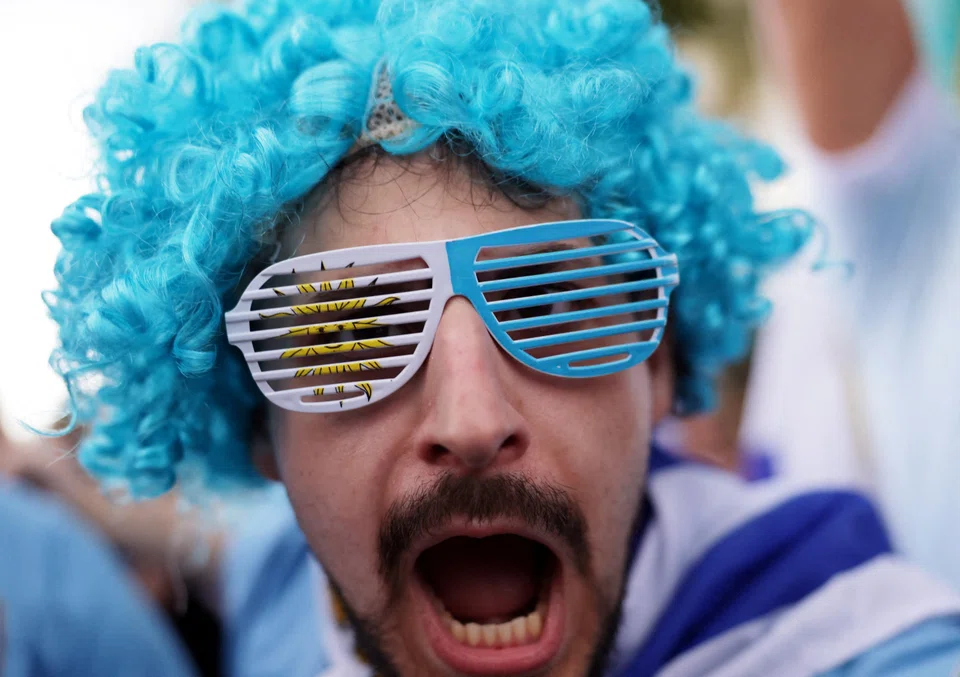
[SINGAPORE] The World Cup is upon us, and millions of armchair pundits across the island suddenly know exactly how to manage a football team.
Instinctively, every fan understands that a manager should not send his squad out to simply defend a goalless draw – a defensive tactic known as “parking the bus”.
While we celebrate the defending heroics of Cape Verde – the minnows who have now eked out draws against reigning European champion Spain, and Uruguay, who won the first Fifa World Cup in 1930 – you cannot win a tournament without sending players forward to score.
Thus, we cheer the attacking genius of Lionel Messi, Kylian Mbappe and Erling Haaland.
Yet, when the morning bell rings at the Singapore Exchange, many of us forgo our love for aggression and goals, and turn into the most cautious of tacticians.
S-Reit stalwarts
Right now, the analyst herd is cheering loudly for a defensive formation, and singing a highly comforting tune about Singapore-listed real estate investment trusts (S-Reits).
The pitch from the experts is straightforward: S-Reit valuations are simply too cheap to ignore. After all, their prices have already fallen 22.5 per cent over the last five years.
Look at the yield spread. S-Reits are now offering a buffer of roughly 4 percentage points over the 10-year Singapore government bond.
CGS International, for example, pointed out that this spread is close to one standard deviation above the historical average, making S-Reits’ valuations “compelling” after a prolonged period of underperformance.
Indeed, it is tempting to look at the numbers and declare that the worst of the S-Reits’ high-interest-rate pain has been fully priced into the market.
And analysts across the board are consistently touting heavyweights such as CapitaLand Integrated Commercial Trust and CapitaLand Ascendas Reit as top picks to ride the recovery.
S-Reits, especially these heavyweights, are the reliable centre backs of the local bourse. They are sturdy, predictable and highly unlikely to score an own goal.
Deploying your money into these property managers makes complete sense. It is the financial equivalent of parking the bus. You set up a massive wall of bricks-and-mortar assets, collect your regular dividends, and hope the opposition gets tired.
The analysts are right. S-Reits are reliable, and the worst could be behind us.
But with the local market finally shaking off its long slumber, this could be the time to play to win.
Attacking is the best defence
A genuine revival appears to be taking shape across the broader Singapore equities landscape. And if the tide is truly turning for the local market, hiding in a defensive crouch could be a waste of capital.
The numbers speak for themselves. S-Reits have fallen 5.5 per cent in the year to date. With distributions reinvested, this translates into a total return of -3.1 per cent.
In contrast, the benchmark Straits Times Index (STI) has marched 12.5 per cent over the same period, generating a total return of 15 per cent.
Playing defence when the momentum has shifted could lead to missing the rally.
We have been conditioned by years of sluggish local market performance to accept meagre returns as a victory. A 5 per cent gain feels like a triumph when you have spent a decade passing the ball sideways.
But we must break this mindset.
Even the analysts advocating for S-Reits admit it is a highly selective arena. DBS called it a “stock-picker’s market”, noting that the current environment will separate the strong trusts from the weak ones.
But if you must do the hard work of picking individual stocks, the potential reward should justify the mental effort.
Instead of looking for the best defensive formation, perhaps we should focus our attention on the goal-scoring opportunities.
Even beyond the STI heavyweights, Singapore’s smaller listed companies could provide some offensive firepower.
“For those actually looking to make money rather than just preserve it, the hunt must take place in the wider, messier pool of forgotten equities.”
Hunt for growth
The MSCI Singapore Mid Cap Index, for example, has risen 6 per cent so far this year, generating a total return of 8.4 per cent. Meanwhile, Singapore’s tranche of the next 50 largest and most liquid stocks outside the STI has advanced 4.4 per cent in the year to date.
These numbers might pale in comparison to their blue-chip counterparts. But a closer look reveals some interesting stories.
Amid a global technology and artificial intelligence boom, shares of semiconductor and electronics testing solutions provider AEM have surged 478.5 per cent in the year to date.
Other tech-related counters have also outperformed so far this year. Shares of PC Partner Group have trebled, those of UMS Integration and Frencken Group have doubled, and CSE Global shares are up 44.2 per cent.
For most of the past three years, investors fled from smaller-cap companies as borrowing costs spiked. Trading volumes dried up, leaving these smaller firms stranded.
The companies that survived this brutal period have cleaned up their balance sheets and learnt to operate incredibly leanly.
Think of them as hungry young strikers who have spent the entire season doing sprints in the rain, and are now ready to run circles around a tired defence.
Because of this recent neglect, many of these mid and small-caps have relatively cheap valuations.
Consider the nimble tech manufacturers, or the unloved consumer goods companies quietly expanding their footprint across South-east Asia. These firms have genuine, vigorous growth potential.
When market sentiment shifts and liquidity finally returns in earnest, these agile businesses will actually move the needle – easily outpacing an office or retail landlord.
Interestingly, some of the worst performers on the iEdge Singapore Next 50 Index so far this year have been S-Reits such as CapitaLand China Trust , CapitaLand India Trust , ESR-Reit , Keppel Reit and Starhill Global Reit .
So, let the timid clutch their yield spreads and celebrate a slow, grinding draw.
For those actually looking to make money rather than just preserve it, the hunt must take place in the wider, messier pool of forgotten equities.
Keep a few reliable property trusts at the back to guard the net, but push the rest of your chips forward.
S-Reits will still be there, collecting rent, when we are old and tired. Right now, the kick-off whistle has blown, and it is time to score.
TRENDING NOW
ComfortDelGro appoints two new independent directors

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

NoonTalk needs continued financial support from CEO Dasmond Koh, auditors warn
DP Architects sets the benchmark for sustainability disclosure and design

