

For ECB rate cutters, the music is as important as the words
Beyond reducing restrictive monetary policy, the central bank must really start looking after the interests of the whole euro area
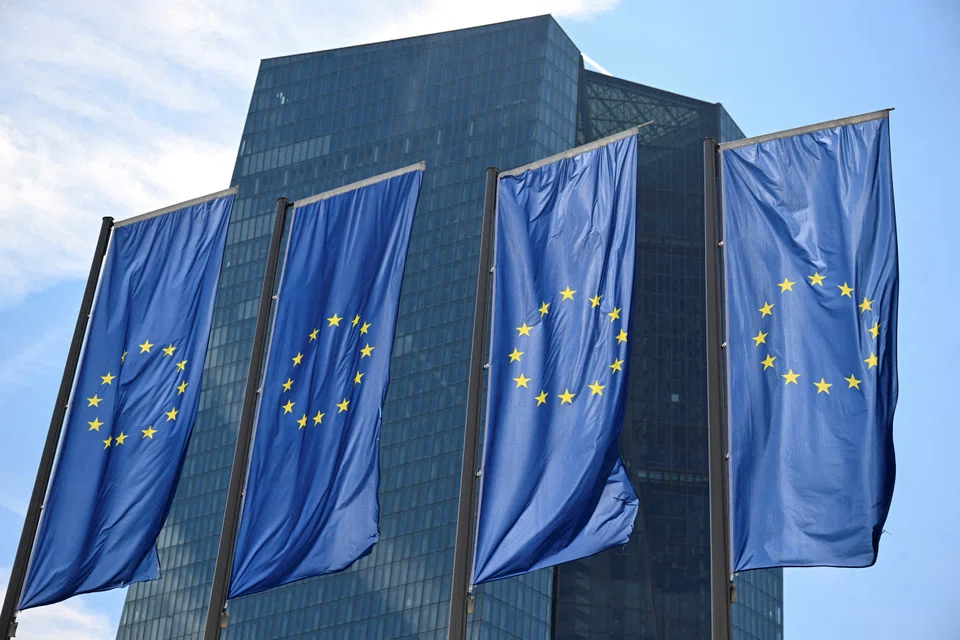
THERE aren’t many sure things in life, but a second interest-rate cut from the European Central Bank (ECB) this Thursday (Sep 12) is one of them. A 25-basis-point reduction in its deposit rate to 3.5 per cent is fully priced in by traders, and a plethora of Governing Council members have called for it. That’s why we’re focused here on what comes next, for the war on inflation is won and policymakers now have an unpleasant-looking economic downturn to combat.
It’s impressive the ECB will have cut twice ahead of the US Federal Reserve, a point that won’t be left unmentioned on Thursday in Frankfurt, I’m sure. But the ECB has so much hard work ahead if the euro area is to avoid another grim downturn. This meeting is a quarterly review with updated forecasts, featuring downward revisions on growth and inflation likely as both are notably higher than economists’ survey averages. It helps that the ECB’s negotiated wage-growth tracker has decelerated to 3.6 per cent annually in the second quarter from 4.7 per cent in the first.
The most important signal the Governing Council could send is roughly how much it expects to cut rates in the months ahead. All that takes is an explicit acceptance of what the market is already pricing in – rather than the usual series of pushbacks and handwringing. The specific timing, and how much it eases this year, are of secondary importance for the real economy. Predictability on financing costs for investment planning is the holy grail for corporates.
It’s the message that will do the heavy lifting. There’s little point in loosening monetary policy if you’re not reaping the rewards of a boost to confidence and activity. Hopefully, it hasn’t escaped policymakers’ attention that oil prices have dropped 15 per cent over the summer break – and are on track to head lower still. The risks are growing more for an undershoot of the precious 2 per cent inflation target – disinflation getting anywhere near deflation will be an economic millstone.
Framing the narrative of reducing the burden on households, corporates and state borrowing costs alike should be the theme of ECB president Christine Lagarde’s press conference. I’m not expecting her to break into song, but some confidence wouldn’t go amiss. It’s probably too much to ask for the ECB to shift emphasis to the growth and employment side of the economy like the Fed has. Executive board member Piero Cipollone of Italy, in a Le Monde interview on Wednesday, cautioned: “There is a real risk that our stance could become too restrictive. We desperately need investment and growth in Europe. Every delay in this area puts us at a serious disadvantage.”
At least one further rate cut is priced into market expectations by year-end, but with two further meetings to go, it’s unclear whether there will be a pause at its subsequent gathering on Oct 17.
The consensus on the Governing Council is for only reducing rates by quarter-point steps at a quarterly pace; that’s not going to move the economic dial. This steady-as-she-goes view was put most clearly by Lithuanian Central Bank head Gediminas Simkus in an Econostream interview on Monday, when he downplayed chances of a 50-basis-point cut. Furthermore, Simkus said “data did not correspond” to the 37 per cent market expectations priced in for another cut in October, which he called “quite unlikely”.
Of course, a surprise 50-basis-point cut by the Fed on Sep 18 would upend the ECB’s cosy consensus. A suddenly weaker US dollar will cause conniptions for euro exporters.
It’s becoming blindingly obvious that less restrictive euro area monetary conditions are needed after parlous manufacturing data out of Germany. It’s the beating engine of growth that underpins the whole euro concept. The threatened closure of Volkswagen’s German plants for the first time is just the tip of a broader industrial decline.
Boosting growth
The German representatives on the ECB are usually among the most cautious about easing up against inflation. In recent comments, neither Bundesbank head Joachim Nagel nor executive board member Isabel Schnabel commented on rates – that’s a tacit acceptance that a reduction will be waved through this week.
But they really ought to be the biggest advocates; wage growth is falling fastest in Germany, halving to 3.1 per cent in Q2 from 6.2 per cent in Q1. German consumer price growth has fallen back to 2 per cent. Although there have been some eyebrow-raising collective wage agreements earlier in the year, the ECB is confident these are backward-looking.
Prices and wages for the other three largest economies in the euro area are on a clear downtrend too. Italy’s disinflation has reasserted meaningfully with a 1.3 per cent August print, even resurgent Spain has seen a sharp drop to 2.4 per cent from 2.9 per cent in July. No more evidence is needed. The added benefit of laying out a clear path for rate cuts is taking the wind out of the sails of a strong euro, providing relief for the region’s exporters.
The ECB has been confident enough to take the first baby steps in reducing restrictive monetary policy. Now it must really start looking after the interests of the whole euro area by becoming bolder on where it sees a natural level of interest rates to enable its economy to get off its knees. The bigger risk now is recession, not a sudden re-emergence of uncontrollable inflation.
TRENDING NOW
Chairman’s role in spotlight with raft of proposed new rules for Singapore boards
Director of PR firm sacked for secretly recording internal meeting loses wrongful dismissal claim

Indonesia stocks suffer worst plunge in nearly 30 years as MSCI proposes standalone status

If Europe goes to war, the fallout will be felt in East Asia

