

Elon Musk’s US$2 trillion fiscal fantasy
Between Trump’s planned tax cuts and Musk’s absurd estimate of how much federal spending can be reduced, the smart money says they have no idea what they are doing
WHEN the US presidential election was called for Donald Trump, the yield on 10-year US government bonds increased from 4.3 to 4.4 per cent, and the 30-year-bond yield rose from 4.5 to 4.6 per cent, with both remaining at those levels 10 days later. As the bond market declined – higher yields mean lower prices – the stock market rose. Clearly, investors expect the next Trump administration to produce higher government budget deficits and more debt.
It is not difficult to see why. During Trump’s first term in office, he added US$8 trillion to the national debt – all previous presidents combined had accumulated US$20 trillion – despite having promised to run budget surpluses so large that they would eliminate the national debt within two terms.
In the campaign, he vowed to cut taxes for seemingly every group that caught his fancy. According to the Committee for a Responsible Federal Budget’s central estimate, Trump’s tax proposals imply US$10 trillion in foregone revenue over the next 10 years.
Add to that an extra US$1 trillion in interest accrued on the national debt, and the losses far exceed the US$3 trillion in added revenue that would come from the sky-high tariffs that Trump has pledged to introduce. This will require the federal government to sell a lot of bonds – a practice that will keep their price low and interest rates high.
The Republican Party line is that the lost revenue will be offset by spending cuts. It is a refrain we have heard before. In fact, Trump is continuing a 45-year tradition of Republican presidents making sweeping promises to cut government spending, which they claim will more than cover revenue losses from tax cuts. From Ronald Reagan to George W Bush – and, of course, Trump – they have all failed spectacularly.
Trump is also upholding another Republican tradition: appointing a toothless advisory commission of businesspeople.
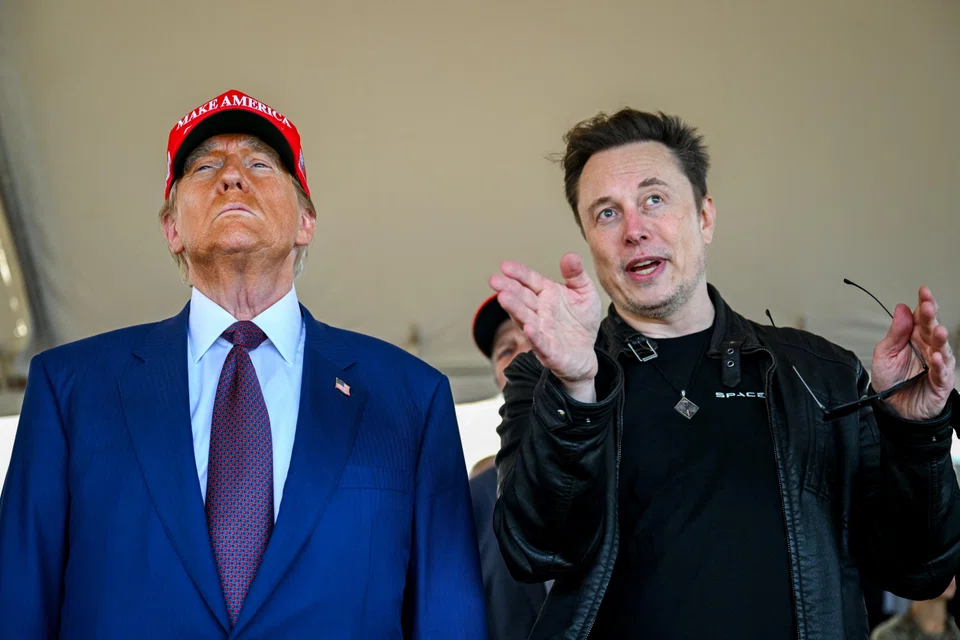
This time, it is the new Department of Government Efficiency (DOGE) – to be headed by Elon Musk and Vivek Ramaswamy – which is supposed to cut waste, fraud and abuse from the federal budget. According to Musk, DOGE will be able to slash “at least US$2 trillion” from the budget per year. This goal – which amounts to 31 per cent of annual US spending, and 7 per cent of US gross domestic product – is sheer fantasy.
Do not let the word “department” fool you: DOGE is an advisory commission, not a government department. And, though Republicans control all branches of government, its recommendations are unlikely to be enacted; they might not even develop into actionable policy proposals. But even if we put aside DOGE’s weaknesses – not to mention the massive ethical conflicts that its activities would create for Musk, the world’s richest man – the US$2 trillion figure remains absurd.
When Republicans say they want to slash federal spending, they typically specify that they will not cut mandatory programmes – so-called entitlement spending. But the major entitlement programmes – Social Security, Medicare, other healthcare programmes – accounted for half of all federal spending last year, or 61 per cent, if farm-price support and other income-support programmes are included. With retired people comprising a growing share of the population, entitlement spending in the future will only rise.
Interest payments, which account for 13 per cent of total spending, cannot be cut, either – unless the US wants to default on the national debt. (Though Trump has reveled in his ability to default on debts, having declared business bankruptcy six times, most Republicans are not interested in the US doing so.) And this bill, too, is likely to continue rising, as debt is rolled over at interest rates well above the rock-bottom rates of five or 15 years ago.
That leaves discretionary spending, which accounts for about 25 per cent of total expenditure. But if one considers defence spending untouchable – as most Republicans do – we are talking about just 12 per cent of the total budget. Can Trump and Musk find their desired savings here? Say they go fully draconian – starting by abolishing the Department of Education altogether, as Trump has pledged to do. This would reduce total spending by 4 per cent.
Then what? Maybe foreign aid. But, contrary to the impressions of many voters, aid accounts for just 1 per cent of all federal spending. Military aid to Israel – something Republicans will not touch – accounts for the largest share. Perhaps Trump would like to cut humanitarian assistance, such as famine relief, but that is just one-fifth of the total.
It is difficult to imagine abolishing the Federal Aviation Administration and other federal transportation programmes – 2 per cent of spending – but let us say Trump does it. Let us also say he eliminates all spending on the Department of the Interior (including the National Parks Service) and the Department of Commerce (including the National Weather Service).
In fact, let us imagine that the US cancels all non-defence discretionary spending. That would still not be enough to save the US federal government US$2 trillion annually, let alone pay for Trump’s tax cuts and balance the budget.
None of this is to say that US budget deficits – which are currently running in excess of 6 per cent of GDP – do not need to be reduced. With the debt-to-GDP ratio having climbed steadily since 1981 – punctuated by temporary declines in 1994 to 2000 and 2021 to 2022 – the national debt is undoubtedly on an unsustainable path. Since last year, the gross debt-to-GDP ratio has broken the record set in 1946, at the end of World War II, and its rise is set to accelerate.
Trump’s next administration – with the sweeping tax cuts it is sure to introduce – will be a powerful driver of this trend. Financial markets might be buoyant now, but eventually – and perhaps before too long – they will come to appreciate the unsustainability of US debt. At that point, Social Security and other entitlement spending will be cut far more sharply than if they were cut now, or if taxes were not cut.
Supporters often say that a businessman like Trump or Musk will know how to put America’s fiscal house in order. But the smart money says they have no idea what they are doing. PROJECT SYNDICATE
The writer, professor of capital formation and growth at Harvard University, served as a member of President Bill Clinton’s Council of Economic Advisers. He is a research associate at the US National Bureau of Economic Research.
TRENDING NOW
From AI financing to Indonesia outlook: 4 takeaways from Singapore banks’ Q3 results

VinFast, Mitsubishi weigh Philippine EV production as state incentives near

Analysts cut DBS target price on lower 2027 earnings, but see buying opportunity after share price slide

Could Japan trigger the next global financial crisis?

