

With the Fed likely to stand pat on rates, investors will scrutinise every detail for any deviation on policy
This time, unlike at previous high-stakes meetings, no one expects to see any surprises
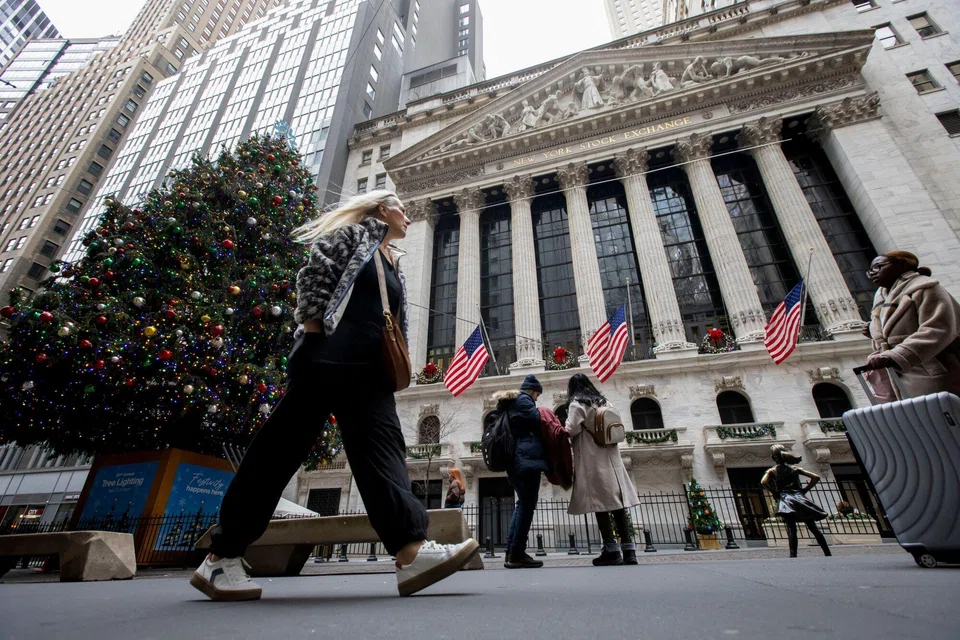
THE US Federal Reserve is likely to leave interest rates unchanged this week that you can almost hear a collective yawn on Wall Street.
This time, unlike at previous high-stakes meetings, no one expects to see any surprises. The Fed will almost certainly keep the Fed-funds benchmark rate between 4.25 and 4.5 per cent at the end of its first two-day meeting of 2025 on Wednesday (Jan 29).
There isn’t expected to be any update on the rate-setting committee’s official policy outlook. As in December, Fed chairman Jerome Powell is likely to acknowledge the remarkable resilience of the US economy and the slight uptick in consumer prices, and to vow data dependence.
Still, the Fed meeting could cause some major swings on the US stock and bond markets.
Investors will scrutinise the Fed’s statement and Powell’s press conference for the slightest deviation from previous assessments of policy and the US economy.
For example, they will be looking for signs of whether the Fed might lean towards one or more interest rate cuts this year. They will monitor Powell’s tone and emphasis on inflation worries and rising unemployment.
“Current data may suggest a less hawkish stance than in December,” said Christian Scherrmann, the chief US economist at money manager DWS, in a note to clients. “Recent inflation data keeps the door open for further, but limited, rate cuts and labour markets – despite robust hiring – are not currently a source of inflationary pressure.”
The US economy is a bit like Rocky in the first Sylvester Stallone film of the same name that was released nearly a half-century ago in 1976. It doesn’t have much going for it, battered by years of hyperinflation and aggressive rising credit costs.
Most observers are braced for its collapse. Yet, this “Rocky economy” just refuses to go down to the mat. This has created something of a paradox. The same stubborn economic growth that is fuelling earnings growth and stock gains is driving up Treasury yields, as investors in the bond market position themselves for either a return of inflation, or a Fed decision to stop cutting rates – or both.
Even more significant than the statement or the press conference this time around could be the Treasury market’s reaction to the Fed’s words.
Yields on the Treasury market have risen steadily since the last central bank meeting because of surprisingly strong inflation and economic data. The stock market remains optimistic that the central bank will resume rate cutting, with the broad S&P 500 closing at a record high on Jan 23.
But experienced investors know that the Treasury market is like the stock market’s more prudent older brother. When the two take a different interpretation of economic trends, the Treasury market’s view usually prevails. Even if the bond market’s fears are misplaced, elevated yields can hurt economic growth.
Responding to the Treasury market
While the Fed funds rate is crucial to banks because it determines the cost of borrowing for their daily operations, Treasury yields are what determine the cost of consumer borrowing.
Almost every stock-market sell-off in the volatile period since the election of President Donald Trump was a response to a move in the Treasury market.
One big worry is that Trump’s apparent attempt to bully China, Canada and Mexico into trade concessions by using the threat of tariffs fails. Most economists say a major increase in tariffs would cause another bout of inflation.
Jim Paulsen, a veteran Wall Street strategist, dissents from this view. He said the moves in the US dollar have been so dramatic that imports priced in the yuan, Canadian dollar and peso are effectively getting cheaper. Any tariffs, at this stage, would effectively be a wash for US import costs.
Paulsen added that Powell is likely looking for any opening in the data to return to the rate-cutting cycle that began with the three consecutive rate cuts late last year.
“They can’t do it right now,” said Paulsen. “Not with the market view being concerns of inflation and overheated growth.”
But Powell is seen as eager to cut rates at some point, largely to make up for prior mistakes that got Fed policy out of sync with the economy, said Paulsen.
“Current data may suggest a less hawkish stance than in December. Recent inflation data keeps the door open for further, but limited, rate cuts and labour markets – despite robust hiring – are not currently a source of inflationary pressure.”
Christian Scherrmann, chief US economist at money manager DWS
The Fed waited much longer than economists believed prudent before responding to the pandemic-era inflation, insisting that it was “transitory”. Powell’s Fed then made the markets play a guessing game for almost a year as inflation fell steadily, before finally pivoting to rate cuts in September.
“I call it the backwards Fed,” said Paulsen. “When inflation hit 8.5 per cent in April 2022, a month before it peaked, the Fed had not yet started to raise rates.”
The central bank then kept raising rates throughout 2022 and some of 2023, even as inflation weakened month after month – an unprecedented move.
“They were behind on the up and behind on the down, and now what trying to do is get back into normalcy, but they can’t quite get back into sync,” said Paulsen.
Usually, when the Fed is looking at steady economic growth and an inflation rate above the 2 per cent annual comfort zone, there would be no question of an interest rate cut. But, this time, Powell may be trying to bring rates down to “neutral” level after a sense that the Fed overdid its rate-hiking cycle.
Any hint of dovishness from the Fed on Wednesday would be a pleasant surprise for Treasury markets. And any downward move in rates in the wake of the statement would likely spark a major stock-market rally.
The second Trump era
The other reason to expect some action on Fed day is that markets have now entered the second Trump era. Powell may or may not provide an assessment of the Trump administration’s tariff strategy. But Trump will almost certainly weigh in on Powell’s performance.
These two men hold the fate of the 2024-25 bull market in their hands, said one money manager.
“Supportive policy and sustained productivity gains hold the key for the regime lasting all decade,” said Jason Draho, the head of asset allocation (Americas) at UBS Global Wealth Management.
Should the stock-market leap in celebration of any dovish signals, it may soon come tumbling back down to earth.
“What remains is policy uncertainty,” said Scherrmann, of DWS.
TRENDING NOW

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Malaysian developer Eco World tops bids for Sin Ming area housing plot with S$1,612 psf ppr offer
As China trust-tax deadline looms, wealthy clients explore options across Asia

